Cash, Term Deposits and Money Market Funds in Australia: Compare Cash Investments
Looking for the best cash investments, term deposits or money market funds in Australia? We don’t rank them. Below are term deposits, cash ETFs and cash funds, filterable by category, objective and investor type, with rates, fees and the offer document where the issuer has published them.
Use the filters to narrow the listings, open the ones that suit your goal and compare them on their own numbers. Everything on this page is general information only, not personal advice, so consider your circumstances and read the offer document before you invest.
Key Takeaways
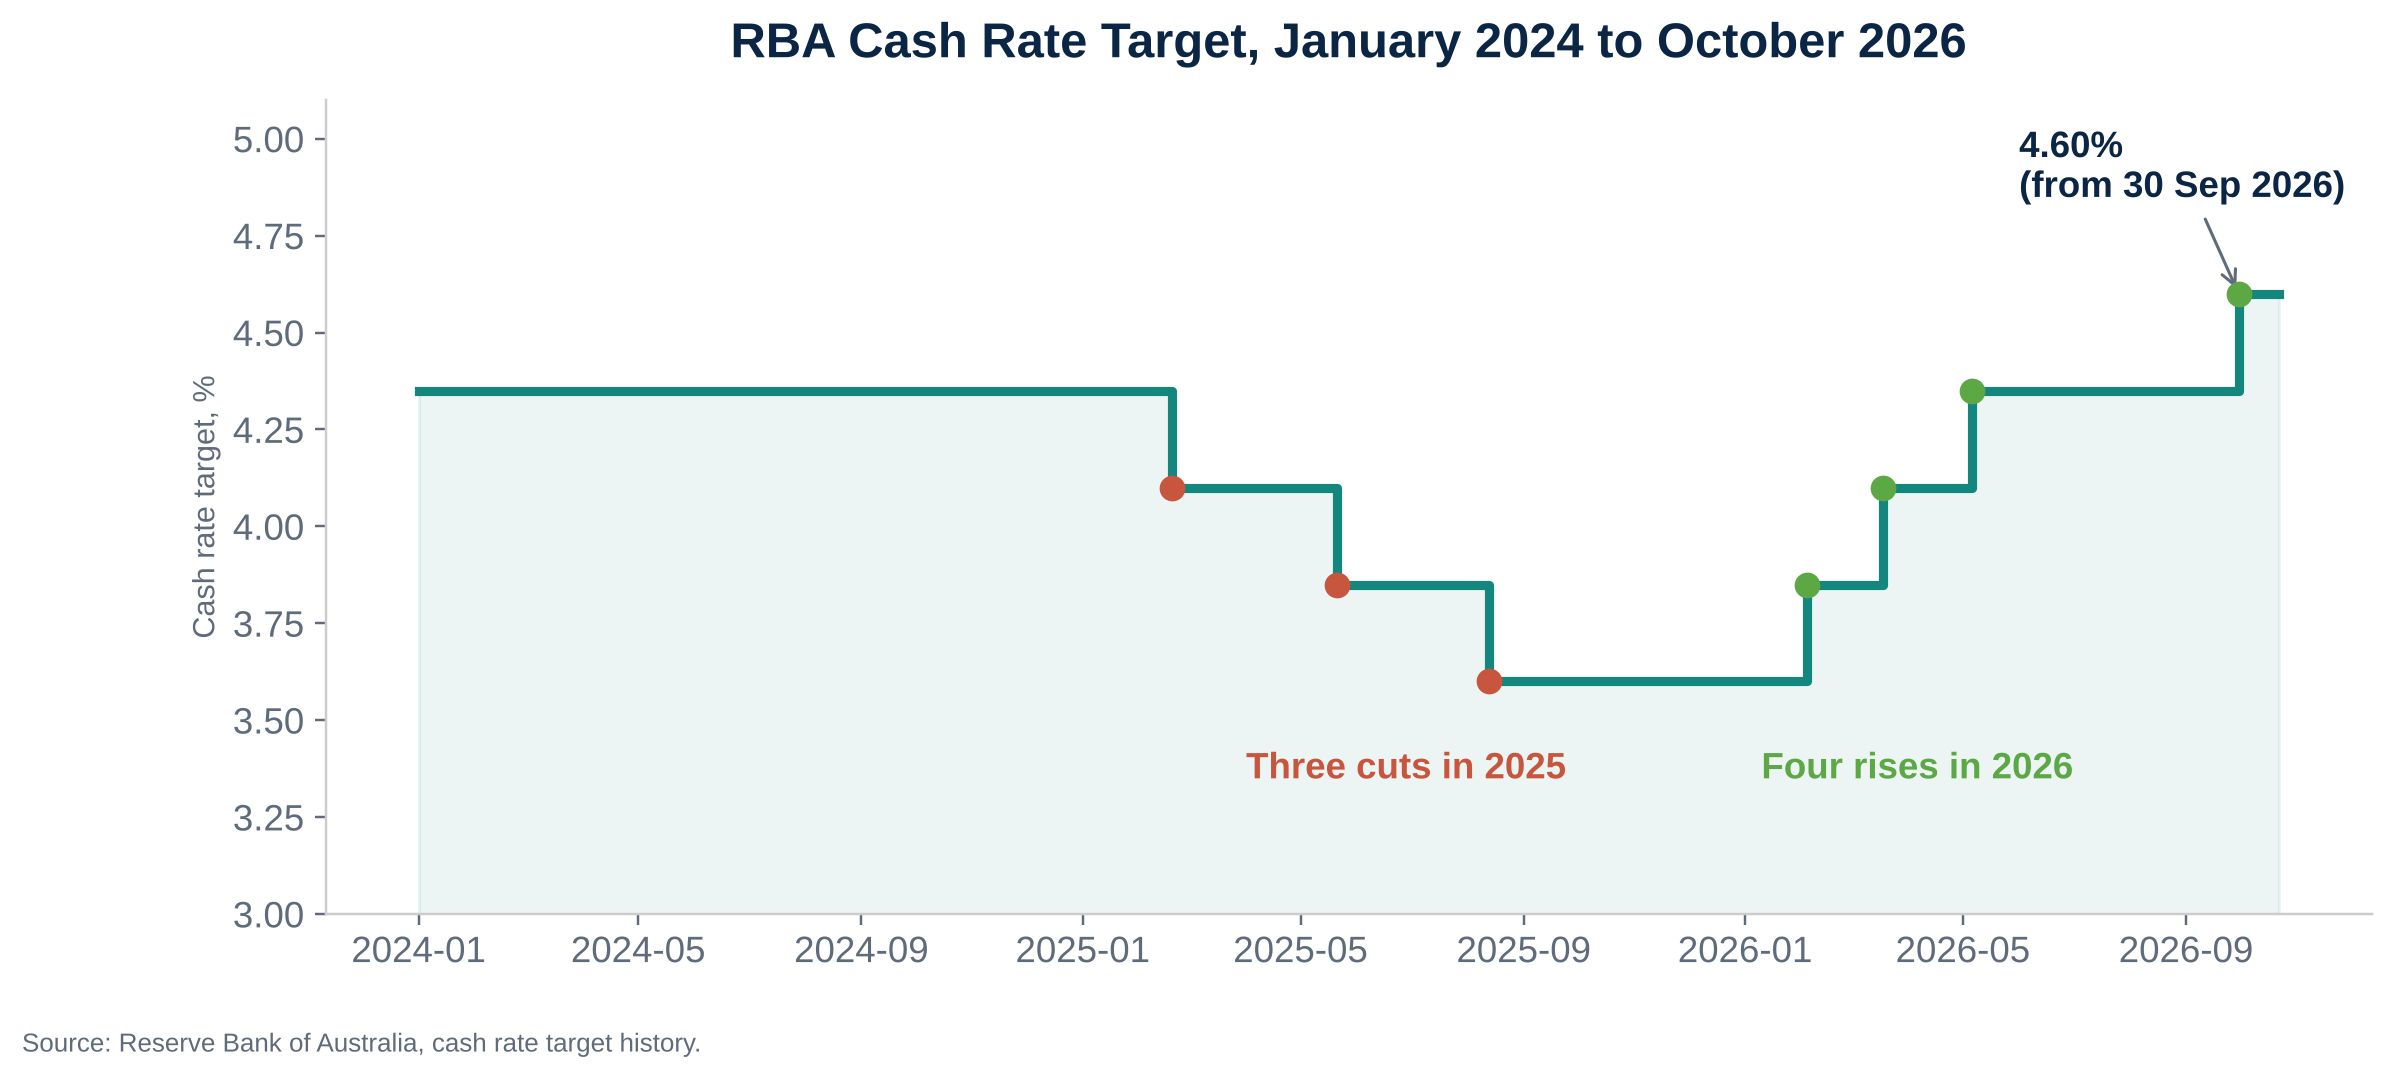
▪ The RBA cash rate target is 4.60%, effective 30 September 2026, after four rate rises in 2026 (Reserve Bank of Australia).
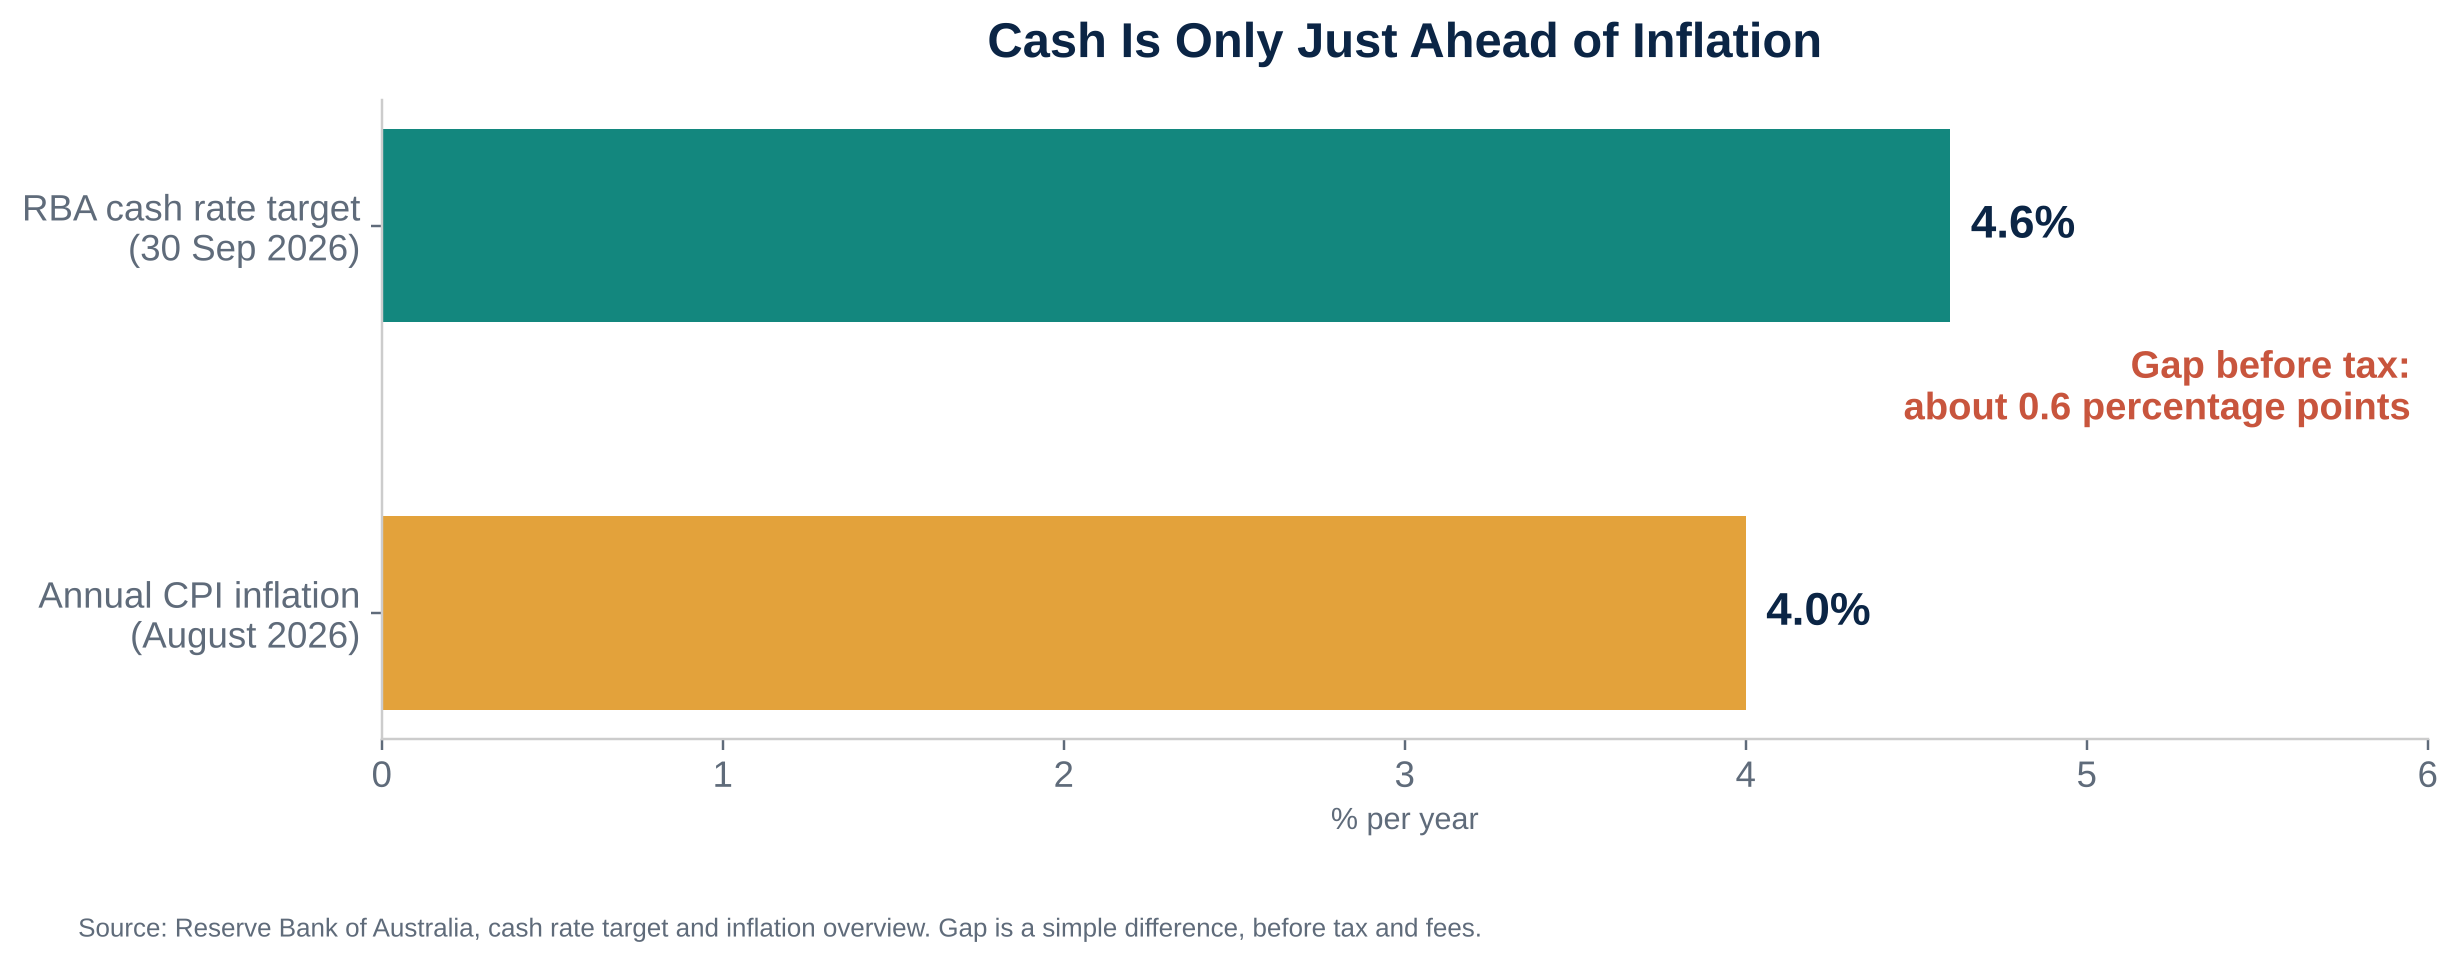
▪ Annual CPI inflation was 4.0% in August 2026 (RBA), so cash is only just ahead of inflation before tax.
▪ Bank deposits, including term deposits, are protected by the government’s Financial Claims Scheme up to $250,000 per account holder, per institution (APRA). Cash ETFs and cash funds are not.
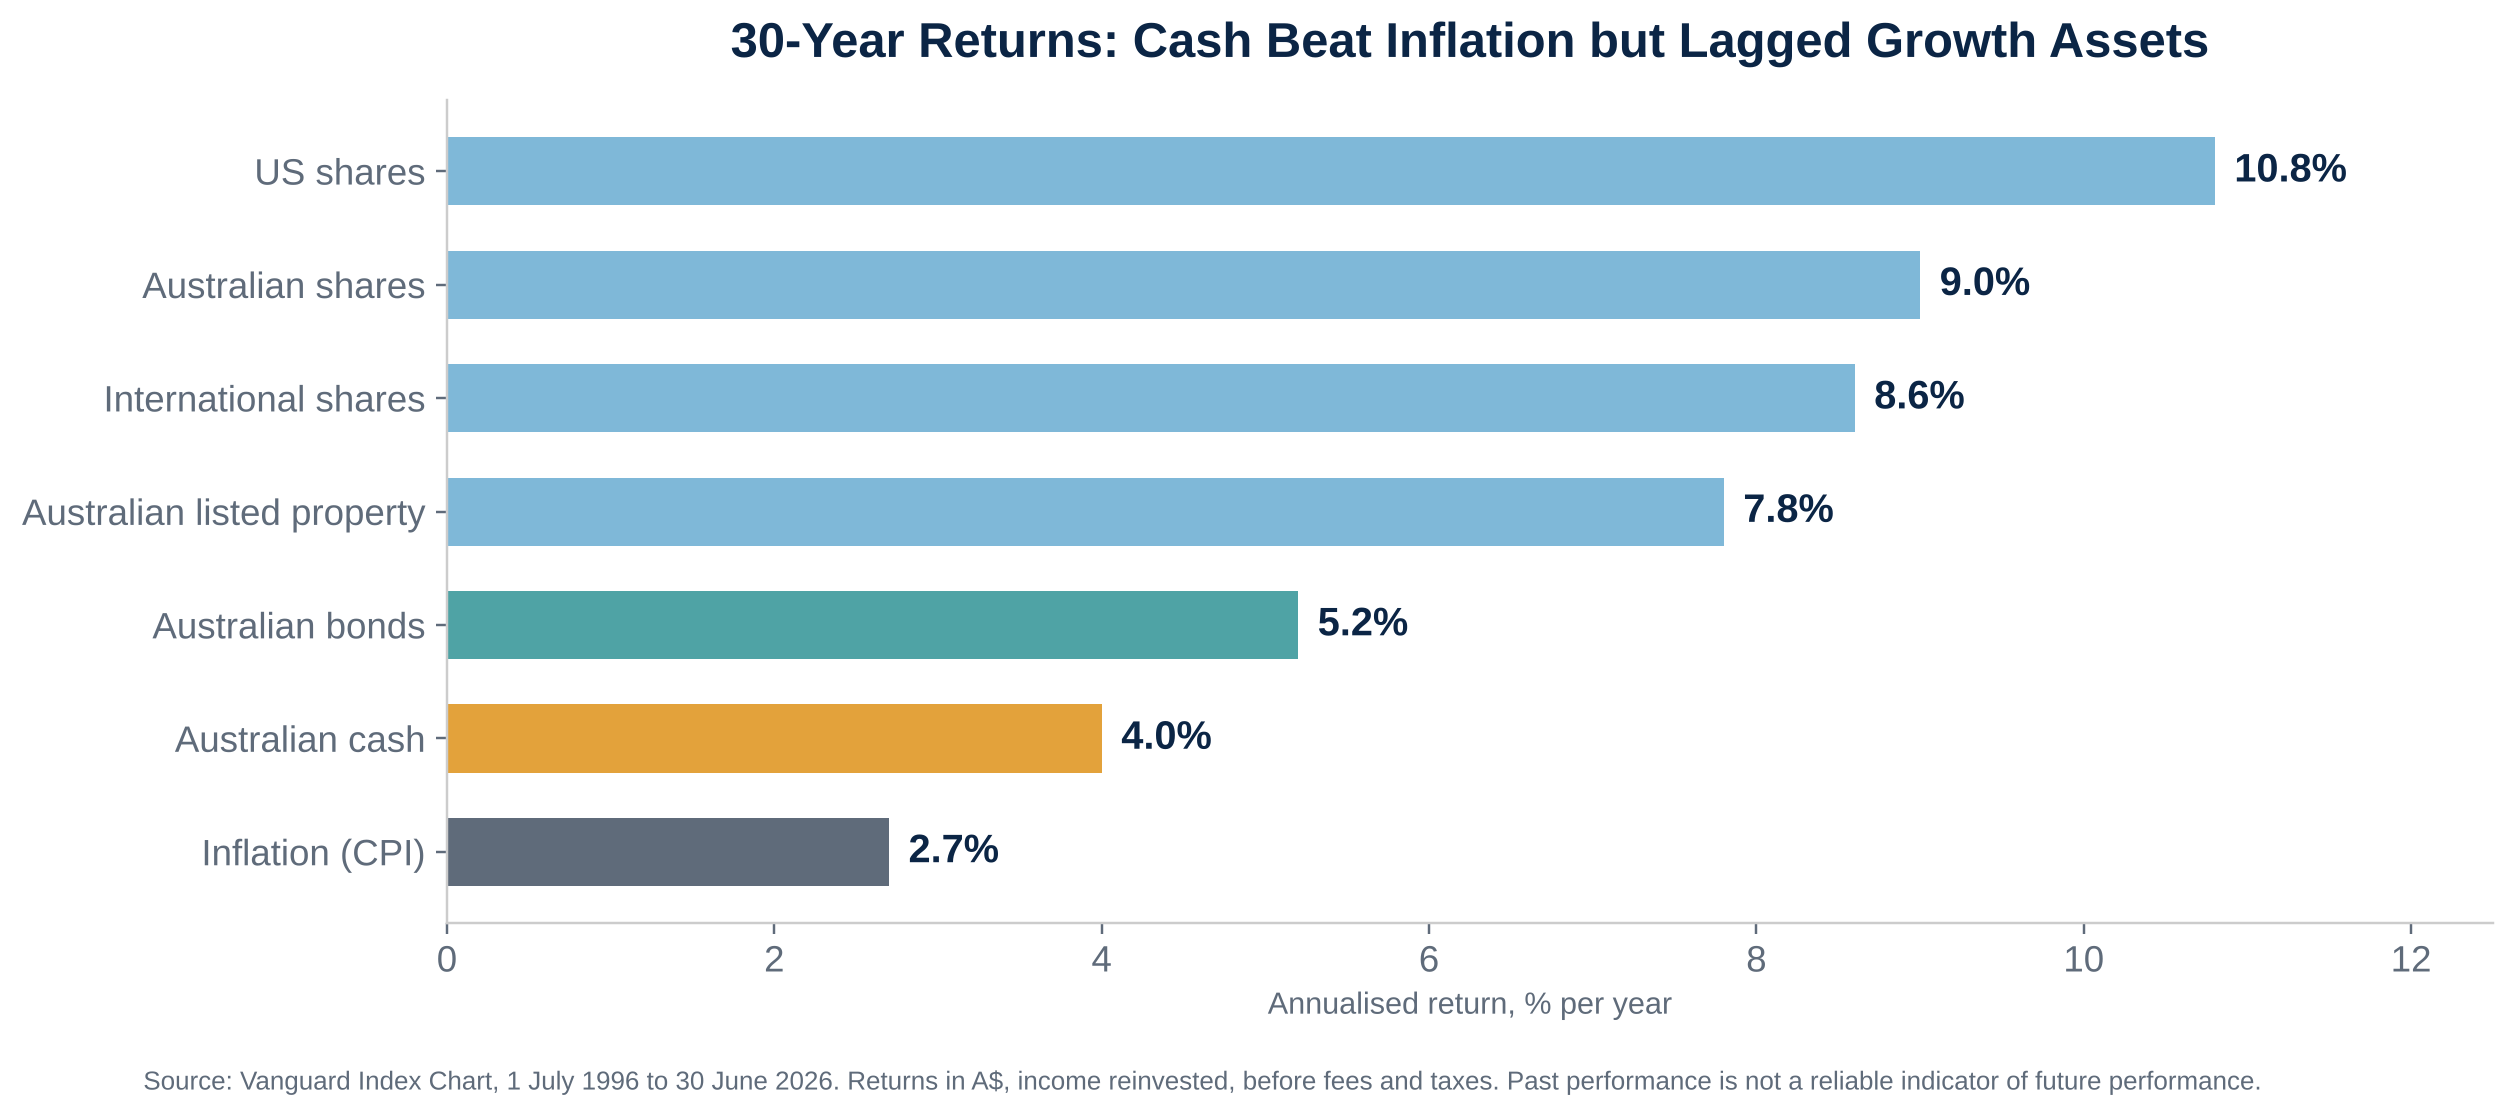
▪ Over the 30 years to June 2026, Australian cash returned 4.0% a year against 2.7% inflation and 9.0% for Australian shares (Vanguard).
▪ Choose between at-call savings, term deposits, cash ETFs and cash or money market managed funds based on return after fees, access, protection and what each one holds.
▪ Cash is a short-term home for money you need soon, an emergency buffer or the first bucket of a retirement income plan. It is rarely a long-term growth engine.
What Are the Best Cash Investments, Term Deposits and Money Market Funds in Australia?
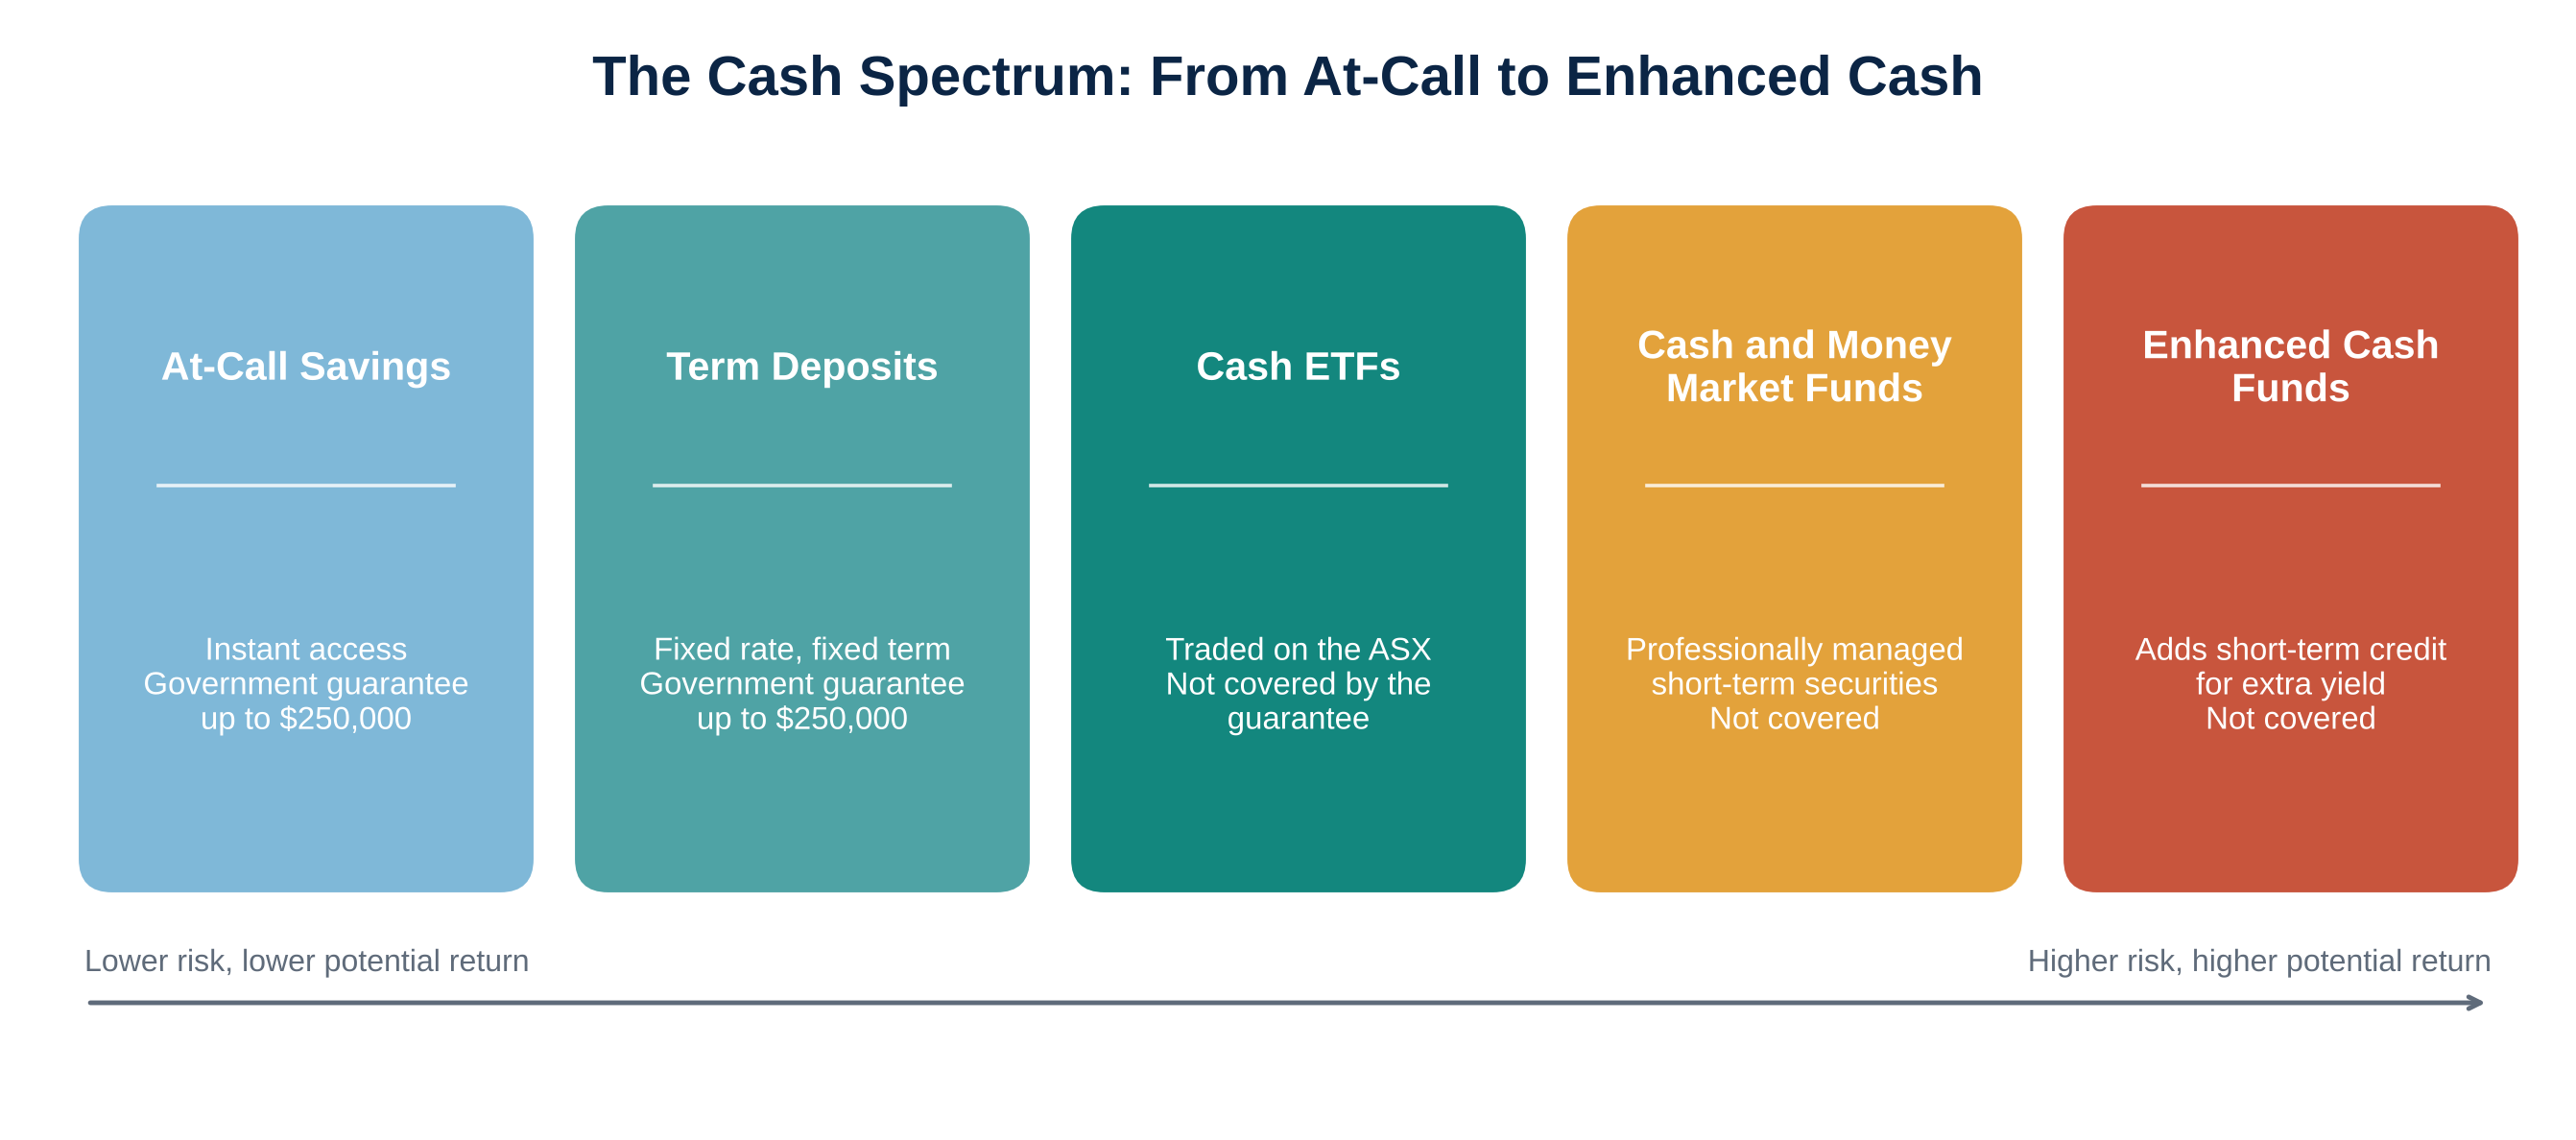
There is no single best cash investment. The right choice depends on how soon you need the money, whether you want the government guarantee, and how much extra return you will accept for extra risk. A term deposit locks in a fixed rate. A cash ETF trades daily on the ASX. A cash or money market fund pools money into short-term securities managed by a professional. Enhanced cash funds add some short-term credit for extra yield.
Start with the job you want your cash to do, then browse the matching listings.
If You Want To…
Consider
Browse
Lock in a rate with the government guarantee
Term deposits with an Australian bank, building society or credit union
How Do I Compare Cash Investments on InvestmentMarkets?
Filter the listings by category, objective (such as income) and investor type (retail or wholesale). Where the issuer has published them, listings show rates or yields, fees, performance figures and the offer document, along with the minimum investment, liquidity and structure. Open a listing to read the detail or enquire directly with the issuer.
Five checks to run before you choose where to hold your cash.
What To Compare
Why It Matters
Where To Find It
Rate or yield after fees
A headline rate means little if fees eat into it. Compare net returns.
Listing, where the issuer has published it, and the offer document
Fees and costs
Management fees on cash funds and ETFs, and account fees on deposits, reduce what you keep.
Listing, where the issuer has published them, and the offer document
Access and liquidity
At call, daily ASX trading, notice periods or a fixed term all affect how fast you can get your money.
Listing and offer document
Government guarantee
Bank deposits are covered up to $250,000 per person per institution. Funds and ETFs are not.
▪ Show issuer figures such as rates, fees and performance, and link to the offer document, where the issuer has published them.
▪ Let you filter by category, objective and investor type.
▪ Connect you directly with issuers so you can ask questions before you invest.
▪ Publish independent fixed income articles and investor education to help you make better decisions.
What We Don’t Do
▪ Rank cash products or tell you which one to choose.
▪ Provide personal financial advice. Information here is general only.
▪ Guarantee any rate or return. Rates can change, and only bank deposits carry the government guarantee.
What Are Cash and Money Market Investments?
Cash and money market investments hold liquid, low-risk assets that earn interest. They sit between an everyday savings account and more complex investments such as bond funds or income funds. Money markets are where banks, governments and companies borrow and lend for short periods, usually less than a year, through instruments such as bank deposits, bank bills, negotiable certificates of deposit and short-term government securities. Cash investments give you access to these rates either directly through a bank, or indirectly through a fund or ETF.
Cash options range from guaranteed bank deposits to funds that add a little credit risk for extra yield.
What Are the Different Types of Cash Investments?
At-Call and High-Interest Savings Accounts
Bank accounts that pay interest and let you withdraw at any time. Rates are variable and some accounts pay bonus interest only if you meet conditions such as a monthly deposit. These accounts are covered by the government guarantee.
Term Deposits
Term deposits lock your money away for a fixed term, from one month to five years, at a fixed rate. Breaking one early usually requires notice and costs interest. For example, Macquarie requires at least 31 days’ notice and may charge a fee of 25% of interest accrued on its standard term deposit. Term deposits with an Australian bank, building society or credit union are covered by the government guarantee.
Cash ETFs
Cash ETFs trade on the ASX like shares. Some hold bank deposits, others hold short-term money market securities, and some actively managed or enhanced versions add short-term credit. You can buy or sell during trading hours, though you pay brokerage and the bid-ask spread. They are not covered by the government guarantee.
Cash managed funds pool investors’ money into bank deposits, bank bills and short-term securities. They often offer easy access, usually within a few business days, and are popular with platforms, SMSFs and wholesale investors. They are not covered by the government guarantee.
Enhanced Cash and Short-Term Income Funds
These funds aim to beat the cash rate by adding short-dated corporate bonds, asset-backed securities or other credit. The extra return comes with extra risk, including the chance of capital losses in a credit downturn. They sit closer to income funds and diversified income funds than to bank deposits.
Cash accounts held with a broker or investment platform to settle trades and receive income. Rates vary widely, and some pay well below the cash rate, so check before you leave large balances sitting idle.
What Is the RBA Cash Rate Today and Why Does It Matter?
The Reserve Bank of Australia cash rate target is 4.60%, effective 30 September 2026. It is the anchor for what banks pay on deposits and what cash funds earn. The RBA cut the rate three times in 2025, to 3.60%, then raised it four times in 2026 as inflation stayed high. In its 29 September 2026 decision, the Board said further increases may follow if needed.
When the cash rate rises, new term deposit rates and cash fund yields generally follow, though not always in full. When it falls, returns on cash fall quickly too.
Major banks expect rate cuts from 2027, which is one reason some investors lock in longer-term deposits or move part of their cash into bond funds.
Only just, right now. Annual CPI inflation was 4.0% in August 2026, against a 4.60% cash rate, a gap of about 0.6 percentage points before tax. After tax at your marginal rate, many investors earn a negative real return on cash.
Over the long run, cash has kept ahead of inflation but lagged growth assets by a wide margin. Vanguard’s Index Chart shows Australian cash returned 4.0% a year over the 30 years to 30 June 2026, compared with 2.7% inflation, 5.2% for Australian bonds and 9.0% for Australian shares. $10,000 in cash grew to $32,459, while the same amount in Australian shares grew to $132,931.
Source: Vanguard Index Chart. Past performance is not a reliable indicator of future performance.
Bank deposits are; cash funds and ETFs are not. The Financial Claims Scheme protects deposits with Australian banks, building societies and credit unions up to $250,000 per account holder, per institution, according to APRA. It covers transaction, savings and cheque accounts, term deposits and separate mortgage offset accounts, held by individuals, companies, trusts or SMSFs. If the scheme is activated, APRA aims to pay account holders within seven calendar days.
Cash ETFs, cash funds and enhanced cash funds are investment products, not deposits, so the scheme does not cover them even when they hold bank deposits. Their safety depends on what they hold and how they are managed. If you hold more than $250,000 in deposits, spreading it across separately licensed institutions keeps more of it within the guarantee.
What Are the Benefits of Cash and Money Market Investments?
▪ Capital stability: cash investments aim to protect your capital, with little or no movement in value.
▪ Liquidity: at-call accounts, cash ETFs and most cash funds give quick access to your money.
▪ Regular income: interest is usually paid monthly, quarterly or at maturity.
▪ Government guarantee: bank deposits, including term deposits, are covered up to $250,000 per account holder per institution.
▪ Portfolio ballast: cash cushions a portfolio in market sell-offs and gives you money to deploy when opportunities appear. Read Patience Is an Investment Decision.
What Are the Risks of Cash and Money Market Investments?
▪ Inflation risk: returns may not keep pace with rising prices, especially after tax.
▪ Reinvestment risk: when rates fall, maturing term deposits roll over at lower rates and cash fund yields drop.
▪ Access limits:term deposits need notice to break early and can cost interest. Some savings accounts cap withdrawals or bonus interest.
▪ No guarantee on funds:cash ETFs and cash funds are not covered by the Financial Claims Scheme.
▪ Opportunity cost: holding too much cash for too long can leave you well behind growth assets over time.
How Can I Invest in Cash in Australia?
You can access cash through banks, building societies and credit unions; through the ASX via a broker; or through fund managers and investment platforms.
Many SMSFs hold a mix. Browse SMSF investments to see options suited to self-managed funds.
A term deposit ladder splits your money across several maturities so part of it becomes available at regular intervals. As each rung matures, you either use the cash or reinvest it at the longest term. A ladder reduces the risk of locking everything in just before rates rise, and of rolling everything over just after they fall.
Illustrative example only. Not a recommendation.
The same idea can be extended into bonds and other income assets.
It depends on your goals, time frame and need for access. Common approaches are an emergency fund of three to six months of expenses, plus cash set aside for known spending in the next year or two. In retirement, a three-bucket approach holds cash for spending needs in the next few years, defensive assets for the medium term and growth assets for the long term, as explained in How a 3-Bucket Strategy Can Help Optimise Retirement Income.
Cash usually forms the first bucket of a retirement income plan.
Should I Choose Cash, Bonds or Private Credit for Income?
Each does a different job. Cash offers stability and access. Bond funds and bond fund ETFs can lock in yields for longer and may rise in value if rates fall, but their prices move. Private credit and mortgage funds can pay more, but carry credit and liquidity risk. With Australian 10-year government bond yields around 5.4%, longer-dated income looks more competitive than it has for years.
Cash, term deposits and money market funds give you stability, liquidity and income, and with the RBA cash rate at 4.60% they pay more than they have for much of the past decade. But with inflation at 4.0%, cash only just keeps pace before tax, and over the long run it has lagged growth assets. Decide what job your cash needs to do, check whether it is covered by the government guarantee, and compare returns after fees.
Use the listings on this page to compare the term deposits, cash ETFs and cash funds available, then judge each one on its numbers.
Investing in Cash & Money Market Accounts FAQs:
A money market account or fund typically invests in short-term securities and may pay a higher rate than a standard savings account, though it may have higher minimum balances or limits on transactions. A bank savings account is a deposit covered by the government guarantee, while a money market fund is not.
Deposits with Australian banks, building societies and credit unions, including term deposits, are covered by the Financial Claims Scheme up to $250,000 per account holder, per institution. Cash ETFs, cash funds and money market funds are not covered.
Usually, yes. At-call accounts give instant access, cash ETFs trade daily on the ASX, and most cash funds pay out within a few business days. Term deposits are the exception: you typically need to give notice and may lose some interest to withdraw early.
Some accounts charge a fee or pay a lower interest rate if your balance drops below a set minimum. Check the terms or offer document before you open an account.
Some savings accounts charge monthly fees, particularly if conditions are not met. Cash ETFs and cash funds charge management fees, and ETFs also involve brokerage. Where the issuer has published them, listings on this page show fees.
Most savings accounts and cash funds pay monthly. Term deposits may pay monthly, quarterly, annually or at maturity, and rates are sometimes lower if you choose more frequent payments.
It ranges from nothing for many savings accounts, to the price of one unit for a cash ETF, to thousands or tens of thousands of dollars for some term deposits and cash funds. Wholesale funds usually require larger amounts and wholesale investor status.
Yes. Their liquidity and capital stability make at-call savings and other easily accessible cash a sensible home for an emergency fund. Avoid locking emergency money in a term deposit you may need to break.
The RBA cash rate target is 4.60%, effective 30 September 2026, according to the Reserve Bank of Australia.
A term deposit is a bank deposit with a fixed rate and term, covered by the government guarantee. A cash ETF is an investment fund traded on the ASX with a variable yield, daily liquidity and no government guarantee.
No. Enhanced cash funds hold some short-term credit to earn extra return, which means they can fall in value if borrowers default or credit markets come under stress. Check the offer document to see what the fund holds.
Yes. SMSFs commonly hold term deposits, cash ETFs and cash funds, subject to the fund’s investment strategy. The government guarantee applies to SMSF bank deposits up to $250,000 per institution. Browse SMSF investments.
That depends on your view of rates and your need for access. Locking in protects you if rates fall, but costs you if rates keep rising. A ladder of maturities spreads that risk. This is general information only, so consider seeking advice.
Disclaimer: This article is prepared by Simon Turner. It is for educational purposes only. While all reasonable care has been taken by the author in the preparation of this information, the author and InvestmentMarkets (Aust) Pty. Ltd. as publisher take no responsibility for any actions taken based on information contained herein or for any errors or omissions within it. Interested parties should seek independent professional advice prior to acting on any information presented. Please note past performance is not a reliable indicator of future performance.
AAA aims to provide attractive, regular income distributions and a high level of capital security via cash held in Australian dollar interest bearing bank deposit accounts.
The Fund provides an opportunity for Wealth Managers to access cash-based products designed with specific considerations to their core needs across returns, liquidity, administration, and reporting. (For Wholesale Investors Only)
The Fund employs a passive investment strategy that aims to provide investors with the performance of the S&P/ASX Bank Bill Index (before fees and expenses). The Fund offers the ability to achieve capital preservation and regular income with a diversified portfolio of high quality short-term money market instruments. The Fund is truly liquid and only holds investments in instruments that can be sold on a same day basis.
MMKT aims to generate a yield (before fees and expenses) that exceeds the Bloomberg AusBond Bank Bill Index, paid monthly, from a portfolio of Australian dollar cash and short-term money market securities issued by investment grade entities.
The Fund uses a passive investment strategy aimed to provide investors with performance, before fees and expenses, that is broadly aligned with, and which may exceed, the performance of an index comprised of Australian bank bills.