COMMODITIES INVESTING IN AUSTRALIA: AN INVESTOR'S GUIDE TO GOLD, ENERGY, METALS AND REAL ASSETS
For most of the 2010s, commodities were the asset class institutional Australia tended to ignore. Zero interest rates rewarded duration, growth equities compounded relentlessly, and a barrel of oil or an ounce of gold looked like dead capital next to a Nasdaq index fund. That calculus has changed. Since 2022, Australian investors have lived through a genuine regime shift. With persistent (if moderating) inflation, a fracturing of global trade relationships, central banks accumulating gold at the fastest pace in decades, and bond markets that no longer behave as the reliable ballast they were for the previous forty years, the setting now favours commodities investing.
This is significant for most Australian investors. The Australian share market is itself heavily commodity-linked, dominated by miners, energy producers and financials whose fortunes are tied to the same cycles. As such, an investor who believes they are diversified because they hold an ASX 200 index fund alongside term deposits may be more concentrated in commodity-cycle risk than they realise, simply expressed through equity and bank balance sheets rather than the commodities themselves.
Commodities are not a bet on the direction of a single price. Used properly, they are a structural hedge against the risks a conventional equity and bond portfolio cannot absorb: inflation shocks, currency devaluation, and geopolitical disruption to physical supply chains.
This report is a practical guide to commodities as an asset class for Australian investors: what they are, how they behave statistically inside a portfolio, the vehicles available to access them on the ASX and beyond, the tax and structural trade-offs each involves, and the mistakes that catch out even experienced investors.
Table of Contents
A BRIEF HISTORY LESSON: WHAT THE LAST THREE COMMODITY CYCLES TEACH US
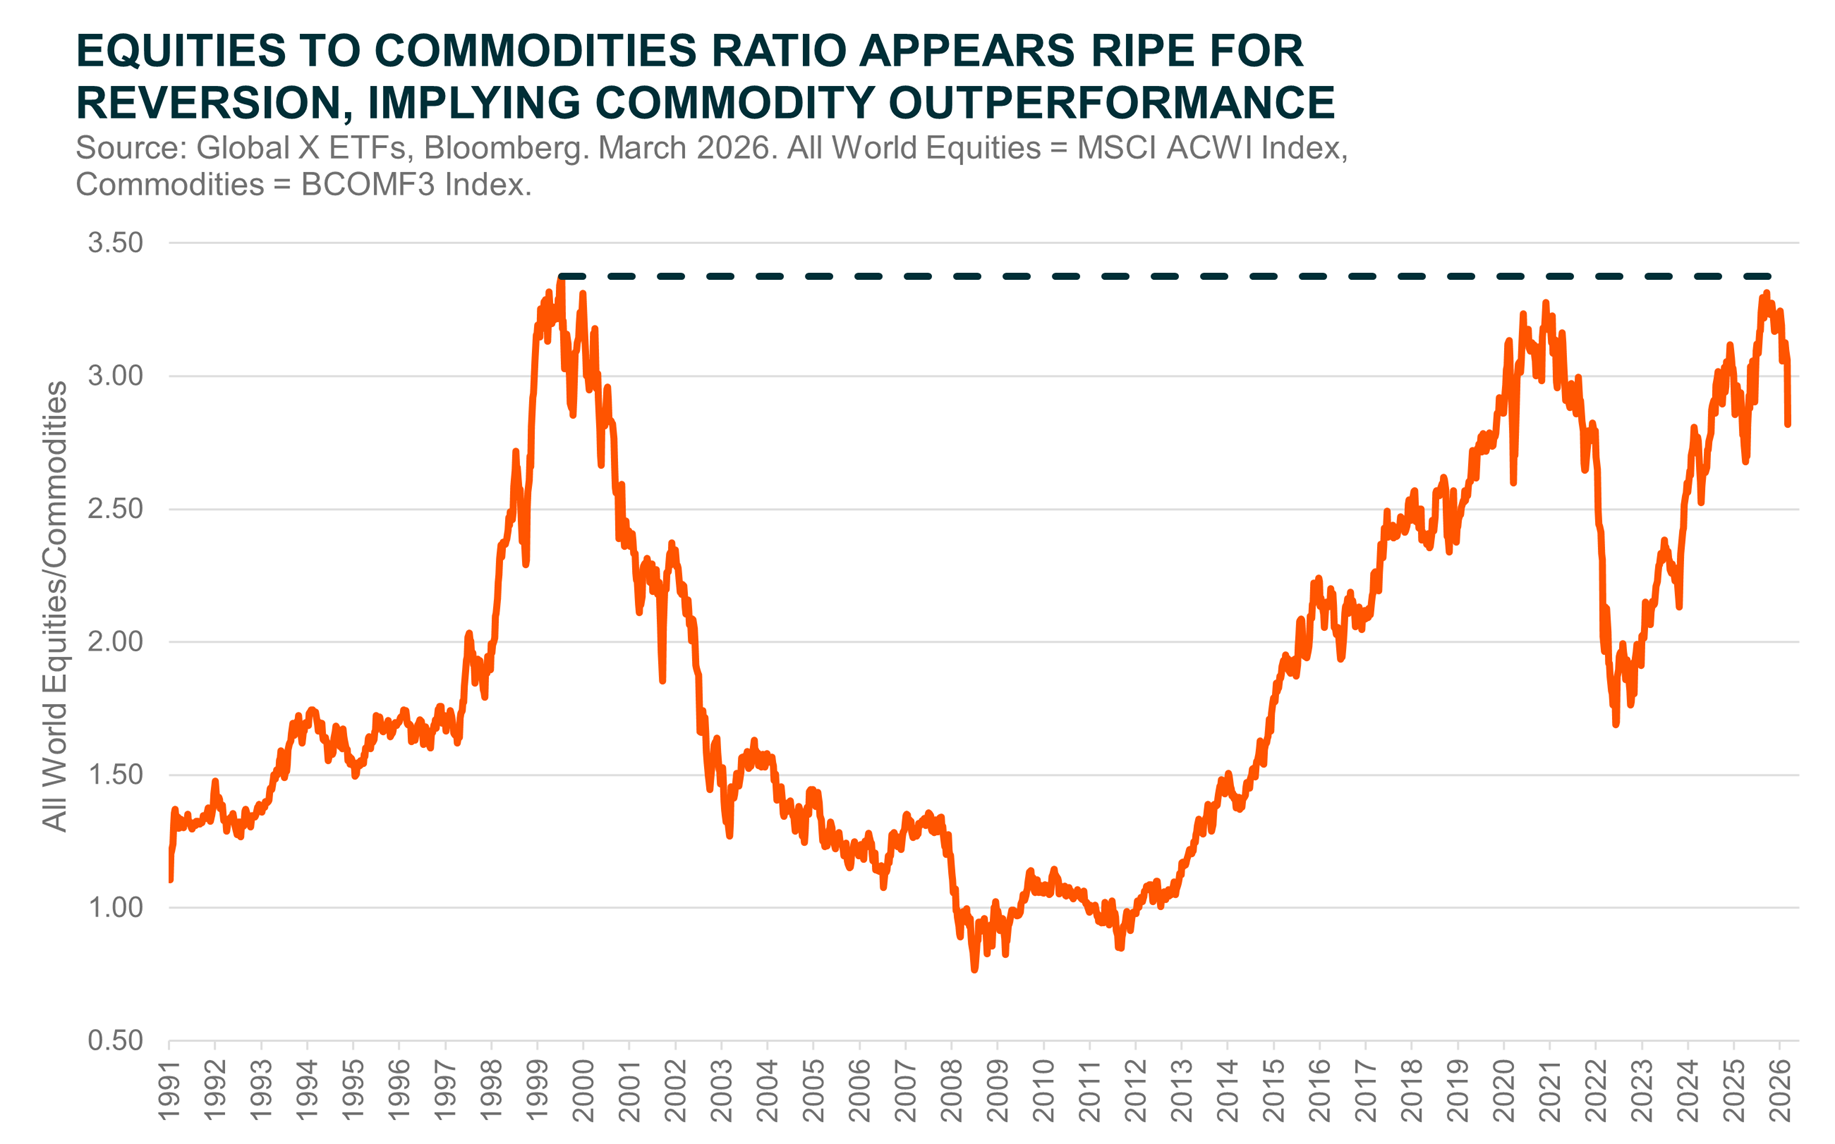
Commodity markets move in long, structural cycles that rarely align neatly with equity market cycles, which is precisely what makes them useful diversifiers when understood correctly. The 2000s commodity supercycle was driven by China's industrialisation, which pulled enormous volumes of iron ore, copper and energy into infrastructure and manufacturing build-out, delivering a decade of broad commodity outperformance that rewarded almost any exposure, from resource equities to physical bullion. That cycle ended abruptly around 2011-2014 as Chinese growth moderated and a wave of new mine supply, greenlit during the boom, came online just as demand growth slowed, producing a multi-year bear market that punished investors who had extrapolated the boom indefinitely.
The subsequent decade, roughly 2014 to 2020, was a difficult period for most commodities. Zero and negative interest rate policy globally rewarded duration assets and growth equities, and non-yielding commodities like gold and diversified baskets materially underperformed. This period may create a mistaken impression that commodities are structurally poor long-term investments. That’s a classic example of how commodity cycle length can distort simple back-tested return comparisons.
The current cycle, roughly from 2020 onward, has been shaped by a different set of forces: pandemic-era supply chain disruption, an inflation shock the likes of which developed economies had not experienced since the early 1980s, war in Europe disrupting energy and grain markets, and the beginning of large-scale central bank gold accumulation discussed earlier. Whether this constitutes a new supercycle, a shorter cyclical upswing, or simply a period of elevated volatility around a structurally lower growth trend remains contested among institutional strategists, and investors should be wary of anyone claiming high conviction on the answer.
Commodity cycles typically run longer, and turn more abruptly, than equity market cycles. This is exactly why they can diversify a portfolio when equities and bonds move together, but it also means investors entering late in a cycle can face a materially different risk-reward proposition to those who entered earlier.
WHAT COMMODITIES ARE, AND WHY THE CATEGORY IS BROADER THAN GOLD
A commodity is a raw, largely undifferentiated input into the economy: energy, metals, agriculture, and increasingly, materials tied to the energy transition such as lithium and copper. Because commodities are fungible, a barrel of West Texas Intermediate crude is functionally the same as another barrel of the same grade. Unlike a share in a specific company, their prices are set predominantly by global supply and demand rather than by company-specific factors such as management quality or balance sheet structure.
Investors typically bucket commodities into four groups, each with distinct drivers:
Precious metals (gold, silver, platinum, palladium) — driven by real interest rates, currency debasement fears, central bank reserve accumulation and safe-haven demand during geopolitical stress.
Energy (crude oil, natural gas, uranium) — driven by global economic growth, OPEC+ supply discipline, geopolitical supply disruption and, increasingly, the energy transition's demand for both fossil fuels and the metals that replace them.
Industrial and base metals (copper, aluminium, nickel, lithium, rare earths) — driven by global manufacturing activity, infrastructure investment and decarbonisation-linked demand, particularly from electric vehicles, battery storage and grid expansion.
Agriculture (wheat, corn, soybeans, livestock) — driven by weather patterns, crop yields, trade policy and population growth, with generally lower correlation to financial-market cycles than the other three categories.
For Australian investors specifically, this taxonomy is significant because the domestic economy already has heavy exposure to two of the four buckets through resource company earnings, currency movements and the terms of trade.
Understanding which commodities sub-category you are investing in, and why, is more prudent than treating commodities as a single homogenous exposure.
Gold's unique status within the commodity universe
Gold occupies a somewhat unusual position among commodities.
Unlike industrial metals or energy, its price is only loosely tied to physical consumption; jewellery, technology and industrial uses account for a meaningful but not dominant share of demand. Instead, gold behaves more like a monetary asset, a competitor to fiat currency and government bonds as a store of value, which is why its price is driven primarily by financial variables such as real interest rates, currency movements and central bank reserve policy rather than by mine supply and industrial offtake in the way copper or aluminium are.
This distinction explains why gold tends to provide better crisis-period diversification than other commodities. It is not simply a leveraged bet on global economic growth. It is in many respects a hedge against the institutions that issue and manage currency.
Australian investors can access this exposure in several structurally distinct ways.
Global X Physical Gold (ASX: GOLD) offers direct, unhedged exposure to the Australian dollar spot gold price backed by allocated bullion, while the Global X Gold Bullion (Currency Hedged) ETF (ASX: GHLD) offers the same underlying physical gold exposure with the Australian dollar/US dollar currency movement stripped out, isolating the pure gold price return.
Choosing between the two is a portfolio decision. An investor using gold specifically as a crisis hedge may prefer the unhedged GOLD, since the Australian dollar has historically tended to weaken during global risk-off periods, amplifying the defensive benefit when it is most valued, while an investor with a more currency-neutral objective may prefer GHLD.
Silver's dual identity
Silver sits awkwardly between precious and industrial metals, which is both its appeal and its complication for portfolio construction purposes.
Roughly half of global silver demand comes from industrial applications, particularly solar photovoltaic manufacturing, electronics and electric vehicles, while the remainder is investment and jewellery demand that behaves more like gold.
This dual nature means silver tends to exhibit higher volatility than gold, amplifying moves in both directions, sometimes tracking gold closely during monetary-driven rallies and at other times tracking industrial metal cycles during growth-driven periods.
Investors buying silver exposure should understand they are taking a more volatile, less purely defensive position than a gold allocation, even though the two are often marketed together as precious metals.
Why energy commodities are different
Crude oil, natural gas and increasingly uranium present a different investment proposition to metals because physical storage at scale is either impractical or, in the case of natural gas, requires specialised infrastructure most investors cannot access.
This is the fundamental reason almost all energy commodity exposure for retail and even institutional investors runs through futures contracts, equities in producing companies, or infrastructure-adjacent vehicles rather than physical ownership, with all the roll-yield and company-risk considerations that follow, discussed in detail later in this report.
THE MACRO BACKDROP: WHY COMMODITIES CAN ADD VALUE TO PORTFOLIOS
Three structural forces explain the renewed institutional interest in commodities, and each may have direct relevance to how Australian investors should think about portfolio construction in the years ahead.
Central bank gold buying has structurally changed the demand base
Central banks, led by China, India, Poland and Turkey, have been net buyers of gold at a pace not seen since the early 1970s, with purchases running at roughly 60 tonnes a month in recent periods according to World Gold Council data.
This is widely interpreted as a hedge against reliance on US dollar reserves following the freezing of Russian central bank assets in 2022, a precedent that reserve managers elsewhere have not ignored.
This buying is largely price-insensitive, meaning it provides a demand floor that did not exist during previous gold cycles, which were driven primarily by retail and jewellery demand.
Real interest rates, not headline inflation, drive precious metals
A common investor misconception is that gold simply tracks inflation.
In practice, gold is more accurately understood as an inverse function of real interest rates, the rate of return investors can earn after accounting for inflation.
When real rates are low or negative, the opportunity cost of holding a non-yielding asset like gold falls, and the metal tends to perform well.
When real rates rise sharply, as they did through 2022 and 2023, gold typically faces headwinds even amid elevated inflation.
Understanding this distinction matters more than headline inflation figures when forming a view on the metal's medium-term outlook.
The energy transition has created durable new sources of metals demand
Copper, lithium, nickel and rare earth elements sit at the intersection of two powerful themes: the electrification of transport and the build-out of renewable generation and storage infrastructure.
The International Energy Agency has repeatedly flagged that current mine supply pipelines for several of these metals fall well short of what net-zero commitments would require by 2030, creating a structural demand-supply mismatch that is distinct from, and arguably more durable than, a typical cyclical commodity upswing.
A related and increasingly important thematic angle is the physical resource intensity of artificial intelligence infrastructure itself.
The Global X Artificial Intelligence Infrastructure ETF (ASX: AINF) illustrates this connection: rather than investing in chipmakers or software platforms, it targets companies driving the build-out of electric utilities, thermal management and the production of copper and uranium, the foundational resources required to meet the accelerating energy demands of AI data centre workloads.
This is a useful illustration of how commodity demand and thematic technology investing increasingly overlap, and why an investor's exposure to copper or uranium may already be broader than a single-commodity ETF allocation suggests once thematic equity holdings are accounted for.
Geopolitical fragmentation and the return of resource nationalism
A quieter but equally important shift has been the return of resource nationalism and strategic stockpiling.
Export restrictions on rare earth processing, critical minerals licensing reviews, and government intervention to secure domestic supply chains for defence and technology applications have all become more common since 2022.
For investors, this is significant because it introduces a genuinely new risk-reward dynamic: commodities that were once priced primarily on supply and demand fundamentals now carry an additional geopolitical risk premium, which can work in either direction depending on which side of a trade restriction an investor's exposure sits on.
Australia, as a major producer of iron ore, lithium and several critical minerals, is a direct beneficiary of this dynamic in aggregate, even though individual commodity price movements remain volatile and unpredictable in the short term.
Why this matters more for Australia than most developed markets
Australia is one of the few developed economies where the domestic equity market, the domestic currency and the broader economic cycle are all meaningfully influenced by the same underlying commodity exposures.
The Australian dollar is frequently described by currency strategists as a commodity currency, tending to appreciate when commodity prices, particularly iron ore and energy, rise, and depreciate when they fall.
The ASX 200 carries a materially higher weighting to materials and energy sectors than comparable developed market indices such as the S&P 500.
Federal and state government revenue, particularly through royalties and company tax receipts from resource companies, is itself commodity-cycle dependent, which is why Australian Budget forecasts routinely flag commodity price assumptions as a key sensitivity.
This creates a specific and often underappreciated portfolio construction challenge.
An Australian investor holding domestic equities, Australian dollar cash, and a home in a resource-exposed regional economy is already running a concentrated bet on the commodity cycle, whether they intend to or not.
A thoughtful commodities allocation in this context is about consciously deciding whether to lean further into that existing exposure, diversify away from it through international assets, or use a specific commodity, gold being the clearest example, that behaves differently to the broader Australian commodity complex to provide genuine, rather than illusory, diversification.
HOW COMMODITIES BEHAVE STATISTICALLY INSIDE A PORTFOLIO
The investment case for commodities rests less on their standalone return profile, which has historically lagged equities over long horizons, and more on their diversification characteristics.
Commodities have historically exhibited low or even negative correlation to both equities and bonds during specific stress periods, particularly episodes of unexpected inflation, when both stocks and bonds tend to fall together.
This was the defining portfolio lesson of 2022, when a conventional 60/40 portfolio experienced one of its worst calendar years on record because bonds failed to provide their usual offset to falling equities.
The purpose of a commodities allocation is rarely to maximise returns. It is to own an asset that tends to do well in the environment where equities and bonds both struggle: during unexpected inflation shocks.
This diversification benefit is not constant.
Correlations between commodities and equities can rise during broad risk-off events, when investors sell everything regardless of fundamentals, so commodities should not be treated as a guaranteed hedge in every scenario.
Their value is most pronounced specifically during inflation surprise regimes, which is a narrower and more useful way to think about their role than a blanket 'diversifier' label.
An important subtlety on this topic is the distinction between expected and unexpected inflation.
Markets price in expected inflation continuously, reflected in bond yields, wage negotiations and inflation-linked security pricing, so an inflation outcome that matches consensus expectations tends not to generate significant commodity outperformance, since it was already anticipated and priced.
It is specifically unexpected, or surprise, inflation, outcomes that deviate materially from what markets had priced, that tends to produce the sharp asset repricing where commodities, and gold in particular, have historically outperformed.
This is why commodities performed so strongly through 2021 and 2022: the inflation shock was substantially higher and more persistent than consensus forecasts anticipated at the time, catching both equity and bond markets offside.
The 60/40 portfolio problem and where commodities fit
The traditional 60% equity, 40% bond portfolio construction relies on a specific historical relationship: that bonds rally when equities fall, because weak growth typically brings both falling inflation and falling interest rates, which lifts bond prices.
This relationship held remarkably consistently from the early 1980s through to 2021, an unusually long period of disinflation that shaped how an entire generation of financial advisers and investors were trained to think about diversification.
The year 2022 broke this pattern decisively.
Equities and bonds fell together, by a significant margin, because the driver of market stress was inflation itself rather than a growth slowdown, and rising rates hurt both asset classes simultaneously.
Commodities, and gold in particular held up far better on a relative basis, reminding institutional allocators why a third, differently-correlated asset class has genuine structural value even in portfolios that had gone a decade without needing it.
Historical correlation patterns
The table below summarises commonly cited, generalised historical correlation tendencies between major asset classes, drawn from long-run academic and institutional research. These are illustrative averages across full market cycles rather than precise forecasts, and correlations shift meaningfully depending on the specific period examined.
Asset pair
Typical long-run correlation
Behaviour in inflation shock periods
Australian equities vs. global equities
High positive
Tends to remain high; limited diversification benefit
Australian equities vs. government bonds
Low to moderate positive (historically negative)
Can turn positive (both fall) during inflation shocks
Gold vs. equities
Low or negative
Often strengthens (more negative) during equity stress
Gold vs. government bonds
Low or negative
Gold has often outperformed bonds specifically during unexpected inflation
Broad commodities vs. equities
Low to moderate
Correlation can rise during broad risk-off liquidations
The strategic role of each commodity type in a portfolio
Commodity type
Primary portfolio role
Typical behaviour in a downturn
Gold
Inflation and currency hedge; crisis insurance
Tends to hold or gain value during equity market stress and currency devaluation
Energy (oil, gas)
Inflation hedge; cyclical growth exposure
Highly volatile; can fall sharply in demand-driven recessions, spike in supply shocks
Industrial metals (copper, nickel)
Growth and infrastructure exposure
Correlates more closely with equities and global manufacturing activity
Battery/EV metals (lithium)
Structural decarbonisation theme
High volatility; sensitive to supply additions and EV demand cycles
Agriculture
Diversification; inflation pass-through
Lower correlation to broad market cycles; driven by weather and trade policy
HOW AUSTRALIAN INVESTORS CAN ACCESS COMMODITIES: FIVE ROUTES
Direct commodity ownership is impractical for almost all investors. Nobody wants a warehouse of soybeans.
So, the question is which of five routes described below best matches your objective, cost sensitivity and risk tolerance?
1. Physically-backed commodity ETFs
Physically-backed ETFs hold the actual underlying commodity, typically gold, silver, platinum or palladium bullion, in secure vaulting, with each unit representing a direct claim on a portion of that physical holding.
This structure minimises tracking error against the spot price and avoids the complications of futures roll costs.
For example, Global X Physical Gold (ASX: GOLD) tracks the spot gold price in Australian dollars with a management fee of 0.40% p.a., while Perth Mint Gold (ASX: PMGOLD) carries a lower fee of 0.15% p.a. and benefits from a Western Australian government guarantee over the underlying metal, making it a common choice for cost-sensitive SMSF trustees.
Beyond single-metal exposure, Global X Physical Precious Metals Basket (ASX: ETPMPM) offers a low-cost and secure way to access physical gold, silver, platinum and palladium in a single instrument, useful for investors who want diversified precious metals exposure without deciding between the individual metals themselves.
2. Futures-based and synthetic commodity ETFs
Commodities without a practical physical storage option, chiefly energy and agriculture, are typically accessed through ETFs that hold futures contracts rather than the physical commodity.
This introduces a feature investors must understand: roll yield.
Futures contracts expire, so the fund must periodically sell expiring contracts and buy new ones further out on the curve.
When the futures curve is in contango, meaning further-dated contracts are more expensive than near-dated ones, this roll process creates a persistent drag on returns, independent of what happens to the spot price.
When the curve is in backwardation, the opposite can occur, providing a tailwind.
This is the single most misunderstood feature of energy and broad-commodity ETFs, and it explains why a long-term buy-and-hold investor in an oil futures ETF can underperform the spot oil price materially over multi-year periods even when their directional view was correct.
3. Diversified or basket commodity ETFs
Rather than taking a single-commodity view, diversified commodity ETFs track a basket index spanning energy, metals and agriculture, rebalanced periodically according to defined weighting rules.
This reduces single-commodity concentration risk and can smooth the roll-yield issue somewhat, since different components of the curve behave differently at any given time, though it does not eliminate it.
These products are best understood as a macro or inflation-hedging allocation rather than a tactical single-commodity view.
4. Resource and mining equities
Buying shares in companies that extract or process commodities, from ASX-listed diversified miners through to smaller pure-play producers, provides indirect, leveraged exposure to commodity prices.
Equity exposure carries meaningfully different risk to the commodity itself: company-specific factors such as balance sheet leverage, management execution, sovereign risk in the jurisdictions where assets are located, and equity market sentiment all layer on top of the underlying commodity price.
Miners can and do underperform the commodities they extract during periods of cost inflation, project delays or capital raisings, just as they can outperform through operating leverage during upcycles.
This is a different risk profile to owning the commodity directly, and conflating the two is one of the more common investor errors covered later in this report.
5. Actively managed commodity and resources funds
For investors who want professional judgement on which commodities, and which points in the cycle, to hold, actively managed funds can combine physical, futures and equity exposure with tactical positioning.
For example, Tribeca Global Natural Resources (ASX: TGF) runs an active long/short investment strategy specifically designed to profit from the inherent volatility in the natural resources sector, rather than simply holding a static, passive basket of resource equities or futures. This comes at a higher fee than passive ETF exposure and introduces manager selection risk, but may suit investors seeking active risk management around a genuinely cyclical, volatile asset class rather than static beta exposure.
A CLOSER LOOK AT URANIUM AND LITHIUM: TWO COMMODITIES GENERATING DISPROPORTIONATE INVESTOR INTEREST
Uranium and lithium deserve separate treatment because both have attracted significant retail investor attention over recent years, driven by structural narratives, nuclear energy's re-emergence as a decarbonisation tool and lithium's central role in battery manufacturing, that are broadly sound but which have also produced some of the sharpest boom-bust price cycles of any commodity in recent memory.
Uranium: a supply story, but a thin and unusual market
Unlike most commodities, uranium is not traded on a large, liquid, transparent open exchange in the way gold or crude oil are.
The majority of uranium is transacted through long-term bilateral contracts between utilities and producers, with a comparatively small spot market that can be disproportionately moved by relatively modest trading volumes, including from financial buyers such as listed uranium trusts that physically accumulate the metal.
This structural thinness means uranium prices can be considerably more volatile, and more susceptible to speculative flows, than the underlying supply-demand fundamentals alone would suggest.
The renewed policy support for nuclear power across multiple developed economies, as a firm, low-carbon baseload energy source to complement variable renewables, is a structural tailwind, but investors should size any uranium-specific exposure conservatively given the market's structural characteristics and historical volatility, which has included both multi-year rallies and severe drawdowns within the same decade.
Lithium: from boom to bust and the lesson it offers
Lithium prices rose dramatically through 2021 and 2022 on the back of surging electric vehicle demand and constrained near-term supply, before falling by well over 80% from peak through 2023 and into 2024 as a wave of new supply, much of it approved and financed during the boom, came online just as EV sales growth in several major markets moderated from its earlier torrid pace.
This episode illustrated the classic boom-bust supply response cycle typical of commodities markets. High prices incentivise new production, that new production arrives with a multi-year lag, and by the time it does, the price signal that justified the investment has often already reversed.
Investors considering thematic exposure to energy transition metals should treat this as a cautionary case study in position sizing and cycle awareness.
The underlying long-term demand thesis remains intact even as the price cycle has proven considerably more volatile than many early thematic investors anticipated.
Comparing the access routes
Access route
Typical cost (p.a.)
Tracking accuracy
Key structural risk
Physically-backed ETF
0.15% – 0.50%
High
Storage/custody counterparty risk (generally low for major providers)
Futures-based ETF
0.35% – 0.70%
Moderate to low
Roll yield can materially diverge returns from spot price
Diversified basket ETF
0.40% – 0.70%
Moderate
Blended roll yield; less precise single-commodity exposure
Resource/mining equities
Brokerage only, or 0.4%-1%+ for funds
Low (equity-driven)
Company, balance sheet and equity-market risk layered on commodity risk
Active commodities fund
0.75% – 1.5%+
Manager-dependent
Manager selection risk; higher fee drag
TAX AND STRUCTURAL CONSIDERATIONS AUSTRALIAN INVESTORS OFTEN OVERLOOK
Two structural issues catch out investors who assume commodity ETFs behave exactly like equity ETFs for tax purposes.
Capital gains treatment generally applies, but structure matters
For most ASX-listed, Australian-domiciled physically-backed and futures-based commodity ETFs held by individual investors, gains on disposal are typically treated as capital gains, meaning the standard 50% CGT discount can apply up until 30 June 2027 if the units are held for more than twelve months, the same as for equities.
However, this is not universal.
Some overseas-domiciled or partnership-structured commodity vehicles, more common in US-listed products than ASX-listed ones, can attract different tax treatment. Investors should always check a product's tax component schedule or PDS rather than assume identical treatment across the category, and should seek advice specific to their circumstances rather than rely on general commentary such as this.
Distributions and income are typically minimal
Most physically-backed commodity ETFs generate no income distributions, because the underlying asset, bullion or futures contracts, produces no yield.
Investors seeking income should not expect a commodities allocation to contribute to portfolio cash flow; its role is capital preservation and diversification, not income generation.
This is a meaningful distinction for retirees structuring pension-phase portfolios around income needs, where a commodities sleeve should generally be funded from the growth allocation rather than viewed as an income-producing holding.
SMSF considerations
Self-managed super funds can hold ASX-listed commodity ETFs like any other listed security, with standard HIN-based custody and reporting, which is operationally simpler than direct physical bullion ownership, which carries its own storage, insurance and Australian Taxation Office sole purpose test considerations.
Trustees should also be mindful of concentration limits under their fund's investment strategy; the ATO has increasingly scrutinised SMSFs with large single-asset-class concentrations, and a commodities allocation, however strategically sound, should sit within a documented, diversified investment strategy rather than as an outsized speculative position.
THE RISKS AND TRADE-OFFS INVESTORS SHOULD WEIGH HONESTLY
A credible commodities allocation requires acknowledging its genuine limitations rather than presenting the asset class as a costless diversifier.
No yield: commodities generate no dividends, coupons or rental income, meaning total return depends entirely on price appreciation, which makes the opportunity cost of holding them rise as interest rates increase.
Higher volatility than most asset classes: energy and industrial metal prices can move 20-40% in a matter of months on supply shocks, demand revisions or geopolitical developments, materially more than diversified equity indices.
Roll yield drag in futures-based products: as discussed above, this can cause meaningful long-term underperformance relative to the spot price, independent of the correctness of an investor's directional view.
Currency exposure: unhedged exposure to globally-priced commodities denominated in US dollars means Australian dollar movements materially affect realised returns, sometimes overwhelming the underlying commodity price move itself.
Cyclicality and drawdown risk: commodities can experience prolonged bear markets, as occurred through much of the 2010s, during which an allocation can act as a persistent drag on portfolio performance even while providing genuine diversification value.
The conclusion is that commodities are a diversification tool, not a return driver, for most portfolio construction purposes.
Hence, investors expecting commodities to consistently outperform equities over long horizons are likely to be disappointed.
Investors using a modest, disciplined allocation to reduce portfolio-level inflation and tail risk are using the asset class as intended.
PORTFOLIO CONSTRUCTION: HOW MUCH, AND WHERE
There is no universal answer to sizing a commodities allocation, since it depends on an investor's existing exposures, risk tolerance and objectives.
That said, several frameworks used by institutional asset consultants provide useful reference points:
Strategic allocation range: most institutional model portfolios that include a dedicated commodities sleeve allocate somewhere between 2% and 10% of total portfolio value, with the lower end suiting investors already carrying meaningful indirect commodity exposure through resource-heavy equity holdings, and the higher end suiting those seeking a more deliberate inflation hedge.
Existing exposure audit: Australian investors should assess how much indirect commodity exposure they already hold through ASX 200 index funds, given the heavy weighting to miners and energy producers, before layering on a dedicated allocation. Owning both broad Australian equities and resource-heavy commodity ETFs at large scale can create unintended concentration rather than diversification.
Sub-asset-class allocation: within a commodities sleeve, gold is typically the anchor holding given its crisis-hedge properties, with smaller satellite allocations to diversified baskets, energy or transition metals depending on the investor's specific macro view or thematic conviction.
Rebalancing discipline: because commodities are volatile and cyclical, a disciplined rebalancing approach, trimming after strong rallies and adding after material drawdowns, tends to add more value than an initial one-off allocation decision, since it enforces buying low and selling high rather than chasing recent performance.
COMPARISON FRAMEWORKS: ACTIVE VS. PASSIVE, AND LISTED VS. UNLISTED
Active versus passive commodity exposure
The active-versus-passive debate that has played out extensively in equities applies somewhat differently to commodities.
In equity markets, active managers must overcome the challenge of identifying mispriced individual securities within a market that is, in aggregate, reasonably efficiently priced by a large number of well-resourced participants.
In commodities, the case for active management rests less on security selection, since a passive gold ETF and an active gold-focused strategy hold essentially the same underlying asset, and more on tactical allocation: deciding when to increase or reduce exposure to different commodities based on macro views, and managing the structural roll-yield issue in futures-based exposures more actively than a static index methodology permits.
This means the active-passive decision in commodities is less about manager skill in picking better assets and more about whether an investor wants to delegate tactical timing and roll-yield management decisions to a professional manager, at a higher fee, or retain that decision-making themselves through a lower-cost passive vehicle.
Investors with strong, informed macro views and the discipline to act on them may find passive exposure entirely sufficient. Investors who lack the time, inclination or conviction to make those tactical calls, but still want commodity exposure, may find an actively managed multi-commodity fund preferable to either attempting their own tactical allocation or defaulting to a single, static passive holding regardless of the market environment.
Listed versus unlisted structures
ASX-listed commodity ETFs offer daily liquidity, transparent intraday pricing and straightforward entry and exit through a standard brokerage account, which suits the majority of self-directed investors.
Unlisted managed funds with commodity exposure, more commonly found in diversified alternative or real-asset fund structures rather than as standalone commodity vehicles, typically offer less frequent liquidity, often monthly or quarterly, in exchange for potentially broader mandate flexibility and, in some cases, exposure to less liquid sub-segments of the commodity complex that would be impractical to hold in a daily-liquid, listed structure.
For most Australian investors, the daily liquidity, transparency and lower minimum investment thresholds of listed ETFs make them the more practical starting point, with unlisted structures more relevant for larger, more sophisticated allocators seeking specific mandate features not available in listed form.
Comparing listed and unlisted commodity exposure
Feature
ASX-listed commodity ETF
Unlisted commodity/real-asset fund
Liquidity
Daily, intraday
Typically, monthly or quarterly
Pricing transparency
Continuous, market-based
Periodic, manager-determined valuation
Minimum investment
Typically, the cost of one unit
Often $10,000-$50,000 or higher
Fee structure
Simple management fee
Management fee, sometimes plus performance fee
Best suited to
Most retail and SMSF investors
Larger allocators seeking specific mandate features
IMPLEMENTATION IN PRACTICE: THREE ILLUSTRATIVE INVESTOR SCENARIOS
The inflation-conscious retiree
A retiree drawing an account-based pension with a defensive-tilted portfolio may hold a small, physically-backed gold allocation, commonly in the 3-5% range, funded from the growth portion of their portfolio rather than their income sleeve, given gold's lack of yield.
The rationale is capital preservation against currency debasement and equity market stress, not return generation.
A lower-fee physically-backed gold ETF such as Perth Mint Gold (ASX: PMGOLD) is typically more appropriate here than a leveraged or futures-based product, given the priority on capital stability over tactical positioning, and its government guarantee over the underlying metal may offer additional peace of mind for a retiree prioritising security over cost alone.
The SMSF trustee seeking diversification beyond Australian equities
An SMSF heavily weighted to Australian bank and mining shares, a common structural feature of self-managed portfolios built up over decades, may find that adding a diversified commodity basket does relatively little for true diversification, since the fund is already commodity-exposed through its mining holdings.
In this case, a more genuinely diversifying move might be reducing direct resource equity concentration rather than adding a separate commodities ETF, or if pursuing commodities specifically, favouring gold, for instance through Global X Physical Gold (ASX: GOLD) or the currency-hedged GHLD, over broad-basket or industrial metal exposure to avoid doubling up on cyclical resource-sector risk that the fund's existing mining shares already carry.
The growth-oriented investor positioning for the energy transition
An investor with a long time horizon and higher risk tolerance seeking exposure to the electrification and decarbonisation theme might consider a smaller, higher-conviction allocation to industrial and battery metals, or a thematic vehicle such as the Global X Artificial Intelligence Infrastructure ETF (ASX: AINF) for exposure to the copper and uranium demand driven by AI infrastructure build-out, understanding this carries materially higher volatility and thematic concentration risk than a gold allocation.
Investors seeking active, cycle-aware management of resource-sector volatility rather than static index exposure might instead consider an actively managed vehicle such as Tribeca Global Natural Resources (ASX: TGF).
Either approach is better understood as a satellite growth position than a core defensive holding, and sizing should reflect that higher risk profile accordingly.
BEHAVIOURAL TRAPS: WHY COMMODITIES TEST INVESTOR DISCIPLINE MORE THAN MOST ASSET CLASSES
Commodities present a particular behavioural challenge because their volatility and cyclicality interact poorly with common cognitive biases.
Recency bias, the tendency to overweight recent experience when forming expectations about the future, is especially damaging in commodity markets given how dramatically returns can differ across consecutive multi-year periods.
An investor who formed their view of commodities during the 2014-2020 bear market may have concluded the asset class was structurally unrewarding, just before one of the strongest multi-year runs in over a decade began.
Conversely, an investor who became enthusiastic about commodities, or a specific sub-theme like lithium, near a cyclical peak, driven by exactly the media coverage and price momentum that peaks tend to generate, was buying into precisely the conditions that historically preceded sharp reversals.
This is why a disciplined, pre-determined allocation approach, sized appropriately as a strategic diversifier rather than a speculative tactical position, and maintained through a rules-based rebalancing process rather than adjusted based on recent price action or news flow, tends to produce better long-term investor outcomes than attempting to time entry and exit around commodity cycles.
The asset class rewards patience and discipline considerably more than it rewards conviction or forecasting skill, which is a difficult but important lesson for investors drawn to commodities specifically because of a strong macro or thematic view.
COMMON MISTAKES AUSTRALIAN INVESTORS MAKE WITH COMMODITIES
Conflating resource equities with commodity exposure
Mining and energy shares carry company and equity-market risk layered on top of commodity price risk: balance sheet leverage, project execution, management decisions, sovereign risk in operating jurisdictions and broader equity market sentiment all affect returns independently of the underlying commodity price.
A well-run miner with a strong balance sheet can outperform the commodity it produces through operating leverage during an upcycle, while a poorly capitalised producer can underperform sharply even amid rising prices if it needs to raise dilutive equity capital or faces cost blowouts.
This is the distinction an actively managed vehicle such as Tribeca Global Natural Resources (ASX: TGF) is designed to navigate through active positioning, rather than passively absorbing whatever equity-specific risk a static basket of resource shares happens to carry.
Investors seeking pure, direct commodity price exposure without company-specific risk should generally look to physically-backed products such as Global X Physical Gold (ASX: GOLD) rather than equities, reserving resource equities and actively managed resources funds for investors specifically seeking the operating leverage, active risk management and growth characteristics that come with those structures.
Ignoring roll yield in futures-based products
Investors frequently assume that holding a futures-based commodity ETF for several years will deliver a return that closely tracks the change in the underlying spot price over that period.
As discussed earlier, this is often not the case, particularly for energy commodities, where persistent contango in the futures curve has historically created a meaningful drag on long-term buy-and-hold returns, independent of whether an investor's directional view on the commodity proved correct.
This is arguably the single most consequential technical detail that separates informed commodity investors from those who are caught by surprise when a multi-year holding underperforms their expectations despite a rising spot price.
Overweighting commodities after a strong rally
Performance-chasing, allocating capital after strong recent returns rather than before them, is a well-documented behavioural pattern across all asset classes, but it is particularly costly in commodities given how sharply cycles can turn.
Media coverage, and consequently retail investor attention and inflows, tends to peak alongside or shortly after price peaks, meaning investors who chase commodity themes after they have already run hard are statistically more likely to be buying near a cyclical top than a cyclical bottom.
Expecting a commodities allocation to generate income
Most commodity exposures, whether physically-backed bullion ETFs or futures-based energy products, generate no distributions at all, since the underlying assets produce no yield.
Investors building an income-focused retirement portfolio should not expect a commodities sleeve to contribute to portfolio cash flow, and should fund any such allocation from the growth or capital-preservation portion of their portfolio rather than treating it as an income-generating holding.
Underestimating currency risk in unhedged exposures
Most globally-priced commodities are denominated in US dollars, meaning an unhedged Australian investor's realised return depends on both the change in the underlying US dollar commodity price and the movement in the AUD/USD exchange rate.
During periods when the Australian dollar strengthens against the US dollar, this can meaningfully reduce the Australian dollar return even where the underlying commodity price has risen, and vice versa during Australian dollar weakness.
Some ETF providers offer currency-hedged share classes of the same underlying exposure, which removes this variable at the cost of a slightly higher management fee; investors should understand which version of a product they are buying, since the return outcomes over any given period can diverge meaningfully between hedged and unhedged versions of what is nominally the same underlying exposure.
Treating commodities as a single, homogenous asset class
Perhaps the most fundamental mistake is allocating to a broad-basket commodity product, or making a single commodities decision, without understanding that gold, energy, industrial metals and agriculture behave very differently, are driven by different fundamental factors, and serve genuinely different portfolio purposes.
A thoughtful commodities allocation begins with a clear view of which specific role the exposure is meant to play, crisis hedge, inflation protection, cyclical growth exposure or thematic positioning, and selects the specific sub-category and vehicle that matches that objective, rather than defaulting to the broadest, most diversified product on the assumption that diversification within commodities is inherently virtuous regardless of purpose.
OUTLOOK: WHAT COULD SHAPE COMMODITY MARKETS OVER THE COMING CYCLE
Several structural themes are likely to influence commodity markets over the medium term, though as with any forward-looking market commentary, these should be treated as considerations rather than predictions.
Continued central bank gold accumulation, particularly from emerging-market reserve managers diversifying away from US dollar concentration, providing a structurally different demand base to prior cycles.
Energy transition metals demand from electric vehicle adoption, grid-scale battery storage and renewable infrastructure build-out, set against mine supply pipelines that multiple energy agencies have flagged as insufficient to meet stated decarbonisation targets.
Geopolitical fragmentation and supply chain reshoring, which tend to increase the strategic premium placed on physical commodity security, particularly for critical minerals where a small number of countries dominate global processing capacity.
The path of real interest rates, which remains the single most important variable for precious metals specifically, more so than headline inflation prints.
Investors should resist the temptation to position portfolios around any single one of these themes with high conviction. The value of a commodities allocation lies substantially in its role as a diversifier across multiple possible macro outcomes.
Structural considerations: counterparty risk, custody and product due diligence
Beyond price and tax treatment, investors should apply basic structural due diligence to any commodity ETF before investing, in the same way they would for any managed investment scheme.
For physically-backed products, this includes understanding who the custodian is, where the metal is vaulted, whether it is allocated (specific bars assigned to the fund) or unallocated (a pooled claim on the custodian's holdings), and what independent audit or verification process exists.
Established providers with large, long-running physically-backed gold and silver ETFs on the ASX generally publish this information clearly in their product disclosure statements, and the larger, more liquid products in this category tend to have the most robust and transparent custody arrangements, simply as a function of scale and the commercial incentives that come with managing a large pool of assets under strict regulatory oversight.
For futures-based products, investors should understand the fund’s counterparty exposure to the financial institutions on the other side of its derivative contracts, and whether the fund uses exchange-traded, centrally cleared futures, which carry lower counterparty risk due to clearinghouse guarantees, or over-the-counter derivatives, which can carry higher and less transparent counterparty risk.
Most ASX-listed commodity ETFs use exchange-traded futures for this reason, but it remains worth confirming in the product disclosure statement rather than assuming.
FREQUENTLY ASKED QUESTIONS
Gold can play a legitimate diversification role within an SMSF, typically through an ASX-listed physically-backed gold ETF rather than direct bullion, given the operational simplicity of standard HIN-based custody versus physical storage and insurance.
Most institutional frameworks suggest a modest allocation, commonly in the low single digits to around 5-10% of the portfolio, rather than a large speculative position, and trustees should ensure any allocation is documented within the fund's investment strategy rather than added as an ad hoc position.
A physically-backed ETF holds the actual commodity, typically bullion held in secure vaulting, so each unit represents a direct claim on the physical asset.
A synthetic or futures-based ETF instead holds futures contracts or derivatives that track the commodity's price, which introduces roll yield as a structural factor that can cause returns to diverge from the spot price over time, particularly for commodities like oil and gas that cannot practically be physically stored by a fund.
Most physically-backed commodity ETFs pay no or minimal distributions, since the underlying asset generates no yield.
This differs meaningfully from equity or fixed income ETFs, and investors building an income-focused portfolio should not expect a commodities allocation to contribute to cash flow; its role is capital preservation and diversification rather than income generation.
There is no universal figure, but many institutional model portfolios that include a dedicated allocation sit in the 2-10% range, with sizing dependent on an investor's existing indirect commodity exposure through resource-heavy equities, their risk tolerance and their specific objective, whether that is inflation hedging, crisis insurance or thematic growth exposure.
Investors should also consider how much commodity-cycle risk they already carry through Australian equity holdings before adding a separate allocation.
Most ASX-listed, Australian-domiciled commodity ETFs held by individuals are subject to standard capital gains tax treatment.
However, tax treatment can vary by structure and domicile, particularly for some offshore-domiciled products, so investors should review the product's tax component schedule and seek advice specific to their circumstances rather than assume uniform treatment.
This is most commonly caused by roll yield in futures-based products.
When the futures curve is in contango, meaning longer-dated contracts trade at a premium to near-dated ones, the fund incurs a cost each time it rolls expiring contracts forward, creating a persistent drag independent of the spot price direction.
Physically-backed ETFs largely avoid this issue since they do not rely on futures contracts, though they still carry management fees and can experience minor tracking differences.
This depends on your view of the Australian dollar and your objective for the allocation.
An unhedged product gives you exposure to both the commodity price move and the currency movement, which can amplify or offset the underlying return, while a currency-hedged version isolates the commodity price move alone, at a slightly higher fee.
Investors using commodities specifically as a crisis hedge may prefer unhedged exposure, since the Australian dollar has historically tended to weaken during global risk-off periods, which can amplify the defensive benefit of an unhedged, US-dollar-priced holding like gold precisely when portfolio protection is most valued.
Both are commonly discussed as inflation-hedging asset classes, but they work through different mechanisms.
Commodities respond directly to the price of the underlying raw material, providing relatively immediate, high-beta exposure to inflation surprises.
Infrastructure assets, such as toll roads, utilities and regulated energy networks, often have contractual or regulatory mechanisms that link revenue to inflation indices, providing a more moderated, lower-volatility form of inflation protection with the trade-off of an illiquidity premium in many unlisted structures.
Investors seeking inflation protection may reasonably use both, with commodities providing more immediate, volatile protection and infrastructure providing steadier, longer-duration protection.
KEY INVESTOR TAKEAWAYS
Commodities are primarily a diversification and inflation-hedging tool, not a reliable long-term return driver; size allocations accordingly.
Physically-backed ETFs suit investors wanting simple, low-tracking-error exposure to precious metals; futures-based products carry roll yield risk that can meaningfully affect long-term returns.
Resource equities are not a substitute for direct commodity exposure; they carry additional company and equity-market risk.
Gold's behaviour is more closely tied to real interest rates than headline inflation, an important distinction when forming a view on the outlook.
Australian investors should audit their existing indirect commodity exposure through resource-heavy equity holdings before adding a dedicated allocation, to avoid unintended concentration.
Most commodity exposures generate no income, so a commodities sleeve should generally be funded from the growth allocation rather than viewed as an income strategy.
This report is general information only. It does not take into account your personal objectives, financial situation or needs, and is not a recommendation to buy, sell or hold any particular product. Commodity prices are volatile and past performance is not indicative of future results. Investors should read the relevant product disclosure statement and consider seeking advice from a licensed financial adviser before making investment decisions.
Simon Turner is an ex-fund manager with 20 years investing experience gained at Bluecrest, Kempen and Singer & Friedlander who now writes educational content about investing and sustainability. He's also the published author of The Connection Game and Secrets of a River Swimmer.
GMTL provides exposure to global companies which produce critical metals for clean energy infrastructure and technologies, including lithium, copper, nickel and cobalt.
The Ainslie Bitcoin & Bullion Fund is designed to mitigate substantial drawdowns by strategically capitalising on Bitcoin during growth phases and utilising the stability of gold and silver during periods of Bitcoin drawdowns.
MVR gives investors exposure to a diversified portfolio of ASX-listed resources companies. Australian Resources ETF aims to provide investment returns, before fees and other costs, which track the performance of the Index.
Global X Physical Precious Metal Basket (ETPMPM) offers a low-cost and secure way to access physical gold, silver, platinum, and palladium via the stock exchange.
The Fund is an absolute return fund which is focused on emerging resources companies, and targets double digit returns over a 3-5 year investment cycle. (For Wholesale Investors Only)
OOO aims to track the performance of an index (before fees and expenses) that provides exposure to crude oil futures, hedged for currency movements in the AUD/USD exchange rate.
GDX gives investors exposure to a diversified portfolio of companies involved in the gold mining industry. GDX aims to provide investment returns, before fees and other costs, which track the performance of the Index.
QRE aims to track the performance an index (before fees and expenses) comprising the largest ASX-listed companies in the resources sector, including BHP, Rio Tinto, Woodside Petroleum and more.
URNM aims to track the performance of an index (before fees and expenses) that provides exposure to a portfolio of leading companies in the global uranium industry.