This page delves into property funds and trusts open to Australian investors: pooled vehicles that hold commercial, residential or development property, compared by structure, liquidity terms, minimum investment and investor type. It is not a guide to buying an investment property.
Looking for where to buy an investment property in Australia?
This page won’t help you buy a house, unit or commercial building in your own name. That’s direct property, and it starts with a real estate agent, a buyer’s agent and a lender.
This page is for real estate investing through a fund.
As Moneysmart puts it, you buy units in an investment run by a professional manager, who pools your money with other investors’ and invests it in property. The property investment company (the fund manager) owns the buildings, collects the rent and pays you a share as distributions.
Then check the numbers in the listing and offer document.
Total returns (income plus capital growth) over 1, 3 and 5 years, to see how a fund has performed across market cycles. Always note the date the figures were reported.
Distribution rate and frequency, to judge how consistent the income has been relative to similar funds.
Gearing: how much debt the fund carries (its loan-to-value ratio, or LVR). For context, A-REITs averaged 28.6% gearing in FY25.
Asset quality and diversification: sectors, tenants, locations and weighted average lease expiry (WALE).
Fees and costs: management fee, any performance fee and the total cost ratio. On our listings these range from 0.23% for an index ETF to 1.90% for an unlisted direct property fund.
The manager: track record, transparency and how the fund fits your wider portfolio.
Example: Four property securities funds, side by side
This is how the listing figures look when you compare funds on the same measures. It is an illustration, not a ranking, and funds are shown alphabetically. Returns are shown as each issuer has published them at 30 September 2026.
Returns and costs as shown on each InvestmentMarkets listing at 28 September 2026.
What we do and don’t do
We don’t rank funds. Search results ask for the ‘best’ or ‘top’ property funds.
Figures come from the issuer, and they’re dated. Where the issuer has published them, each listing shows fees, minimum investment, liquidity, structure, investor type, the offer document and a last-updated date. Check that date before relying on a number.
This is general information, not advice. It doesn’t consider your objectives, financial situation or needs. Read the offer document and consider speaking with a licensed financial adviser before investing.
This is an educational guide to help investors better understand the property fund landscape in Australia. It is not personal financial advice, nor does it consider individual objectives or circumstances. [IMA, operator of www.investmentmarkets.com.au, holds AFSL No. 527875.]
Property investment funds, commonly called property funds, pool investor capital to buy, manage and earn income from property. They give Australian investors exposure to commercial and residential real estate without the capital, complexity or day-to-day management of owning a building.
The range is wider than most people expect: offices, shopping centres, industrial and logistics estates, healthcare properties, convenience retail and specialist assets such as social infrastructure. Income usually comes from tenants’ rent, with the potential for capital growth as properties are improved, revalued or sold.
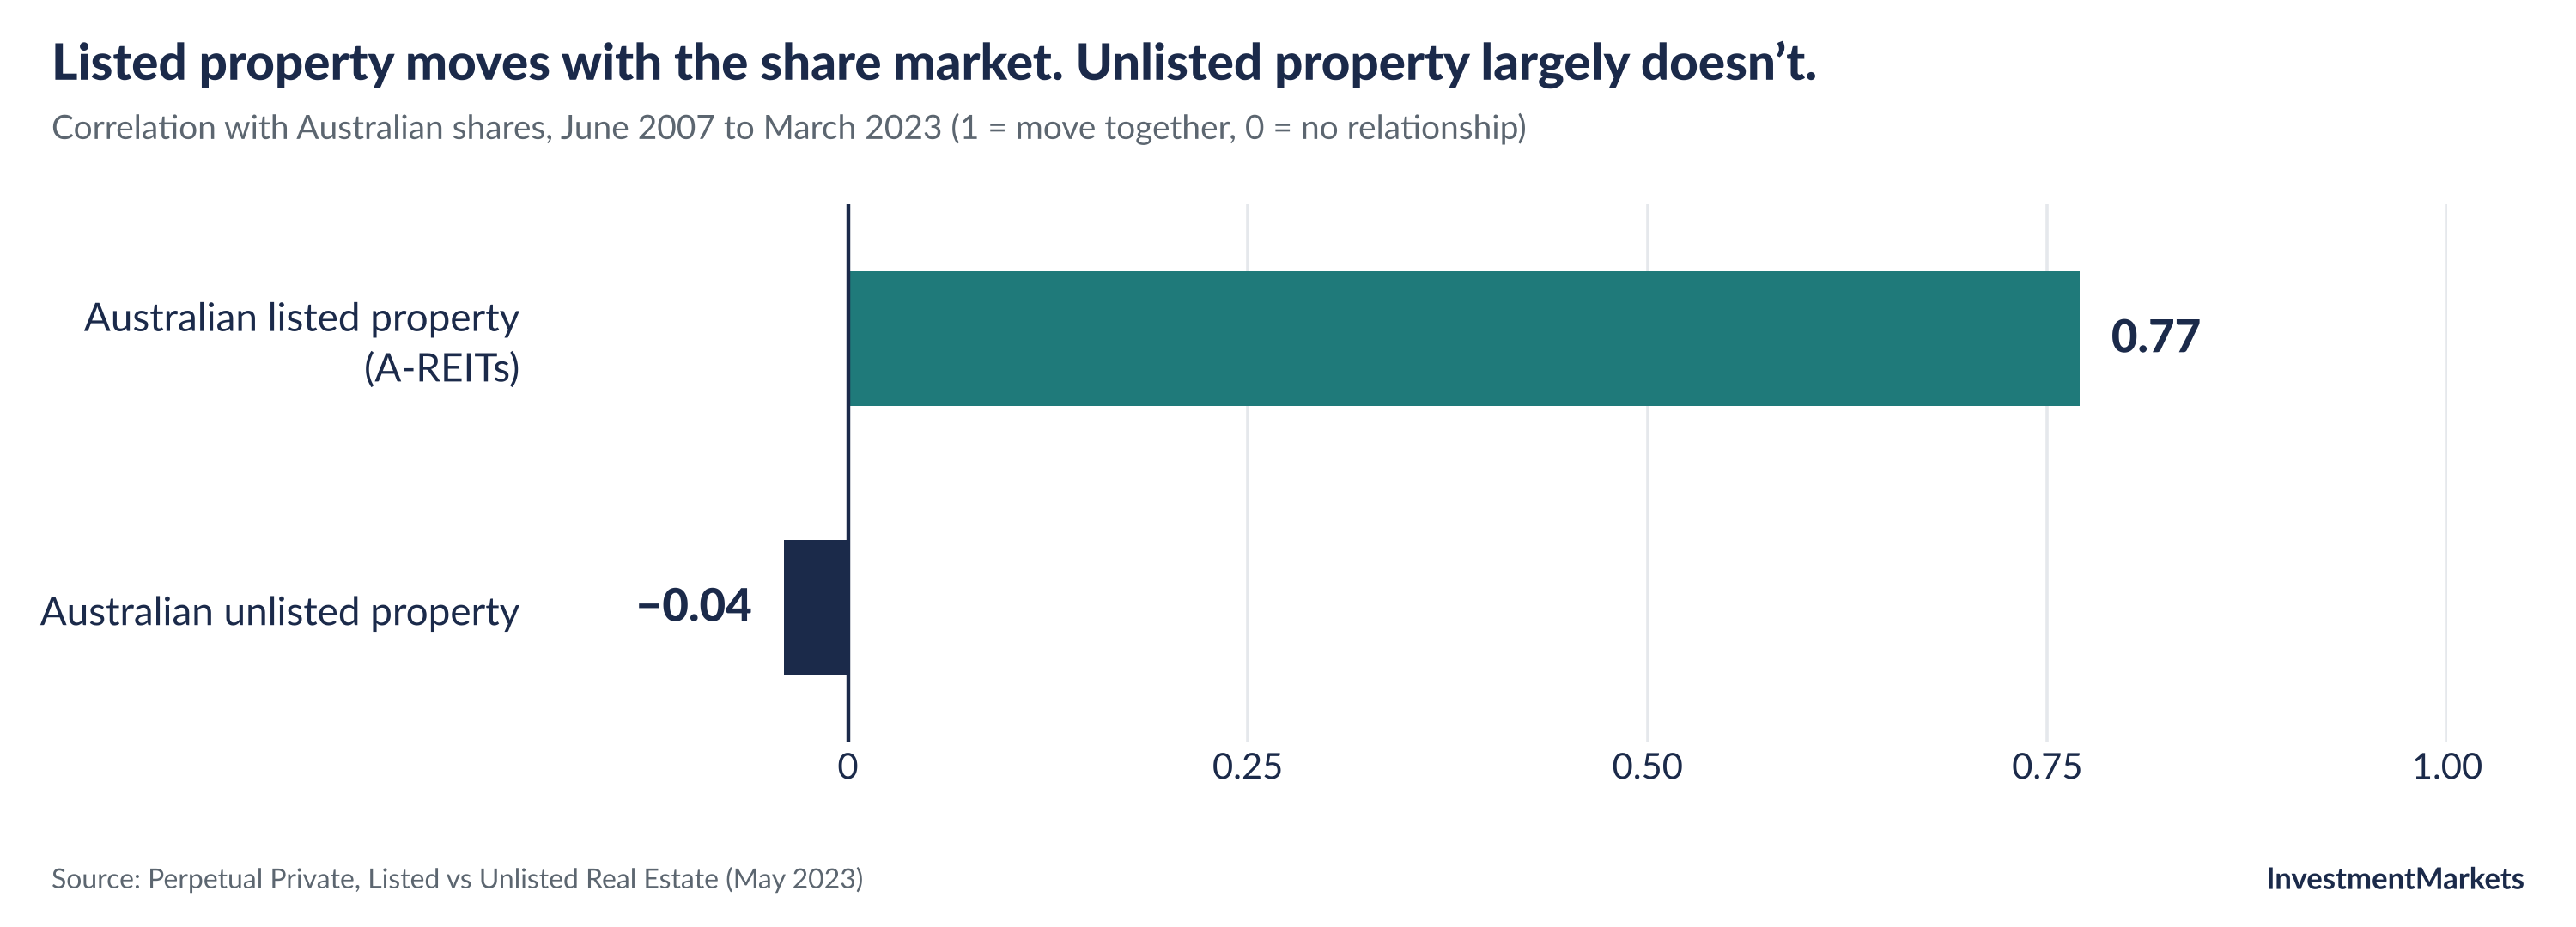
The structure you choose changes how your investment behaves. Listed funds (A-REITs) trade on the ASX and move with the share market: from June 2007 to March 2023, Australian listed property had a correlation of 0.77 with Australian shares, against –0.04 for unlisted property. Unlisted trusts and syndicates are steadier on paper but much harder to exit. This guide explains how property funds work, the main types, their benefits and risks, how to compare them, and the tax and regulatory points to understand before investing.
Key takeaways
Property funds pool investor capital to own and manage property. Investors hold units, not buildings.
The main types in Australia are A-REITs, unlisted property trusts, syndicates, development funds and property securities funds.
Liquidity varies widely. A-REITs trade daily on the ASX, unlisted funds offer limited redemption windows, and syndicates are generally illiquid until the asset is sold.
Distributions come mainly from rental income after expenses, fees and financing costs. They are not guaranteed.
Key risks include economic conditions, vacancy, interest rates, gearing, valuation lag and concentration.
Useful comparison points are fees, WALE, occupancy, gearing (LVR), valuation frequency, redemption policy and manager governance.
Tax-deferred distributions reduce your CGT cost base. They are not tax-free income.
No single structure suits every investor. Suitability depends on your goals, risk tolerance, timeframe and liquidity needs.
Australia’s property fund market in numbers
Figure
What it shows
Source
$85.6bn
Value of Goodman Group’s property portfolio, 30 June 2025
Australian commercial real estate is valued for rental income and the potential for capital growth through market cycles. Many leases build in rising rent: Perpetual notes contractual rent step-ups of around 3–4% a year in most tenant agreements.
For individual investors, direct access is hard. Institutional-grade commercial properties are expensive, demand extensive due diligence, and need active management of leases, tenants and maintenance. Without deep expertise and capital, most private investors can’t reach this market or its diversification benefits.
Property funds close that gap. By pooling capital from many investors, they buy and manage portfolios of institutional-grade real estate and offer proportional ownership at a fraction of the direct cost. The manager handles operations, and investors receive a share of the income.
‘Gain access to high-quality commercial real estate assets that offer robust, income-based returns and potential for capital growth.’Westbridge Funds Management
David Harrison, Managing Director of Charter Hall, highlights the value of co-investment in property funds:
‘Business models where a majority of the balance sheet is co-invested with investors has been a major dynamic change. And ensuring development profits stay with fund investors, rather than being captured by the manager, has reinforced long-term partnerships.’ David Harrison, Managing Director, Charter Hall (The Australian)
What is a property fund?
A property fund is a managed investment scheme in which money from many investors is pooled to buy and manage a portfolio of real estate. A professional fund manager oversees property acquisition, tenant leasing, maintenance and long-term strategy on investors’ behalf.
Moneysmart defines it this way: ‘A property fund is where you buy ‘units’ in an investment run by a professional investment manager. They pool your money together with other investors’ money and invest it in property assets.’ Managers such as Centuria offer ‘a diverse mix of unlisted property funds across a broad range of sectors including office, industrial, retail, healthcare and agriculture.’
Tip: Property funds combine scale, diversification and professional oversight with the potential for regular income and tax-deferred distributions, making them an accessible alternative to owning property directly.
Types of Property Funds in Australia: Listed vs Unlisted
Before investing, it’s important to understand how listed and unlisted property funds differ:
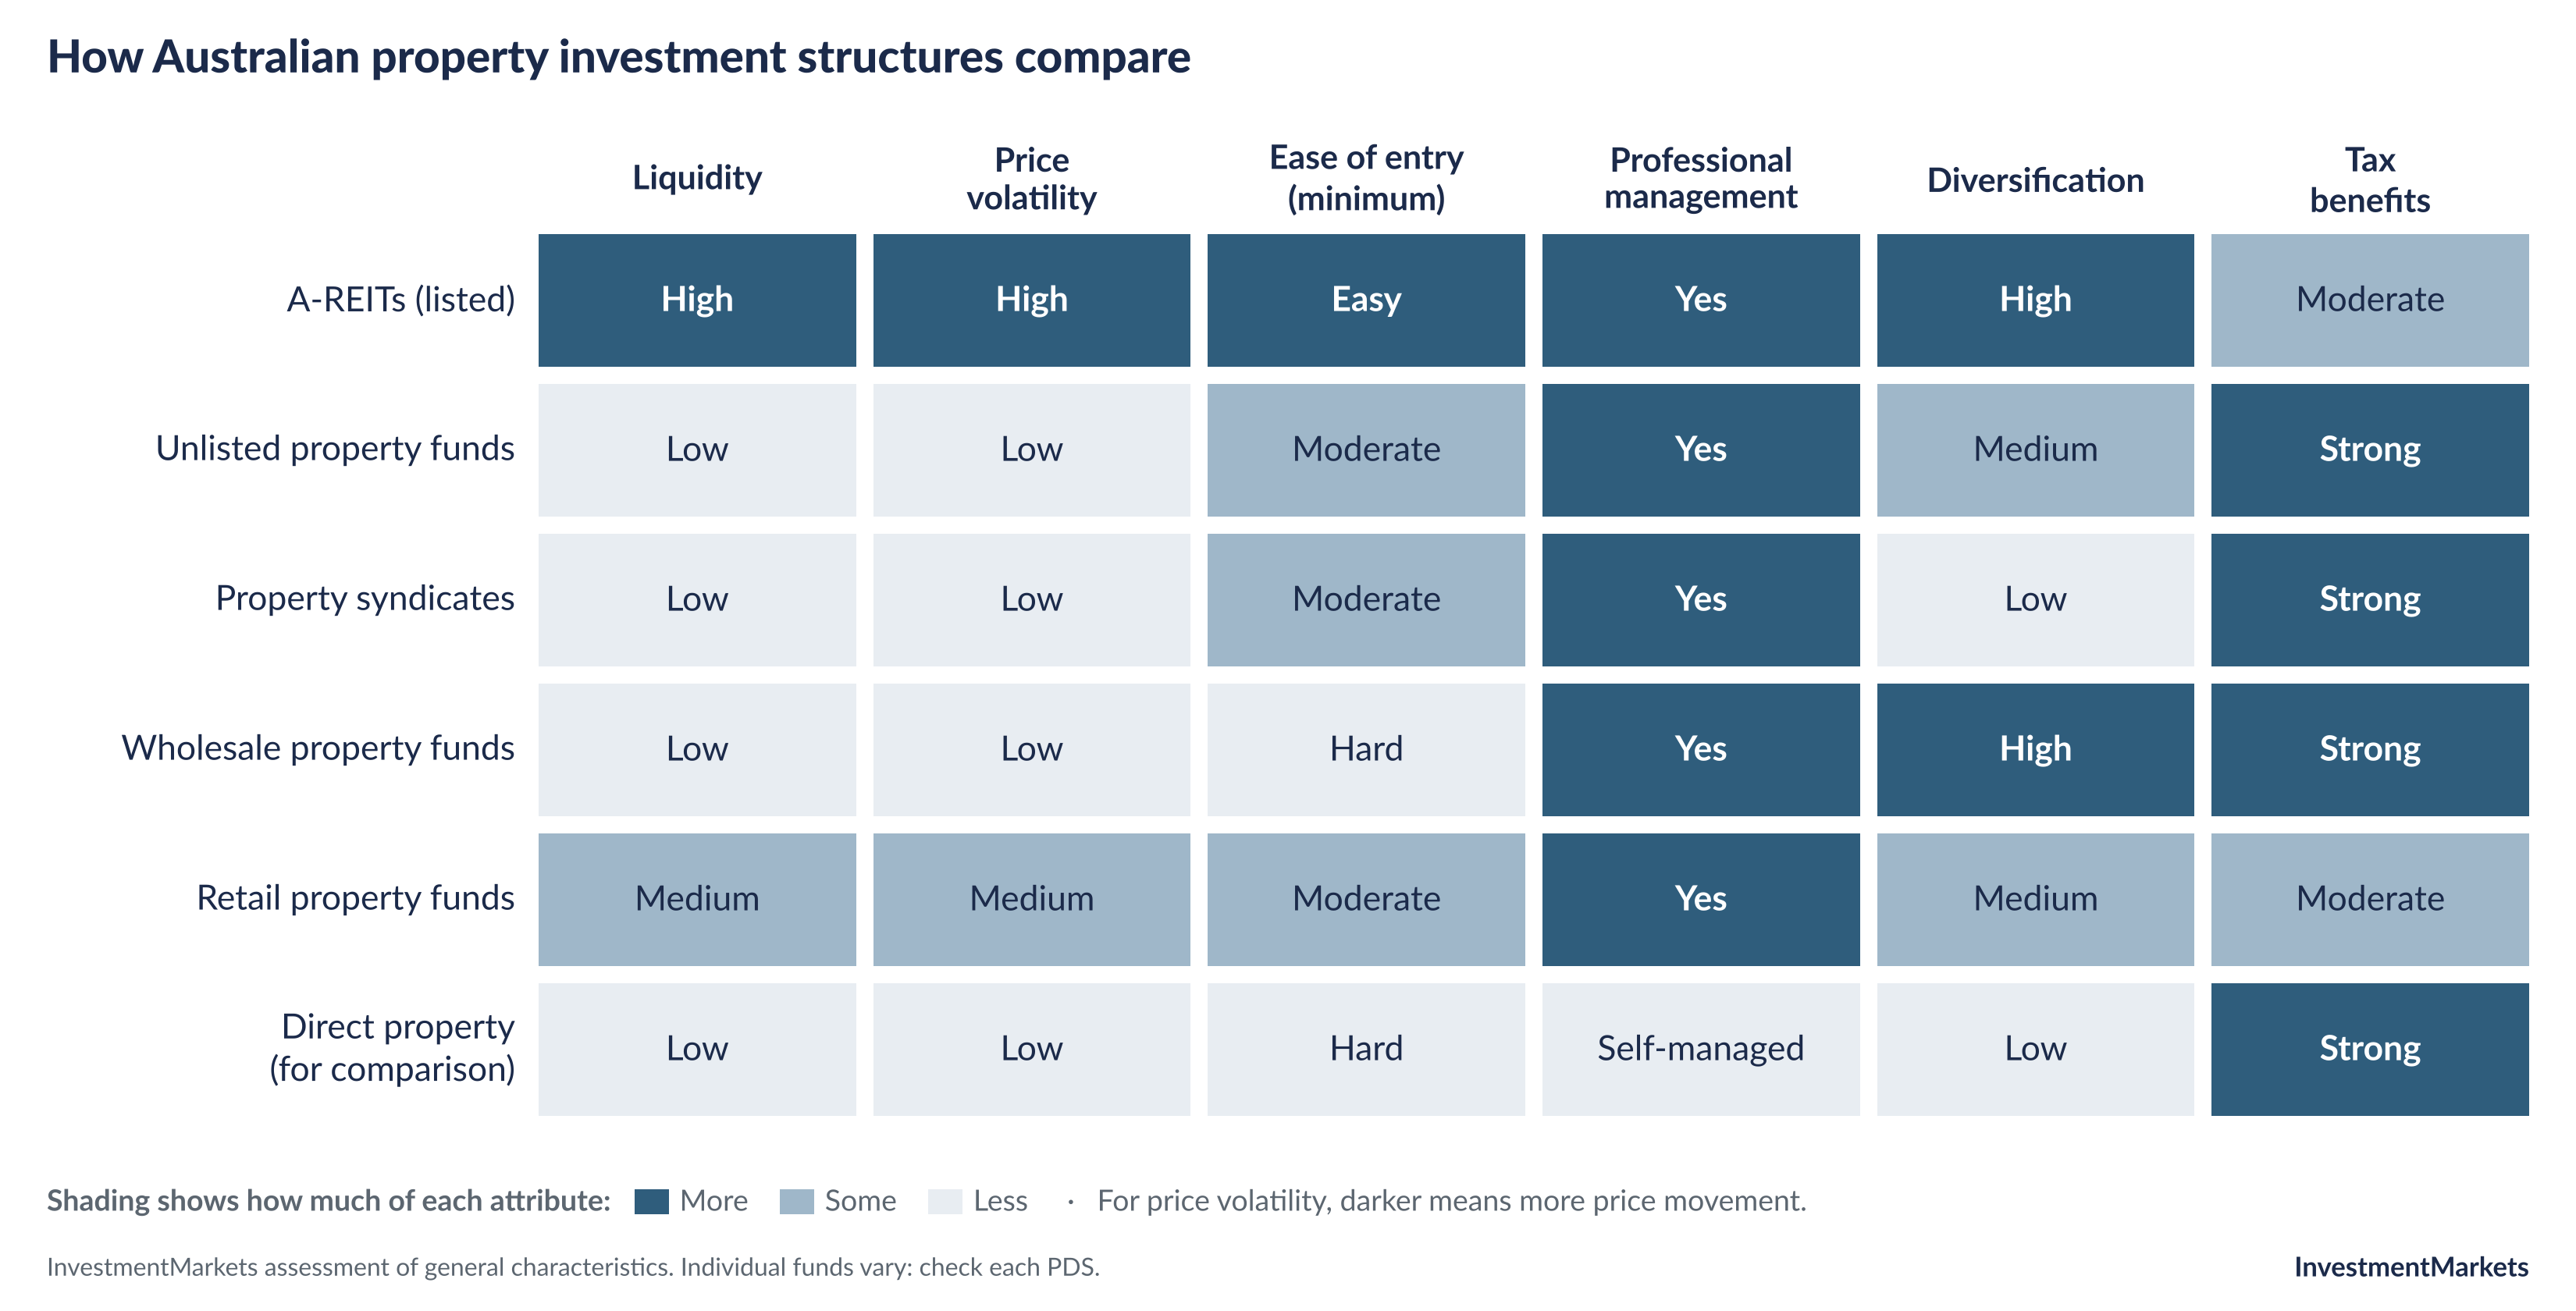
The grid below compares the main structures, with direct property included for reference.
Figure 2. Indicative comparison of Australian property investment structures. InvestmentMarkets assessment of general characteristics; individual funds vary.
Listed property funds (A-REITs)
Australian Real Estate Investment Trusts (A-REITs) are property trusts listed on the ASX. They are the most liquid way to invest in property funds because units can be bought and sold daily, like shares. A-REITs typically hold large, diversified portfolios of office towers, shopping centres, industrial estates, logistics hubs and healthcare facilities.
Volatility: higher. Prices move with the share market as well as property values. The Vanguard Australian Property Securities ETF, which tracks the A-REIT index, returned –14.95% over the year to 28 September 2026.
Ten well-known A-REITs (source: Finexia), shown alphabetically for reference:
A-REIT
ASX code
Primary focus
Arena REIT
ARF
Social infrastructure (childcare, healthcare)
Charter Hall Group
CHC
Office and industrial properties
Dexus
DXS
Office and industrial properties
Goodman Group
GMG
Industrial and logistics properties
GPT Group
GPT
Diversified (retail, office, logistics)
Mirvac Group
MGR
Diversified (residential, office, retail)
Rural Funds Group
RFF
Agricultural assets
Scentre Group
SCG
Retail (Westfield shopping centres)
Stockland
SGP
Diversified (residential, retail, industrial)
Vicinity Centres
VCX
Retail shopping centres
There are also property securities funds that invest in portfolios of REITs. Because they spread money across many REITs, sectors and sometimes countries, they can reduce reliance on any single trust. Examples include:
Liquidity: limited. For example, GDA Diversified Property Trust offers restricted quarterly withdrawals plus five-yearly liquidity events, and Charter Hall DIF4 holds major liquidity events every five years.
Volatility: lower on paper, with a –0.04 correlation to shares over 2007–2023, because pricing follows valuations rather than daily sentiment.
Structure: open-ended (accepting new money and redemptions) or closed-ended (a fixed pool of capital for a set project or term).
Property syndicates pool investors to buy one property or a small group of properties. Chant West notes that the ‘average expected life of a syndicate is typically five to seven years’ and that syndicates are ‘fixed-term vehicles with no liquidity’. Returns depend heavily on one or a few tenants.
Property development funds finance the construction or redevelopment of property. Returns depend on the project being completed on time and on budget and then sold or leased, so they typically carry more risk and uncertainty than funds holding income-producing buildings.
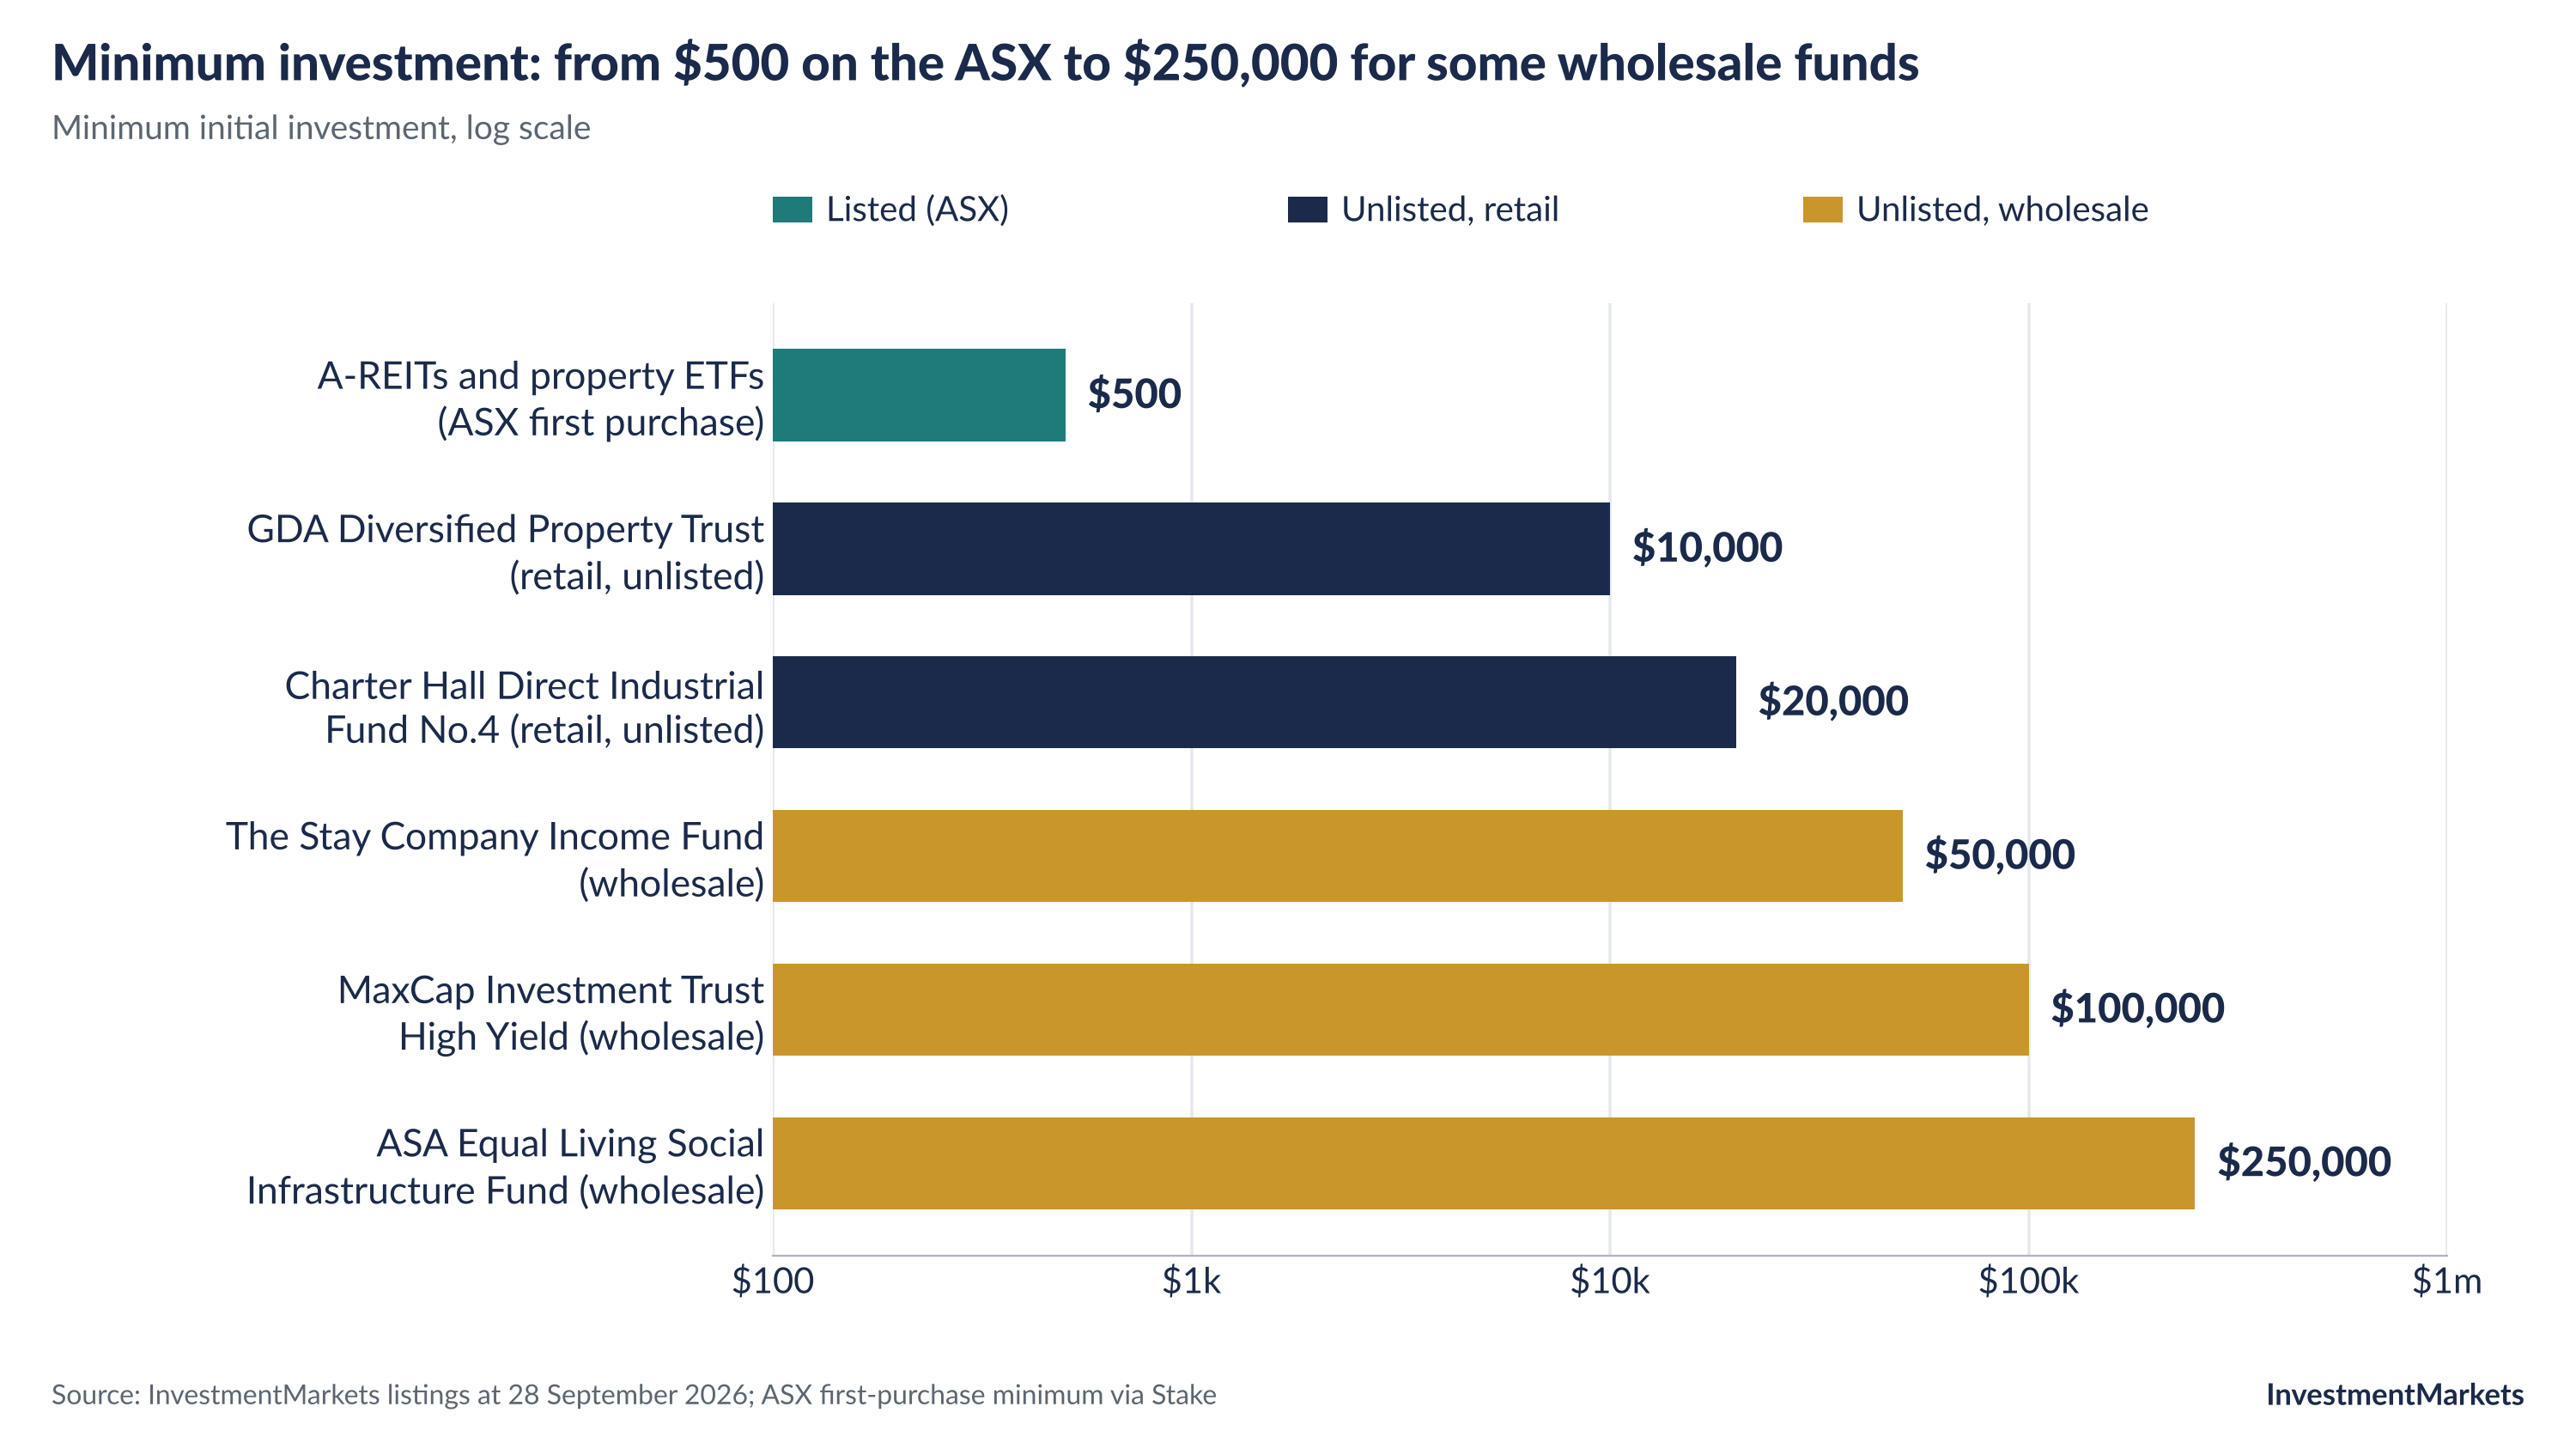
Retail funds are open to the general public with lower minimums (e.g. $10,000), and unlisted property schemes offered to retail investors must meet ASIC’s disclosure benchmarks in Regulatory Guide 46.
What Are the Benefits and Risks of Property Funds?
Before investing in property funds, understand both sides.
✅ Diversification. Pooled capital spreads your money across multiple assets, sectors and regions. As FRP Capital puts it, ‘investors benefit from exposure to multiple assets, tenants, and locations.’ Diversification is an important principle when building a portfolio that includes property funds.
✅ Regular income. Many funds pay monthly or quarterly. For example, GDA Diversified Property Trust pays monthly at 4.50% a year and Charter Hall DIF4 pays quarterly at 5.5% a year (issuer figures, not guaranteed).
✅ Tax-deferred distributions. Depreciation on buildings and fittings means part of a distribution may be tax-deferred. This postpones tax rather than removing it: the ATO requires you to adjust the cost base of your units by these amounts, which can increase capital gains tax when you sell.
Risks to consider
⚠ Liquidity risk. The main risk for most unlisted funds. Moneysmart warns they can be ‘difficult to withdraw money early’, and withdrawals may be limited or suspended in stressed markets.
‘It is critical that any investor in the real estate sector understands and appreciates the illiquid nature of the underlying asset class.’
Adrian Harrington, Head of Capital & Product Development, Charter Hall (Trustnet)
⚠ Market risk. Rising interest rates, weaker tenant demand or slower growth can cut rental income and asset values. Listed funds show it fastest: the Dexus AREIT Fund and Vanguard’s A-REIT ETF both lost around 14–15% in the year to 28 September 2026.
⚠ Gearing (leverage) risk. Most funds borrow to buy assets, which magnifies gains and losses. A-REITs averaged 28.6% gearing in FY25. Moneysmart suggests checking ‘what the fund owes (its debts) versus what it owns (its assets)’.
⚠ Management risk. Performance depends heavily on the manager. Poor acquisitions, weak tenant management or poor allocation decisions can hurt returns.
‘…it is at the manager’s discretion to buy or sell assets, so investors must have confidence in their ability to do so successfully.’
Hamish Wehl, Head of Funds Management, Cromwell Property Group (The Australian, December 2019)
How Do I Choose a Property Fund? A Due Diligence Checklist
Use this checklist to work through any fund you’re considering:
Align with your goals. Does the fund prioritise income, capital growth or a blend? Make sure its strategy matches your objectives, and that its minimum investment fits your budget.
Understand the strategy. Is it a conservative buy-and-hold approach, or a higher-risk value-add or development strategy? Your risk tolerance should match.
Scrutinise the fee structure. Understand management, performance and exit fees. Total costs on our listings run from 0.23% to 1.90% a year, and that gap compounds (see the worked example below).
Assess the fund manager. Look at the track record across market cycles, including returns since inception, and how the manager handled the last downturn.
Review the property portfolio. Look at asset quality, tenant strength (e.g. government or blue-chip tenants), geographic spread and WALE. Unlisted trusts ‘can be targeted to specific sectors or geographic locations’, so check that the focus is what you want.
Read the offer document or IM carefully. The offer document or Information Memorandum (IM) sets out the fund’s rules, risks and fees. For unlisted property schemes, ASIC’s Regulatory Guide 46 sets the disclosure benchmarks to look for.
‘The returns [on unlisted trusts] are less correlated to the share market so unit prices are less volatile and reflect undervalued assets.’
Hamish Wehl, Head of Funds Management, Cromwell Property Group (The Australian, December 2019)
How Much Do Fees Cost Over 10 Years? A Worked Example
Sarah wants to invest $100,000 for 10 years and is weighing two property funds. Both are expected to earn the same gross return of 8% a year before fees. The only difference is cost:
Fund A (low-cost A-REIT): listed property trust with a 0.50% p.a. management expense ratio (MER).
Fund B (unlisted property fund): 1.25% p.a. MER.
Fund
Gross return (p.a.)
Fees (MER)
Net return (p.a.)
Value after 10 years
Difference
Fund A: low-cost A-REIT
8.00%
0.50%
7.50%
$206,103
–
Fund B: unlisted fund
8.00%
1.25%
6.75%
$192,167
$13,936 less
Hypothetical example calculated by InvestmentMarkets. Assumes returns compound annually and are reinvested, with no tax or other costs. The fee levels sit within the range of total costs on our listings.
Key takeaway: A 0.75% difference in annual fees costs almost $14,000 on a $100,000 investment over a decade. Comparing fees is a core part of due diligence, not a box-ticking exercise.
Current Market Trends and Outlook
Four trends shaping Australia’s property fund sector:
Environmental, social and governance (ESG) considerations are now central to investment decisions. PwC says: ‘For the property sector, ESG performance will be a key differentiator and a focus of increasing regulation and scrutiny.’
Technology is changing how property is managed and transacted, with analytics and smart building systems aimed at improving efficiency, transparency and the tenant experience.
Conclusion: Are Property Investments Right for You?
Property investment funds give Australian investors a structured way to gain exposure to commercial real estate without owning property directly. Depending on their structure, they can offer professionally managed portfolios, income through rental distributions and access to institutional-grade assets such as industrial estates, office buildings, healthcare facilities and retail centres. By pooling capital, they let investors diversify across sectors, tenants and locations that would be hard to reach individually.
They are not without risk. Performance depends on property market conditions, tenant demand, lease structures, gearing, valuation timing and broader factors such as interest rates and employment. Income and capital returns are not guaranteed, and values can fall as well as rise.
Whether property investments suit you depends on your goals, risk tolerance, timeframe and liquidity needs. Listed A-REITs offer daily trading and price transparency but move with share market sentiment. Unlisted funds behave differently because of periodic valuations and withdrawal rules. Syndicates and development funds usually involve longer commitments and more uncertainty. Before investing, read the offer document, understand how the structure works, what drives its returns and where the risks lie, and consider speaking with a licensed financial or tax professional.
FAQs
No. Buying an investment property means you own a specific house, unit or building, usually with a mortgage, and you’re responsible for tenants and upkeep. A property fund is a managed investment: you buy units in a trust, and a fund manager owns and runs the properties and pays you a share of the rent as distributions. This page lists property funds, not properties for sale.
Neither is better for everyone. It depends on whether you value diversification and convenience, or control and the ability to borrow. The main trade-offs:
Factor
Property funds (listed or unlisted)
Direct property ownership
Capital required
Lower entry point: $500 on the ASX; $10,000+ for most unlisted funds
Large deposit plus borrowing capacity
Diversification
Across sectors, assets and locations
Concentrated in one property and location
Management
Professionally managed; passive for you
Hands-on: tenants, maintenance and finance
Liquidity
Listed funds trade daily; unlisted funds are less liquid
Low: you must sell the whole property
Control
Little say over assets or strategy
Full control over property, tenants and improvements
Leverage
Usually none at investor level (the fund may borrow)
Significant borrowing possible, magnifying gains and losses
In a property fund, the property investment company is the fund manager or responsible entity. It raises money from investors, buys and manages the properties, collects rent, arranges any borrowing, values the assets and pays distributions. For unlisted schemes offered to retail investors, it must disclose against ASIC’s Regulatory Guide 46 benchmarks in its OFFER DOCUMENT.
Yes. Property fund values can fall because of weaker property markets, rising vacancies, higher interest rates or high gearing. Several A-REIT funds on our listings, including the Dexus AREIT Fund and Vanguard’s VAP, lost around 14–15% in the year to 28 September 2026. Unit prices in unlisted funds may lag market movements, but valuation lag doesn’t remove the risk of loss. Moneysmart’s guide to property funds explains the risks to check before investing.
No. Distributions depend on rental income, occupancy, expenses and financing costs, and they can vary or stop. Capital growth depends on the market and is only realised when assets are sold. Past performance is not a reliable indicator of future performance.
The main differences are liquidity and how they’re valued. A-REITs are listed on the ASX, trade daily at market prices and settle on a T+2 basis, but their prices move with the share market (0.77 correlation with shares, 2007–2023). Unlisted property funds are bought directly from the fund manager, priced using periodic independent valuations, and offer limited liquidity through withdrawal windows that may be capped or suspended. Moneysmart compares listed and unlisted property funds in more detail.
In two ways:
Income: rent paid by tenants. After expenses such as management fees and maintenance, the remainder is distributed to investors, usually monthly (e.g. GDA) or quarterly (e.g. DIF4).
Capital growth: an increase in property values over time, realised when a property is sold or reflected in the unit price when properties are independently revalued.
Common fees include management fees, transaction costs such as acquisition expenses, brokerage, legal fees and buy–sell spreads, and in some cases performance and exit fees. All fees reduce net returns and must be set out in the fund’s OFFER DOCUMENT.
Management fee: an annual percentage of your investment, paid to the manager.
Performance fee: paid to the manager if returns beat a set benchmark.
Acquisition/disposal fee: charged when the fund buys or sells a property.
Exit fee: may apply when you withdraw, more common in unlisted funds.
Usually not. Exiting an unlisted fund is a structured process, not an instant one:
Withdrawal windows: the manager may offer periodic windows, subject to available cash. GDA Diversified Property Trust, for example, offers restricted quarterly withdrawals.
Liquidity events and maturity: some funds offer a full exit only at set points, such as every five years; syndicates typically run five to seven years, after which properties are sold and capital returned.
Secondary market: a limited secondary market may exist for some funds, but finding a buyer can be difficult.
ASIC Regulatory Guide 46 sets disclosure expectations for liquidity and withdrawals in unlisted property schemes.
A-REIT prices update continuously through ASX trading. Unlisted funds rely on independent property valuations conducted periodically; the OFFER DOCUMENT says how often. Less frequent valuations can smooth short-term price movements but may lag actual market conditions.
Gearing is the use of debt to buy property, usually measured as a loan-to-value ratio (LVR). A-REITs averaged 28.6% gearing in FY25. It’s a double-edged sword: it lets a fund buy more than its equity alone allows, but it magnifies losses if values fall, increases sensitivity to interest rates and creates refinancing risk when loans mature.
Moneysmart lists gearing and interest cover as key risk measures to check. Gearing is different from property debt investments such as mortgage funds, where investors effectively act as the lender.
Distributions are paid from net rental income, usually monthly or quarterly, in proportion to the units you hold. They may include taxable income, capital gains and tax-deferred amounts. Tax-deferred amounts reduce your cost base, which can increase capital gains tax when you sell. Your annual member statement (AMMA) shows how each distribution is made up for your tax return.
No. A dividend is a share of a company’s after-tax profit. A property fund distribution is your share of the fund’s net rental income and other earnings. Unlike most dividends, part of a property fund distribution can be tax-deferred because of depreciation allowances. That defers tax rather than removing it, because it lowers your cost base for CGT.
Rental income falls until the space is re-leased, which can reduce distributions and valuations. Single-tenant properties, common in syndicates, can lose all their income if the tenant leaves. Multi-tenant and diversified funds spread this risk. WALE (weighted average lease expiry) and occupancy rates show how exposed a fund is to vacancy.
It’s the legal category for investors who meet financial tests under the Corporations Act, allowing them to access offers not available to the general public. According to Moneysmart, you may qualify if you have:
gross income of $250,000 or more a year in each of the previous two years, or
net assets of at least $2.5 million.
These tests must be certified by a qualified accountant. Investing $500,000 or more in a single product can also make you a wholesale client under section 761G of the Corporations Act.
No. Office and retail are common, but property funds invest across many sectors:
Industrial and logistics: warehouses and distribution centres (e.g. Charter Hall DIF4).
Simon Turner is an ex-fund manager with 20 years investing experience gained at Bluecrest, Kempen and Singer & Friedlander who now writes educational content about investing and sustainability. He's also the published author of The Connection Game and Secrets of a River Swimmer.
The Trust is a fixed term, unlisted property fund that is forecasting a distribution yield of 8% pa and targeting an IRR of 11% to 15% pa (not guaranteed). (For Wholesale Investors Only)
The Fund presents an unrivalled investment opportunity with a primary focus on generating consistent income for investors. (For Wholesale Investors Only)
The Fund's investment strategy is to primarily invest in property development projects that take into account ESG considerations where it would be a benefit to the final revenue and value of the Fund.
The fund aims to achieve a total return at least equal to movements in the MSCI World REITs Index (USD) (hedged into AUD) over a rolling 5 to 7-year timeframe through exposure to a diversified portfolio of Sharia Compliant REIT investments.
Invest in exclusive off market properties at up to 20% below market value, no acquisition costs or holding costs. and you can start from as little as $1,000.
MaxCap’s flagship real estate credit fund, the MaxCap Investment Trust (MIT), offers wholesale and institutional investors access to a diversified portfolio of institutional-grade real estate credit.
FRP Capital presents its latest investment opportunity – the Brickworks Marketplace Fund. Access this iconic South Australian sub-regional shopping centre through our exclusive single asset Wholesale Fund.