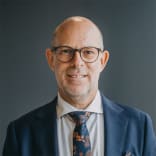
Next up, we have Vaughan Hayne, Managing Director and Co-Founder of Exceed Capital.
Vaughan is an experienced financial services leader with over 30 years of experience in funds management, specialising building and growing investment businesses and delivering quality investor-aligned opportunities.
He holds a Master of Applied Finance and Investment, is a former Executive Committee Member of the Property Funds of Australia and a Fellow of the Financial Services Institute of Australasia.
Great to have you here today, Vaughan.
Over to you.
Thank you, Darren.
We're excited to be part of this webinar and thanks for all of those who have tuned in as well.
At a high level, Exceed Capital is a privately owned wholesale fund manager based here in Brisbane in Queensland.
We've been operating for approximately 10 years now and Justin Clark and myself are the co-founders.
A big, really important part to us as setting up a funds management business was being aligned with our investors.
So when I say aligned with our investors, it was around the, in particular, the structuring of our fees.
So we are different to the rest of the industry where we charge our fees on a percentage of income, not as a percentage of assets under management.
and that really does make a difference which flows through to the small amount of vacancy we have across our portfolio and also being purely aligned to make sure that we're always doing the best for investors.
Along with that we also invest with our investors in every product as well.
It was important for us as well to hold the highest level of ethics, transparency and make sure that our communication was always very clear with our investors as well.
So we're very renowned in the industry for our communication with investors, which is nice to have.
At the moment we have approximately $450 million worth of assets under management and that is across 15 assets we hold.
That ranges from retail to office, a little bit of industrial and large format retail as well.
Our average returns to date over all of those products, which are typically being closed-ended products, but we've opened an open-ended product in the last sort of eight months, which I'll touch on later.
They've been very good strong returns with upwards of 8% per annum cash returns, plus a tracking IRR somewhere around that 20% per annum, which is being well received by our investors.
I guess property to us is a great area.
We focus on commercial property.
But I guess the question is why property in a volatile market or volatile conditions like we do have at the moment?
My feedback to that would be is that first of all, generally property does have a lower volatility compared to many other assets or asset classes, especially when you're referring or looking at unlisted property.
It's got very strong supply and demand dynamics.
So with good quality commercial property, there is always a demand there for the property.
And especially in growing regions like Queensland, for example, where you've got growth there of population, which it's estimated that we're going to have another 2 million people coming to Queensland.
which is going to mean about 900,000 new homes.
And then as well with the Olympics coming up in approximately seven years, there's going to be the, let's call it the tailwind or the boost with the Olympic growth as well.
So it's a very strong dynamics on that basis.
Cash flows under property are also very important, and the benefit with commercial property cash flows is that with your annual rent reviews, it is what they say a hedge against inflation, meaning that every year the underlying rent goes up by a certain percentage, which offsets that against any increases in CPI and that side of things in the economy.
stability of returns is another important factor under property.
And that comes down to the fact that commercial property is backed, the income streams from that is backed by underlying
leases there and obviously with good quality commercial property you've got very strong tenant covenants whether it be ASX listed companies or national brands it provides a stability and security around those returns.
Scale of assets, so when we put together a product, we basically pool investors' money and we put that into better quality assets than what a typical person may be able to afford or be able to invest in themselves.
So by pooling investors' money together, we're able to target
lot better quality tenant covenants.
So that might be for example if you're owning a office building or a neighbourhood shopping centre and it might have Woolworths or Coles as an anchor tenant for example.
Where opposed to if you're individually doing it and you may have two million dollars to invest, your tenant covenant would typically be a lot lower.
What does that all mean?
It's all around, again, meaning that property is more secure.
It's tangible.
You can actually see it.
You can touch it.
And historically, it's been a lot more consistent store of value, so to speak.
So it does become a bit of a safe haven for good quality returns.
Typically, investors
They would probably have about maybe 20% of their portfolio allocated to unlisted property vehicles or companies like ourselves.
As for mine, it's probably sitting there around that 98%, 99% allocation.
But hey, you invest in what you know, right?
The property market at the moment, what are we seeing?
We're seeing some good buying opportunities, in particular where there's been a bit of pressure from the listed real estate companies.
We've been seeing some really good opportunities to pick off some of the non-core assets, so to speak.
The construction costs in the industry and labour costs have obviously been at the record high.
That's no surprise at the industry at the moment, especially with construction slowed down as well with a lot of the unions and that side of things.
What does that flow on?
Those higher costs means that there's less supply.
So that's from existing commercial property owners.
That's generally a good thing because less supply, more demand pushes up rental prices.
And I'll give you a bit of an example.
At the moment on the Gold Coast, there's a vacancy there of A grade office building of less than 1.7% at the moment.
So it's the lowest it's ever been.
And Brisbane, you're sort of sitting there less than around
just under sort of 10.5% or thereabouts.
So what we've seen is a big flight quality in office space in particular, where you're getting tenants coming from the fringe city into the city and tenants from B grade buildings moving up into A grade buildings, et cetera, et cetera.
And also in Queensland in particular, there's been the population growth.
So with that population growth, it has also put more pressure on occupancy levels and the low vacancy rates.
We've seen incentives reduce where they used to be around the Gold Coast, around that sort of 25% incentives.
And even in Brisbane in A grade, some of them got up to 40 and 50% incentive.
Now we're seeing that reduce down to around that 20%, even below in the Gold Coast, to sort of 15%, 10% incentives.
We're also seeing rents there because of that demand and that limited supply and limited new construction.
We've seen rents there increase in the Gold Coast 40% in two years.
So some of our A-grade office buildings, we've seen rents go from approximately 460 a square metre up to approximately $650 a square metre, a recent deal we did with a government tenant there.
So really big improvements in those rents, which is fantastic for asset holders.
What that's also flowed through to with those assets is where we've been able to get returns, cash returns to investors in double digits.
One going right up to approximately 17% per annum, which is outstanding considering our target of return was actually only 9% per annum.
What we're also seeing as part of this market and continuing state of flux is that people are also repositioning the older assets at the moment.
They might be repositioning them to the same sector being, for example, office and moving it from a B grade quality to an A grade quality to collect greater rents.
When you're looking at commercial property, we'll just run through, I guess, a few things to consider and look at.
And I guess we'll break it down to three areas.
First of all, asset itself, the numbers, and the environment as well.
So first of all under the asset, things to consider is diversification.
Naturally, the old story, don't put all your eggs in one basket, but diversifying your investment within assets.
So that reduces risk, which basically reduces volatility of returns.
So it's important to understand also the ongoing capital expenditure and leasing link to that property, the costs around that, and it's important to do a very thorough due diligence so therefore you've got no surprises when it comes to five years down the track or something like that.
Proactively managing outgoings is very important.
The reason for that is depending on if you're on gross or net leases, if you're on gross leases, it flows directly through to your bottom line.
So therefore it impacts your returns back to investors.
So it's important to make sure that your outgoings there are managed proactively.
And also for tenants on net leases who are paying those outgoings,
you want to ideally reduce those to a level which is affordable for those tenants so therefore it's not putting them under additional pressure.
Because if they're under additional pressure and they're trying to run their own business, naturally it means that they're more likely to potentially go into rent arrears or alternatively when it comes to the end of that lease term they may not renew
Numbers with regards to that, that comes under gearing levels.
So typically we would gear our properties at around 50%.
Ideally it would be good to have a 5% head space too in your LVR levels.
Interest cover as well, just be aware of that with the ongoing cash flows.
Typically at the moment we've seen it sort of around 1.5 times.
And then it's important to also understand how the debt is structured.
For example, the loan term, also the security which is required behind that debt facility.
For example, if it's a non-recourse loan or limited to the asset only, risk margins, meaning on top of your, so what you're paying as part of your interest rate, and so it might be your BBSY plus a margin on that, and that may vary as well depending on market conditions.
Also, where possible, it's good to look at hedging.
We use on-market swaps to be able to hedge out interest rate risk and swap our variable interest rate for a fixed rate for a certain term and potentially be able to gain higher returns to our investors from that hedging as well.
Under the environment, due diligence is an important thing.
It's very important to be very thorough with your due diligence.
Have very strict processes and procedures around that.
Alternatively, if you don't have the capabilities of in-house doing it, bring somebody external, one who is very well experienced at that.
We run our due diligence in-house along with some consultants for some parts of that.
We generally have a 110 point due diligence checklist which we run through, so we're very thorough around that.
And then it's important to understand the environment, making sure that you've ideally got multiple economic drivers which are in the area which you're investing in.
It's all about reducing risk and making sure that we're setting up the fund for stable long-term performance.
With regards to buying properties as well, we take ourselves a top-down and a counter-cyclical approach when we're buying assets.
So top-down, high-level, we're looking at economic drivers, working out where is opportunity and we look at, so we chart, we're big numbers people here.
We chart the long-term averages with regards to the different property sub-sectors, so it might be office, it might be retail, it might be medical or allied health.
We chart where the current capitalisation rates are with that, with regards to long-term averages, and then where the cap rate is softer than the long-term average, meaning higher than the long-term average.
it means that basically there's good buying opportunities and then we look to sell when the cap rate is tighter or lower than the long-term average and that's where we look to add money for our investors.
What I'm going to touch on is diversification and I guess how we diversify in our fund, which we started approximately eight months ago, which is The Collective.
The Collective is a truly diversified property portfolio across multiple property asset classes or sub-sectors and also location.
When I say truly diversified, what do I mean by that?
It's not just a diversified office fund or an industrial only.
We use our structures and our strict methodology around where there's opportunities in the market and the cycle of property.
to be able to identify where we can purchase well.
A lot of the time there's one or two property sub-sectors which are at a different point of the cycle as others and that provides buying opportunities.
It was important for us as well with the collective to provide flexibility to our investors.
So that's flexibility both on the way in, meaning that it's open-ended so investors can invest in that fund at any point in time, but also flexibility on the way out as well if people want to reduce their returns or want to sell out of their investment for whatever reason.
So we created what's called a managed liquidity process, which means that we ask for investors to invest for a minimum of a two year period.
And then after that, we provide a bi-annual or every six months, a redemption facility, which allows people to get out at the market unit price.
And that happens two times a year.
And there is a cap on that as well at 5% of equity issued.
And what that just prevents is a big run on money where we're forced to sell assets to be able to help liquidate people's positions, which impacts those who want to stay in the longer term.
As part of our asset allocation as well, we make sure that we've always got a 5% minimum allocation in our portfolio to liquid assets, and that's to be able to fund that liquidity as well.
The collective is all about stable cash returns.
So we say that we'll deliver returns between seven to 8% cash per annum.
There's also tax deferred benefits on that, which would be approximately 40 to 50% on top of that.
And those returns are paid monthly.
Within the collective we currently have four assets or five properties in total and that's across medical, allied health, A-grade office, data centres and other government tenant focused as well.
So it's a very strong portfolio.
We see this as our flagship portfolio and looking forward to seeing how that grows over time as well.
Thank you Darren for that.
Thanks Vaughan for the insights into the operational mechanics of XSEDE.
I've got a couple of questions if you don't mind.
The first one is, with the collective, was there a particular investor trigger that led you and your colleagues to decide to set up that fund?
Yes there was actually.
So a couple of different things around that.
So one was that some of our investors were aging because we're a wholesale fund manager.
A lot of our investors invest through self-managed super funds and they're retired.
So some of our closed-ended trusts which would have a five or a seven year investment period were starting to get a little bit too long for them.
So they wanted a bit more flexibility with shorter investment periods.
So that helped out those investors.
And then we also had other investors where, for example, I've got a couple who would often ring me up around 30th of June around tax time and they would have some money to invest.
And we often
wouldn't have a product open because we typically had only closed ended products and we might only be doing two of those a year.
So it depended on the timing and they might only be open for a month of capital raise.
So yeah, we created a product around flexibility for those investors as well.
and investor demand, which is always a good place to be.
Absolutely.
And maybe finally, Vaughan, as a counter cyclical investor, which areas of the market are you looking at closely at this particular point in time?
The example from the Gold Coast, the old Gold Coast office building was very good.
Where else are you looking?
At the moment we are still keen on office.
The reason for that it goes back to that counter cyclical top-down approach with our investing and right now office is in some locations has been sold down by some of the listed companies.
Still a very strong sector just because of working from home and things like that we're not seeing
that have a long-term impact.
So we're still seeing a lot of demand around office from a tenant side of things.
Queensland, South East Queensland with the population growth.
So Gold Coast used to be the fastest growing population with regards to interstate migration across Australia.
That's now gone to the Sunshine Coast and the Gold Coast is second.
All of that's driving that population coming into Queensland, as well as with the Olympics, is driving more people moving up here for affordability, which then they need naturally jobs and is putting more pressure on the office environment.
We're seeing still great opportunities in office where we're able to purchase somewhere between 40 and 50 percent below replacement cost.
And even then we're buying below market value as well.
So that's just a unique situation which hasn't been around for a long period of time.
And ultimately property always comes down to supply and demand, Vaughan.
And it's certainly in your favor at this particular point of view, particular point of time as a property investor.
Agree.
Absolutely.
Well, thank you very much for this interesting insight boat into the business exceed the collective and the market and what you're looking at.
Thank you very much for your time.
I'm sure the audience will find that very interesting.
Thank you very much, Darren.
It was a pleasure to be part of investment markets and the webinar.
Thank you.
Why Diversification Is the Foundation of Smart Property Investing
Vaughan Hayne from Exceed Capital - Investor Webinar March 2026
About this presentation
Vaughan Hayne, Managing Director and Co-Founder of Exceed Capital and speaker in the March Investor Webinar ‘Finding Value in Volatility’, presents commercial property as a resilient, income-generating asset class in volatile markets. He highlights the benefits of unlisted property, including stable cashflows, inflation-linked rental growth, and strong tenant-backed income streams. Vaughan explains how Exceed’s investor-aligned model, including fee structures and co-investment, reinforces long-term performance and transparency. He also points to favourable market dynamics, including low vacancy rates, rising rents, and supply constraints, particularly in high-growth regions like Queensland. A central message is that high-quality commercial property can act as a defensive anchor within a diversified portfolio.
Disclaimer
- The presentations made during this seminar are for informational and promotional purposes only.
- Any comments made or information provided does not consider the appropriateness for you having regard to your particular objectives, personal/financial situation and needs. Before investing you should consider independent professional financial advice.
- No comments made or information provided constitutes advice, an invitation, or an offer to buy any security or other financial product or engage in any investment activity.
- All securities and financial products involve risks.
- Past performance of any product is not a reliable indication of future performance.
- Read carefully the governing documents of a product’s offering such as its PDS or information memorandum.
- InvestmentMarkets does not vet, endorse or recommend any product the subject of the presentations and is only facilitating the exposure of the product.
- These presentations were made as at March 2026, and therefore relevant facts, the economic environment , governing documentation and the law upon which they were based may change after that date such that the accuracy and reliability of their content may be affected.
Featuring
More Videos








