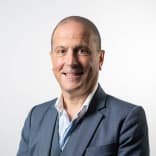
Next up, we have Michael Fazzini, Sales and Distribution Executive from Capru.
Michael is an experienced capital raising professional with a strong background in investor engagement and distribution strategy.
He works closely with advisors and wholesale investors to communicate Capru's investment offering and support capital deployment across phones.
We're looking forward to hearing about the evolution of your offering.
Over to you, Michael.
Thank you Darren and hello everyone.
So I work for a business called Capru.
We started about seven years ago and maybe I'll just take it back to what our objectives were when we started the business.
We wanted to do two or three things.
The first thing we wanted to do was to make property development an asset class that is
reasonably easily accessible to investors.
So the entry point is a hundred thousand dollars which generally if you're doing property development on your own it's impossible to access that sort of capability at such a low level.
The second thing we wanted to do was one of the things about property development is you get too uncertain
estimated outcomes and you need to sort of work out whether you can live without uncertainty.
One is the rate of return on a development is forecast and you need to wait and see how it pans out.
Secondly, you don't quite know when you might get your capital back.
You get it back at practical completion and the sale and that's forecast but you don't quite know.
So we wanted to take out the uncertainty of what the return might look like from an investor's perspective and when you get your capital back.
And the third thing we wanted to do was always tick property development on its head.
We wanted to allow investors to access the attractive returns that are inherent in property development, but to deliver those returns as a predictable regular income stream, which is quite different to the normal way you think about accessing property development.
Now this led to the creation around seven years ago of our first income strategy which was a note structure called the secured income notes and subsequently we've developed a managed fund that's called the income opportunity fund.
So let me just talk through how we actually convert property development as an asset into a regular predictable income stream.
And it all comes down to what we do, which essentially is what investors are really backing us in is it's our capability.
We are what we call a build to sell property development led funds management business.
So we operate a portfolio of property development assets that are what we call short duration.
Now short duration is because when we actually finish a development, we don't look to hang on to it.
We don't look to own the asset long term.
We want to extract those developments inherent within development, as I said.
So that creates a natural flow of cash.
We're constantly buying, constantly selling developments.
and it's that cash flow that provides natural liquidity.
Now whilst we run a liquidity overlay to ensure we hit our income targets, that is a fundamental driver of being able to provide regular income to investors off the back of this asset class with property development.
So it's really important to understand our process and how we go about actually managing risk because it's a bit of a throwaway line, but there are many risks in property development, but they are largely manageable if you have a dedicated risk framework.
And really, this is what I think sets Catprewer.
apart from many other participants in this market.
So let me just build out that whole risk management framework.
The first thing is we operate in the mid-scale property development market.
So think about a development with a total development cost circa up to 80 million.
Why do we like that sector?
Well, it's too big for mum and dad, and it's too small for the large institutions.
So what you're left with is quite a fragmented market that presents many opportunities, but no real structured, disciplined approach.
You know, you've got property developers themselves operating in that space.
So we're not really competing with anyone that's sort of got that really hard-edged risk process.
Now let me flesh out how the risk process looks like.
So I mentioned it's mid-scale in size, but we're very specific on the types of developments.
So when it comes to commercial, we generally don't do your typical shop or office.
What we like is special purpose commercial.
So think industrial warehouses, strata title industrial sheds, service stations, medical centres, childcare centres, fast food.
Why do we like that part of the commercial market?
because it's much more stable through the business cycle.
So if you think about shops and offers, whilst they've got structural head wings, and I think we're all aware of, they also operate sort of throughout the cycle.
So when the markets and the economy is stronger, demand for office space is better, we spend more, etc.
But it goes the other way.
So we try and avoid that cyclicality around the developments in our commercial expertise.
And that's because what you want to find is a healthy buyer's market when you're ready to sell, no matter where you are in the cycle.
When it comes to residential, we don't do high rise towers for argument's sake.
We like
to basically cap out at four or five stories.
So if we do an apartment building, but we like also very much your town homes.
Now, the other thing about the way that we target the sorts of developments is if you think about most commercial developments I spoke about, they're easy to build.
They're four walls and a lid.
That means the builder risk is actually much lower.
They're not as complicated.
So there's good reasons why we target those very specific types of developments.
In residential, again, I should have said, the reason we don't go above four or five floors, two reasons.
One is, plus the construction goes up when you get above four or five.
But secondly, you're left with a lot of stock to sell.
That can lock capital up.
Because remember, we are a build to sell manager.
We get those profits in development.
We're not a passive owner.
We need to get in and we need to get out.
The next element of our risk process is what we call price discovery on a piece of land that we would acquire to develop something.
This is absolutely fundamental because here is an inside secret if you're not aware.
Guess where most of the profit from property development comes from?
It comes from what you pay for the land.
Then your risk process is all about guarding that profit, ensuring there's no blowouts, either time or cost, et cetera.
So you need to have a way of working out what to pay for a site or what not to pay.
So this is what we do.
We, before we put any development into a fund that we may expose investors to, we need to work out what type of development approval
we can get a DA.
So either we get a DA or we have a very high likelihood of we know what the DA might look like.
Once you have a DA, development approved, you know what you can build.
So then we actually get evaluation of the finished product.
Now let's say it's worth $110 million in the arbitrary figure.
We then work backwards to work out the land price.
$110 million, right.
What are the build costs?
What are the costs to pay the bank?
Because we do borrow what we call senior debt from the bank.
What are the costs to investors who invest with us?
And what's Cap Prove's minimum return on cost to make the project viable?
That essentially spits out a land price that you shouldn't go above.
So market price for land in our world is not last transaction of a similar site.
It's not per square meter.
Yes, we might look at that.
It's what works in our proprietary model.
Now, this is absolutely key is to not overpay.
And then we do some pre-work again before the asset comes into the fund.
So getting a DA is part of the pre-work.
So we rarely go cash on condition on a site.
What we do is put an option.
That could be seven months, eight months, whatever, and do a lot of work before we bring the asset in.
That includes some pre-leasing work, getting the build attenders done, so you're ready to go from day one.
The other thing that's really important is property development is so localised, you know, relationships with local councils, architects, builders, it's really important to have boots on the ground.
So we're a national business where we've got development managers all spread throughout the country and they get a really good deal flow, which obviously is really important for us because we're a very active property development manager.
So that led to the creation of that fixed income opportunity that I spoke about.
So the Income Opportunity Fund is a fund that pays the RBA cash rate plus 7% per annum net of fees.
So that's a great inflation hedge strategy because we're seeing cash rates going up at the moment.
Why they're going up is inflationary fears, cost of living pressures, so then we pay a little bit more.
Similarly, if inflation is falling, stylistically you expect cash rates to come down.
So again, cost of living should come down, so therefore the crediting rate that we offer investors doesn't need to be quite as high.
So right now, as of the first of next month, the crediting rate is 11.1% per annum net, paid monthly.
Again, how do we do that?
Short duration assets, build to sell, funds management business.
Now for the seven year journey we have met 100% of our income commitment, 100% of our capital commitment and that's led to a lot of our investors saying I'm really happy with the return profile you've been delivering.
But can I actually make what you make cap proof?
Because if you think about our portfolio approach, each individual development within that fund, it's actually not that relevant what it actually returns.
What the commitment is, is that we meet that income payment and we take the uncertainty or the volatility around what those underlying developments might actually deliver.
So some might do better than forecast, some might not do as well.
But investors who all of a sudden, well not we shouldn't say all of a sudden, over the journey,
backing our capability, want to partner us.
They want to chase that upside.
So we launched a few years ago a range of development equity funds where investors can actually participate alongside us and their rate of return is precisely what that development delivers.
And of course, as I said earlier, that's your more traditional approach, but that means the forecast return and the forecast time is uncertain.
but they're short duration assets.
So I can point to our very first development equity fund which we paid investors out about a month ago.
We thought that was a development, a strata title warehouse that was developed in Jandacott, Perth.
The forecast period was an 18 month hold period.
Put your money in, 18 months later you get paid.
And the forecast return was an IRR, internal rate of return of 18%, which effectively in simple terms is a per annum return.
We delivered that development in 14 months and we delivered a return to investors of 40 IRR, 40% per annum, four zero.
Extraordinary outcome.
I think we got a little bit lucky, but we have got the skill set and the risk framework to give us confidence that we can hit the objective.
Now, not suggesting we can do that all the time, but we are at the moment, we are capital raising for a third, our third development equity fund, which will include two or three strata title industrial warehouses, one in Victoria, one in Queensland, possibly one in New South Wales.
Why do we like Strata title industrial warehouses for this type of exposure to investors?
Well, they are very short duration.
One to two years and you can spit it out.
That's great.
And secondly, there's a lot of potential buyers of that sort of asset.
You've got investors and you've got owner-occupiers.
And what we're noticing is investors that like to hold property might have traditionally bought a residential home to put in their self-managed super fund.
They're now looking at strata warehouses.
Because they could actually sell, in fact, Jandacott as an example, the average sale price, I think we had about 48 sheds that we sold in that development in Perth, in our first equity fund, that actually sold on average about $900,000.
That's actually cheaper than the typical average house price.
And you could argue the yields are a little bit solid and maybe the demand might be better, so a bit more capital growth over time.
but they are really attractive and they tend to range, we can subdivide between 150 to 400 square metres.
So you've got a very diverse buyer market.
That's what you want when you're a good development manager.
You want to be able to have a strong buyer's pool because we do extract that profit, as I said, built to sell.
So essentially what I'm saying is our journey is really interesting.
We started by being quite different in terms of a property development fund manager.
Think of it like looking through the lens of a risk manager at bank or fund manager, not through the lens of a property developer.
we wanted to provide a different type of exposure, an income exposure.
We've done that very successfully and of course now there was demand for us to offer your more traditional exposure which is your equity exposure and with you know thankfully our first one anyway was a great success and they were onto our second one is closed onto our third.
So do reach out you know we love talking to investors we think we're very different but we do have that fundamental appeal.
A lot of investors
they either think they know property or they're attracted to property so it's a natural area of interest so we're just trying to feel what we think is just some really strong demand in that area.
So Darren back over to you that hopefully sort of gives a bit of a snapshot of who we are where we've come from and where we are today.
Thank you very much, Michael, for highlighting the evolution of the product structures within Capru have been offering.
Property, as we know, and as you alluded to, is often quite cyclical.
Which of your offerings do you think are most attractive to investors at different points of the economic cycle?
Quite an interesting question because cyclicality is something investors constantly think about in terms of which assets they might want to take exposure to.
So for example within listed equities, these periods where they seem to be attractive and maybe right now they might be slightly less attractive, but even within equities there's this is it value, is it growth style, so there can be a natural rotation.
And things like government bonds,
enlisted credit.
When bond yields or credit spreads are rising it tends to suggest that asset class is less attractive, maybe you allocate less.
When they're falling you might want to get involved.
It's not so much the case with us because effectively our returns are driven by a fundamental bottom-up analysis of each development before we take exposure to it.
So it's not as if a certain part of the cycle favours us more than another part.
Sure, we would like lower interest rates versus higher, but understanding our proprietary feasibility model, we built in interest costs.
So again, to try and get that price discovery in a piece of dirt, we are looking at current drivers and inputs all the time.
And if all of a sudden
cash rates are far too high, well then maybe we are more selective and do less developments.
But the investor gets exposed to what we believe is a high chance of those developments being profitable and delivering on our investment objectives.
So we are, even though we're an active build to sell manager, I would argue our offerings are buy and hold.
because I think you'll get a very consistent very transparent journey when you invest either in our income or our equity strategies.
And consistency is certainly something that I think people are looking for in given what's going on in the markets at the moment Michael.
Absolutely.
So how should those investors then, if they're looking up your product offering, how should they think about those products in terms of their own portfolios?
Maybe if you could draw that out as an example.
Sure.
I guess the first starting point is,
When you build a portfolio, when you introduce an asset to your current portfolio, what you're looking for is confidence that that asset or that manager will deliver on an absolute basis.
And secondly, it introduces something different to the other parts of the portfolio.
In other words, you're looking for true diversification.
So I would argue that a lot of assets that are currently in portfolios tend to be listed assets.
Now listed assets and we're seeing a great example now because of the wall where market sentiment and weight of money shifts pricing.
Not necessarily the fundamentals at the company level.
but really just the buying and selling.
That doesn't really impact what we offer.
So I think we immediately look like a really smart way to diversify your overall portfolio.
So in our fixed income offering, we are an alternative fixed income manager.
That's an interesting description because we are alternative because we do something different.
But yet we offer what investors would argue is what they're looking for in a traditional sense when you buy fixed income.
My capital doesn't move and I get regular income payments.
So we actually do that.
So I think we look really attractive, either stand the line, but if you put us with other fixed income managers in that fixed income allocation, we provide rich diversification.
And similarly, if you're allocated to our Development Equity Fund, then what you're really getting is an active, not passive property approach.
You're getting pure property development.
Most managers tend to offer property assets that are based off rents, which drive the yield, and then hopefully capital appreciation over time.
There's not too many that give you pure property development exposure.
So again, if you had property managers in a portfolio, just think about adding that equity fund to that property allocation, you're getting different drivers to the overall portfolio.
And I would argue a really solid standalone outcome from a fund manager.
So I just think we are quite different, very experienced at what we do, and we offer some great portfolio diversification benefits as well.
Diversification is certainly top of everybody's minds these days, Michael.
Thank you very much for highlighting Capru's journey on the products and how they've evolved over the last few years.
My pleasure, Dan.
Thanks for the invitation.
The Evolution of CapPru’s Real Estate Investment Offering
Michael Fazzini from CapPru - Investor Webinar March 2026
About this presentation
Michael Fazzini, Sales and Distribution Executive at Capru and speaker in the March Investor Webinar ‘Finding Value in Volatility’, explores how property development can be transformed into a predictable income-generating investment. He explains Capru’s approach to removing traditional uncertainties around timing and returns by structuring development exposure into regular income streams. Central to this is a disciplined risk framework, focused on site selection, price discovery, and short-duration ‘build-to-sell’ projects. Michael highlights how this model creates natural cash flow and liquidity, enabling consistent income delivery to investors. His key message is that with the right structure and risk management, property development can offer both stability and attractive upside.
Disclaimer
- The presentations made during this seminar are for informational and promotional purposes only.
- Any comments made or information provided does not consider the appropriateness for you having regard to your particular objectives, personal/financial situation and needs. Before investing you should consider independent professional financial advice.
- No comments made or information provided constitutes advice, an invitation, or an offer to buy any security or other financial product or engage in any investment activity.
- All securities and financial products involve risks.
- Past performance of any product is not a reliable indication of future performance.
- Read carefully the governing documents of a product’s offering such as its PDS or information memorandum.
- InvestmentMarkets does not vet, endorse or recommend any product the subject of the presentations and is only facilitating the exposure of the product.
- These presentations were made as at March 2026, and therefore relevant facts, the economic environment , governing documentation and the law upon which they were based may change after that date such that the accuracy and reliability of their content may be affected.
Featuring
More Videos