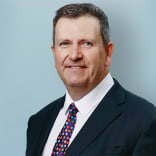
Our last presenter is Brian Parker, Chief Economist at Australian Retirement Trust, ART.
Brian joined ART in June 2015.
Prior to joining, Brian worked in a series of economics, asset allocation, and communications roles with a range of firms, including Rothschild, JP Morgan, Citigroup, MLC, and the Reserve Bank of Australia, in a career spanning more than 30 years.
Today, he will be giving us an economic outlook, global, national and local.
Hi Brian, great to see you again since we last chatted a few months ago.
Welcome to the presentation.
Thanks very much for having me on.
Well firstly, thank you everybody in advance for listening.
I just want to start off by saying just to keep my compliance team happy that this is general information only, doesn't take into account your particular circumstances,
The only people who can really do that are you and your appropriate financial advisors.
So please bear with me.
Now, let me just start by summarising the main messages, or at least the state of the world as we see it.
We've started 2025 with the global economy looking at least in reasonable shape.
For a year in 24, where the economy probably held up better than a lot of forecasters might have expected, 25 is expecting the latest forecast, at least from the consensus, for growth to slow down a little bit, but certainly not to be terribly dire.
The problem with that very benign consensus is that it's certainly around smack bang into the middle of a trade war and some very, very aggressive moves by the new Trump administration on the trade side of things, not just with Mexico and Canada and Europe and China, but indeed increasingly with the whole world.
And that does pose a fairly, fairly significant threat to an otherwise benign set of consensus forecasts for the year ahead.
More about that in a minute.
Now what about here in Australia?
Well here in Australia we've been growing but really only barely.
We've actually seen Australia's economy grow at a very, very modest rate underpinned by very, very rapid population growth and that's certainly boosted demand in the economy.
It's also eased a lot of the labour force pressures that we saw coming out of COVID, but it's also created its own stresses, and that is in particular in the housing market.
If you look at the economy in a more underlying sense, until very recently, measures of things like GDP per capita and real income and real spending per capita were actually falling, and falling at some of the sharpest rates we've seen in many, many years.
We think that over the year ahead, you will see an improvement in the economy, but we certainly don't expect the Australian economy to be racing away anytime soon.
Now, on the inflation side of things, we've seen very significant progress in bringing inflation rates down both here in Australia and globally.
And that's certainly allowed the world's major central banks to start cutting interest rates.
And we've seen a whole range of interest rate cuts over the past year or so.
This year, the Reserve Bank of Australia joined the party with an initial rate cut,
Now, normally when the Reserve Bank starts cutting interest rates, you know, interest rate cuts are kind of like cockroaches.
There's never one.
There's always a family.
But this time around, we may only be in for one or two.
And if anything, there may be some months before we see another one.
And a large part of the reason for that is the fact that the labour market here in Australia still remains very tight.
The economy is continuing to do OK. And if I'm the Reserve Bank and I want to cut interest rates further,
I need to be convinced that the labour market is not going to tighten a lot further.
And we've certainly seen that labour market tighten up again in recent months.
Now on the geopolitics side of things and global politics more generally, I've been doing this job for over 30 years and you always had to keep a weather eye on geopolitics and what politicians globally were up to, but they weren't really the main game.
What central banks were doing and what was happening in the broader economy, what was happening with technology and things like that.
were far more important than the state of world politics.
That's seen a significant shift in the last little while.
Geopolitics has become front and centre.
And we think that over time, the geopolitical uncertainty the world is facing is going to have real world economic implications.
It's going to have real world investment implications.
It's a theme I'll return to.
Now that sort of sums up our view of the state of the world right now.
Let's just have a look at this in some pictures.
Now, this is the latest forecast for 2025 from Oxford Economics to do some of the best detailed modelling of the global economy that we have access to.
And what it shows you is that, yes, you can see that in 2024, most of the major economies of the world still managed to grow, albeit at a fairly unspectacular pace in some cases.
We think the overall economy does slow down a bit this year.
led by a slowdown in China and the United States, you'll probably see marginally better growth in Europe and Japan and better growth here in Australia.
But overall, it's a global economy that, you know, at first cut at 2025, it looks like a year of fairly ordinary below trend growth.
But as I said in the introduction, there's a lot of risks around that otherwise benign forecasts.
On the inflation side of things, you've certainly seen inflation fall substantially.
after rising to multi-decade highs in the aftermath of COVID, you've seen core or underlying inflation rates come back down dramatically across much of the world.
And indeed here in Australia, and I think this is, to me, this is an interesting theme.
If you just think about it, anyone on the call, I want you to think back over the course of your life and try and identify how old were you when you first became aware of money or the cost of stuff?
It might've been when you had your first job at Woolies or Maccas or something, or when you got a few dollars under the pillow when you lost your first tooth, I don't know.
But whenever that date was, if that date was any time after about 1992, 93, in that case, when it comes to inflation, this is your first rodeo.
You've had 30 years of very low inflation or generally very benign inflation.
And this is the first time in your, I'll say economic life,
where you've had to experience a broad-based surge in inflation across goods and services.
And it certainly has been a huge change in people's perceptions of the economy and perceptions of their own living standards.
And it certainly had implications in the last US election.
And it will probably also feature quite heavily in the forthcoming Australian election.
So after 30 years of very low inflation, this has been a massive, massive shock.
Now, let me also just highlight the labour market story that I started with.
Why the Reserve Bank may be a bit more reluctant to be cutting rates a lot further, and indeed also why the US Federal Reserve may be a bit more reluctant to cut rates a lot further.
This is a really nice summary measure of the labour market and how the labour market is faring.
This is the number of job vacancies per person looking for work.
So in the case of the United States on the left, as we came out of COVID, there were two jobs going for every American looking for work.
That's an extraordinary number.
Okay.
Here in Australia, it got up to close to one for one.
Now, in both cases, you've seen the line come down, but that fall is kind of stalled in the last little while.
And it's stalled at a fairly high level.
And it's a key indicator that labour markets in both countries still remain reasonably tight.
Another way of saying the same thing effectively is by looking at some of the more detailed labour force data here in Australia.
And this is based on data that was released just a few hours ago here in Australia for February.
So in particular, I want you to look at the orange line on the left.
This is the labour force underutilisation rate, which is a mouthful, but it basically means it's what percentage of the labour force is either unemployed or underemployed.
In other words, they're working part-time, they want more hours and they can't get them.
Now, what we saw coming out of COVID is this very broad measure of the amount of slack in the labour market tightened up massively.
It fell to pretty much a record low, we're very close to it.
Now, we also saw that start to ease over the past year or so until recently.
The more recent data has this heading in the wrong direction for the reserve bank, I should say.
This is not what the Reserve Bank wants to see if they're about to embark on a series of interest rate cuts.
And the reason it's a problem for them is the blue line, because there's a reasonably nice inverse relationship between the rate of growth in wages and labour costs and this underutilisation rate.
And the Reserve Bank doesn't really want to see wages accelerate dramatically anytime soon.
The chart on the right is another measure of the health of the labour market and it's still historically reasonably high.
This is the percentage of the overall population that is employed full time.
And it's a really nice broad measure of the underlying strength of the labour market.
It did shoot up to very close to record highs in the aftermath of COVID.
It started to fall.
But unfortunately, over the last little while, it started to rise again.
Again, it's another sign the labour market started to tighten up.
That last little dip down is just literally one month's data.
Nevertheless, both the level of that chart, but also that key orange line on the left, those are particularly problematic data points for the Reserve Bank.
Another problem, and this is especially the case in the United States where we have the best data on this.
You hear from the central banks quite a lot when they talk about the outlook for inflation,
They often use a phrase about long-term inflation expectations being well anchored.
In other words, the risk of inflation, or at least the risk of higher inflation becoming a self-fulfilling prophecy is quite low.
In other words, a lot of the consumer surveys in the last few years have basically said, yeah, inflation has surged, but we don't expect it to last.
We expect inflation will return to normal at some point.
And unfortunately, while that's been very true until recently, now maybe not so much.
And what it does suggest is that even though President Trump is trying to say that the Chinese and the Mexicans pay the tariffs, Americans know better.
This is results from the University of Michigan Consumer Sentiment Survey, where they ask Americans, what do you think inflation is going to be over the next year?
That's the blue line.
And more crucially, what do you think inflation is going to be over the next five to 10 years?
Now, both of these lines have shot up, but that crucial long term number is now risen to its highest level since February 1993.
Once again, this is a very problematic data point.
If you are a central banker who still wants to argue that long term inflation expectations are well anchored because they are looking anything but at this point.
a major problem.
Now again, I work for a superannuation fund.
We look after about $340 odd billion of other people's money.
And because of the nature of the investments we make, while we do pay attention to what's happening in the economy and in markets in the short term,
We're not in the business of trying to forecast the short term direction of markets or indeed of the economy.
Superannuation is the longest term investment any of us are ever going to have.
And so we need to keep focused on the long term outlook for returns.
And in doing that, we're much more interested in the sort of longer term trends that the world is going to be facing.
And let me share some of these with you.
Because as I said, this is not just an intellectual exercise.
It has implications for investment returns, but also for the volatility of markets.
We are in a less globalised world.
We are in a more volatile world.
We're in a less connected world in a trade sense.
We are seeing massive disruption to global trade.
not just because of President Trump's policies.
This has been happening for a while now.
We're seeing massive shifts in global investment flows, massive shifts in foreign direct investment spending, disruption to global supply chains.
Because of geopolitics, but also because of climate-related disruptions, we're likely to see more volatile economic conditions and more volatile inflation rates.
I think that's the reality of the world we're in.
We also think that because of the geopolitical environment, because of the rise and rise of populism in global politics, we think that this is an environment where government spending is going to be significantly higher for longer than perhaps we might have previously thought, especially when you think about defence spending.
And especially in Europe, many countries in Europe have basically been, and this is one thing that President Trump has been right about for the last decade or more,
And that is that a lot of European countries, when it comes to their own defence, have been free riding off the US taxpayer for 70 odd years.
That is now changing quite dramatically and rapidly.
What all this means is that government deficits are going to be higher.
It means there's probably going to be upward pressure on inflation.
And you're not going to see, I don't think there's any political appetite virtually anywhere to do anything serious about government deficits.
Now these are primarily inflation forces.
This is going to continue to put upward pressure on inflation.
Now we don't think this means we're going back to the 1970s in an inflation sense.
We don't believe that at all.
What we do think, however, is that if you think about the decade leading up to COVID, there was a decade where the fight the central banks were waging was to actually get inflation up.
Inflation was consistently below their target.
Now, why would that be a problem?
It's a problem because it means you've got an economy which is unnecessarily weak.
You could have actually put more people to work and actually driven inflation a little higher and still met your target.
But they didn't do that.
That's not their fault per se, you know, hindsight is 20-20, but that was the world we're in.
The next decade, starting right now, is basically a period where we're back to central banking 101, where the fight will be to keep inflation under control.
We need to get used to somewhat higher inflation is the point.
Reason why we don't think this is a back to the 70s story,
technology, artificial intelligence in particular.
This is massive.
We don't know the quality of the impact.
We don't know how it is all going to pan out.
There's massive potential benefits from the rise and rise of artificial intelligence.
And those benefits are not just going to accrue to a small number of very big companies.
Those benefits could be very, very widely dispersed.
There's plenty of scope for a whole range of actors
to do both good and potentially bad things with artificial intelligence.
So we don't know how this is going to pan out.
But what we do know is that that kind of innovation tends to be highly deflationary.
So it'll certainly help keep a lid on inflation trends that are arising from somewhere else.
Let me explain these in a few more pictures, then I'm happy to take questions.
Firstly, this is the rise and rise of world trade.
This is the globalisation story.
Globalisation was a massive, massive disinflationary force, especially when China entered the global trading system.
This is world goods trade as a percentage of world GDP.
It was rising for 40 years and then it didn't.
around the mid 2000s, that kind of stabilised.
Now does it go into wholesale reversal?
We don't think it goes into wholesale reversal, but we do think you're going to see very, very significant shifts in global trading patterns.
More about that very, very shortly.
Other issue is tariffs.
Now this is some data from the Peterson Institute for International Economics.
This is the average rate of tariffs in the United States on US imports.
And it goes back to the late 1800s.
And what it shows you is you've seen this long, long, long term decline in tariffs in the United States.
That dotted line at the end, that is what the typical tariff rate will rise to based solely on what President Trump has imposed on China, Mexico and Canada.
It does not include what has been imposed more recently on other countries and what is still to come.
So even based on those three economies, this still takes US tariffs to the highest level since World War II.
This is a major potential disruption to the global economy.
We don't have a good handle on how this pans out.
What we do know though, is that rising tariffs basically is inflationary, but it's also bad for global growth.
It's stagflationary, if you like.
Just how far this goes, we really don't have any idea.
What we do know, though, is that Trump means what he says when he wants to use tariffs as a tool of basically reconfiguring global trade and trying to boost US economic growth.
Unfortunately, he's boosting that growth at the expense of friends and allies.
Trade.
Who is in the president's sights?
I thought this was worth showing.
This just, President Trump thinks about trade in a very transactional sense.
Who do I run a deficit with?
Who do I run a surplus with?
And his perception is that if I'm running a deficit with a country, it means they're somehow winning and I'm losing.
Now that's not really how trade works, but if that's his perception, let's look at the data.
Which countries have the biggest trade deficits?
Well, the US has the biggest trade deficits with them.
China, the EU, Mexico, and others.
It's pretty easy to see that countries like Vietnam and Taiwan and even Japan potentially could also come into President Trump's sights for further direct tariff action.
The chart below that shows you what is the change
in that trade balance over the course of the last nearly a decade or so.
And you can see that while China's deficit has actually shrunk, so the US actually has shrunk its percentage of the imports it uses from China.
But so hence, the US now has a smaller trade deficit with China.
But its trade deficit with the EU, Mexico, Vietnam, Taiwan, Canada, Korea, among others, has risen over the past decade or so.
You'll notice that the top right-hand chart, at the very, very, very, very, very far end, we run a very, very tiny surplus with the United States.
That doesn't help us, however.
Tariffs are gonna be used in a very, very widespread and rather indiscriminate kind of a way.
I talked about foreign direct investment flows, and I thought these charts were interesting.
This is, so foreign direct investment, just as by definition basically buys a large stake in a listed company or sets up a new business directly in a foreign country or buys a piece of property or buys a factory or whatever.
They are making a foreign direct investment.
This is net flows of foreign direct investment into a range of countries.
On the left, China and India.
Now there's two observations from this chart.
Firstly,
ever since China opened up to world trade in the early 2000s, you could pretty much reliably think, you know, China's probably going to attract about $200 billion every year in foreign direct investment.
That has actually dried up to virtually nothing in the last couple of years.
Two reasons, one is geopolitics.
The other is that China is not quite the low cost export source it used to be.
It's not quite the low-cost production facility it used to be, okay?
Its competitive edge has waned a bit somewhat, okay?
Notice the blue bars on the left, that is the amount of money going into India.
India is often touted as a winner from the current disruption we're seeing in global trade and in geopolitics.
And I think over the longer term, that is probably true, that we're not seeing it in foreign direct investment flows just yet.
You know, if anything, India is a country of a bigger population now than China.
And it attracts, historically, it's only attracted a fraction of China's flows.
And even now, it's still only attracting about 30 odd billion dollars a year in flows, which is quite extraordinarily low for an economy of their size.
We think that picks up over the coming five or 10 years, but it may be a slow burn.
The other story on this chart is on the right.
Foreign direct investment into the US and the UK.
The UK used to rely on somewhere around call it 50 to 75 billion dollars in net flows every year coming in to the UK economy.
The last few years that's actually gone into reverse.
The money is leaving the UK.
One word, Brexit.
The greatest act of economic self abuse in human history.
But look at the United States.
And I think this is important, especially when you look at US politics.
Now, US politics has been a source of uncertainty and volatility and has not been in great shape, frankly, for quite some years.
But we need to distinguish between the US as a political system and the US as an economy, as an investment destination.
It is still the largest, most dynamic and most innovative economy on the planet.
And so it is still, you can't say the United States is not investable because of the politics.
In fact, that has been the judgment of investors for the last decade or more.
The US still manages to attract about $300 billion a year in flows, despite its politics, not because of it, but certainly despite its politics.
And I think that probably continues.
The other story is another big winner out of this geopolitical shift, if you like, is Vietnam.
And what I've done, just to provide a bit of perspective here, this is foreign direct investment going into India, same as the previous chart,
And foreign events have been going into Vietnam.
We're talking about a country, in the case of Vietnam, of about 95 million people versus a country of about one and a half billion people.
And yet the Vietnamese attract nearly as much money in foreign direct investment flows as India does, which is quite extraordinary.
The Vietnam has proven itself to be a very dynamic economy, very investment friendly, very highly efficient workforce, very strong education system.
And it's certainly been a beneficiary as money has stalled going into China
Vietnam has been a winner and has attracted more than its fair share of those flows.
To what extent is that basically people pulling a bit of a swifty and trying to get around US tariffs on China by setting up production facilities in Vietnam, but also places like Mexico.
That has certainly been part of the story.
I think President Trump is now aware of that.
And so hence, I don't think there's gonna be anywhere to hide in the short term from the shift in tariffs we've seen in the United States.
The other story which I touched on was military spending.
As I said, Europe has been kind of free riding off the US taxpayer for a long time.
President Trump was right about that.
What I'm showing here is military spending as a share of GDP in a whole range of economies.
And more crucially, the bottom panel shows you the change in that military spending compared to the decade leading up to Russia's invasion of Crimea.
What I'm trying to illustrate is what the question I'm trying to answer is, which countries
in the wake of Crimea woke up, and which countries did not.
The countries that woke up are in orange, and they're no surprise.
They're those countries with serious history and geography with Russia.
It's the Poles, it's the Estonians, it's the Lithuanians, the Latvians, the Hungarians, the Danes, the Finns.
It is no surprise.
These countries, their perception of Russia has broadly been right, whereas the Germans and others have been dead wrong.
The Germans are now waking up to that fact and so you're seeing a major, major shift in the military spending posture of Germany as we speak.
Let me just start and finish off by just talking a little bit about positioning and how we're seeing markets right now.
We are not seeing markets as being massively cheap or massively expensive.
And as a result, we're not taking big active positions in the portfolios we manage.
We are certainly taking advantage of volatility.
We've certainly seen a fair bit of that.
and we expect that volatility to continue.
Volatility provides opportunity.
We all, because we're not taking big positions, we've certainly got the scope to, we've certainly got dry powder at our disposal.
Any major share market weakness over the coming months is likely to present a buying opportunity and vice versa.
A massive rally in share markets may be an opportunity to lighten up and we have the risk budget at our disposal.
In a country sense, where do we like?
If I look at a global portfolio of equities, we would prefer to be overweight Japan, modestly overweight the UK and underweight the United States and Australia.
We just think the relative value story still does not quite favour the United States or Australia, but it still certainly favours Japan, where we're seeing a lot of the reform measures that have been introduced in the past decade
really starting to bear fruit in terms of Japan's corporate performance.
And in fixed income, we're still fairly cautious on German government bonds, but we're finally starting to see some value come back.
You can actually now buy a diversified portfolio of investment grade bonds, hold it to maturity, and you might actually get a positive real return.
which would be a major change from where we were three or four years ago.
And that is good news, especially for investors who are at a later stage of life, who are moving into a more conservative investment strategy.
I'd much rather make that shift today than three or four or five years ago.
Let me just finish by talking about future long-term returns.
This is basically returns from the major asset classes we invest in over the past decade or the decade leading up to the end of June last year.
And I chose that because that's the time we do our annual review of strategic asset allocation.
And as part of that review, we need to create some kind of assessment of what sort of investment returns are achievable and sustainable over time.
And what this shows you is that the last decade was actually a phenomenal time to be an investor.
It was an era where a rising tide lifted all boats.
We don't think the next decade looks like that.
It is going to be a more uncertain and a more challenging time.
But we still think there's returns to be had.
This is our current estimate of 10-year returns for these major asset classes.
Several observations I want to make and then I'll close.
Firstly, will I still get an equity risk premium?
Will I still get compensated for taking equity risk?
Yes, I will.
I just won't get as much compensation as I did for the past decade.
We think equity returns are going to be lower.
Now, I hope I'm wrong on that because frankly, investing is like life in general.
I'd much rather be pleasantly surprised and bitterly disappointed.
So let's be realistic about what equities can deliver from here.
Secondly, will I get a premium if I'm prepared to give up liquidity?
So in other words, Australia's major super funds have long invested significant amounts in things like infrastructure and private equity and direct real estate.
Will those asset classes offer me a premium for the fact that they're not liquid?
We think the answer is yes.
But also, and it goes back to my point before, this is the future returns for cash and bonds.
And thankfully, the silver lining to the cloud, which was the last few years bond returns, is because yields have risen, I can buy a diversified bond portfolio and I'll actually get a respectable return.
It also means that bonds might have a decent chance, at least in some scenarios, of doing what bonds are meant to do, namely protect capital and pay me an income if equity markets go through a crap period.
I think there's a much better chance of that happening now than there was perhaps four or five years ago.
I want to thank you again for the opportunity.
I really, really appreciated your time and look forward to taking your questions.
Thank you, Brian, for the presentation.
Very informative and insightful indeed.
And to your point, it's not just intellectual practice or exercise.
It's relevant to all the crucial investments, especially aiming for the long term.
So we have some questions for you.
First one is, nominal Australian economic growth continues to run below train, which you mentioned in your presentation.
So the GDP per capita,
has been negative for almost two years.
So do you expect this local economic weakness to continue?
And if not, what's likely to drive an economic recovery from here?
Okay, I think we do see an improvement.
I think we've already seen some sign of an improvement of those per capita measures.
I think that does continue and it really comes from two directions.
I think you will see a bit more of a slowdown in population growth because I think that massive surge in migration after we reopen borders will start to wane somewhat.
I also think the impact of some easing in interest rate pressure
The tax changes late last year are certainly boosting or provide a bit of a boost to disposable income.
So I think you'll see consumers start to improve their situation a little bit.
You've certainly seen confidence pick up amongst consumers, which is pleasing.
But also there's things happening on the investment side that will probably prop up growth as well.
So there's still a very large pipeline of infrastructure spending, for example, in things like energy resources, which is pretty common, but also in the energy, the electricity space, there's still a lot of projects underway, a lot of work yet to be done on projects in electricity generation and transmission.
And that's, these sort of projects are going to keep on supporting growth for the next few years.
So I don't think growth races away, but I think the Australian economy continues to chug along.
We're not quite as exposed to the threat of tariffs as other countries.
Our trade with the United States is actually relatively limited.
So it's not a killer punch for our economy, at least the direct impact.
But there are other risks to Australia from those trade tensions.
Most notably, if it has a massive impact on China, that's going to have a more serious implication for us.
But I'm cautiously optimistic, if I can put it that way, that the Australian economy will pick up a little bit over the coming year.
And do you believe the RBA are in control of local inflation at this junction?
We seem to have lacked most developed markets in return inflation to target here in Australia.
In your opinion, why?
There's a few reasons for that, I think.
I think the Reserve Bank was more willing to not clamp down on inflation as fast as others because they saw how much progress had been made
in bringing unemployment down and in boosting living standards through higher wage outcomes.
And I don't think they wanted to blow that.
I think they were prepared to trade a bit more carefully and not raise rates as far as some other markets, some other economies, because they thought, can we maybe bring inflation down a bit slower and preserve those gains we made in the labour market?
Now, so far,
And I know they've copped a lot of grief about this, but we still have a very solid labour market and we've seen inflation come down.
Now, will that continue?
I suspect the answer is yes, but I do worry about that state of the labour market.
Unless we see some further weakness in labour market activities and further softening, there's every chance the Reserve Bank might end up just saying, no, I can't cut rates any further.
I don't think they'll raise them again anytime soon, but there's a genuine risk this time around that they're one and done.
I hope that's not the case because I have a variable rate mortgage, so I would really love another rate cut.
But so far, I think things are playing out reasonably well for them, but there are risks out there.
I'm curious about the government's cost of living measures.
So will that make a dent in the inflation rate?
It sort of has already to some extent, but especially on things like power bills.
So you saw, well, effectively, you saw some artificially low inflation readings in the back half of last year.
And I think the political calculation was reasonably clever.
Demonstrate that, yes, you've done something about it.
You've helped actually allow people to actually pay their bills more easily.
but also you brought down measured inflation, I think the hope might've been that, okay, if that washes out of the system, maybe before that happens, there'll be enough other disinflationary pressure coming through to sort of sustain that progress in bringing inflation down.
That's still a very uncertain path,
but I think there's some chance it might come off.
So I think they were fairly careful and cautious in how they did those cost of living measures.
They certainly took some pressure off.
I think you have seen that in the consumer confidence numbers and to some extent in the spending numbers.
And I don't believe that the magnitude of the spending has really boosted the economy too dramatically.
I don't think they've made the Reserve Bank's job massively harder or anything like that.
It was, but certainly the,
the political need to be seen to be doing something about cost of living pressures I think was very real.
You touched on this a few times and it seems counterintuitive that we have higher interest rates for some time now but the Australian unemployment remains relatively low at 4.1% let's say.
So why has employment been so resilient to date and do you expect this resilience to continue looking forward?
That's a good question.
And to me, what it shows is that, and you certainly saw this in the US data as well, is that you had a labour force, a labour market that was so overheated.
And there was, you know, businesses really running up against capacity constraints.
By raising interest rates, if you've managed to ease demand, and just take some of the steam out,
taking some of the steam out can be done in theory without doing much in the way of economic damage at all.
And so for example, in the United States, again, the damage to the labour market from their interest rate increases hasn't been all that great.
They're still generating jobs and unemployment is still reasonably low.
It's been a similar story here.
And so I think what the central banks have been able to do thus far is literally just take the steam out of things without actually inflicting economic damage.
Now,
If they had kept on raising interest rates, then all bets might have been off.
We could have been staring down the barrel of five or five and a half percent unemployment, but we're not.
They raise rates, they pause what seems to be about the right time, inflation's come down and the labour market, they've been able to pretty much sustain those labour market gains.
Whether that continues is an open question.
I suspect the Australian labour market does soften from here.
I do think you'll see a modest increase in the unemployment rate over the coming year.
I don't think it's going to be dire, but I think that steam will continue to come out of the labour market.
But trying to finesse these things is extraordinarily challenging for policymakers, and it's going to remain very challenging.
Yeah, it is indeed.
So when do you believe the RBA will be confident their 2.5% headline inflation target is achievable?
That is the multi-trillion dollar question, really.
I suspect they're going to, I think that if there's another rate cut, it's probably not for a few months.
I think they'll need to see at least another set of major inflation figures, not just the monthly figures, they'll want to see a quarterly result.
And they'll also want to see signs of the labour market softening so that they can be confident that wages won't re-accelerate.
Because if wages re-accelerate, especially when productivity growth has been relatively modest to non-existent,
The risk of that higher wages growth feeds through into more underlying inflation is very real, and it certainly seems to be keeping them awake at night.
I don't think we're going to get enough evidence to support another rate hike.
I don't see it before May.
I think it's more likely going to be second half of the year.
But to be very frank with you, even internally, there's a reasonable amount of debate about that, even though it doesn't massively impact the way we manage money.
It's almost like the interest is more sporting rather than investment related.
It will happen, but not for a while.
Potentially not for a while.
That's right.
And how many more rate cuts do you expect from the RBA in this rate cutting cycle?
To me, maybe one or two, and that's about it.
I don't think the economy is going to be so weak as to justify moving policy to a genuinely easy position.
I think it's going to be a case of taking the foot off the brake rather than hitting the accelerator.
That said, it's still a very uncertain outlook.
The global economy is a very uncertain place right now.
There's a lot that can go wrong.
We don't know, for example, what impact on business psychology and business sentiment and investment decisions the trade war that we're seeing is going to have and how all that's going to play out.
Does it mean that businesses go on a bit of an investment strike?
I don't think so.
because there's a lot of investment activity happening, especially in the technology space, especially in the infrastructure space, which is not really dependent on trade or on interest rates.
It's more structural, it's more driven by technology and efficiency and climate change.
There's a lot of money in the electricity space that needs to be spent as we reconfigure the global energy system.
And that reconfiguration is continuing
even under the new US administration, which is perhaps not as supportive as the previous one was.
Now, I can't believe we're in March 2025.
So what's your opinion on the outlook for local and global investment markets for the rest of this year?
Equity or bonds, which are more likely to outperform and why?
Now, okay, you know, if I absolutely knew the answer to that question, would I be on this call?
I know, I can tell you where I'd be.
I'd be in my farmhouse in Tuscany, drinking my own body weight in Chianti, which is a lot of Chianti.
Yes, you're welcome.
In my farmhouse, it'll be big.
There'll be plenty of places to stay.
Sounds good.
And it has to be near a really cracking winery.
Look, I think we're in for more volatility, the risk of stating the bleeding obvious.
I know that's a very economist answer.
I just think it's going to be very volatile and uncertain.
Yeah, no crap.
Really?
I look, if you're a betting person, I say the coming months for equities is going to be very challenging.
But those challenges do provide opportunities.
You know, does it pay to be a long term bear on equities because of the state of the world right now?
I think the answer that's no.
Every period of market volatility, every market downturn, every crash comes to an end, bar none.
And whatever the world's going through right now will be no different.
I do think you'll see it just in terms of how we're positioned.
And there's no time horizon on this.
But the fact that we're just a little bit underweight equities and a little bit overweight bonds is probably our best guide to how we're positioned, really.
We still think that relative value favours non-US markets, especially Japan, where there's a good structural reform story underpinning that performance as well.
We think there's more juice to squeeze out of that orange.
But, you know, the valuation on US equities is still a bit challenging.
But I'm also acutely aware
that investment decisions in the US based on valuation have not been terribly successful for some years now.
But I do think we're in for more volatility, put it that way.
Another question similar to that, but from a different angle is, do you believe Australian investors should be overweight or underweight, the local market?
Yeah, it's a good question.
There's two angles for me.
And it also depends on who you are and what your investment needs are.
You know, I'm also I'm acutely aware of the attraction for Australian investors to fully frank dividends.
And that's certainly been a nice source of reasonably secure income for a range of investors.
But I'm also conscious that Australia is a very tiny part of the world.
that we are a share market that is dominated by really a handful of big banks and a handful of big miners.
It's not terribly exciting in that sense.
And so I just think from a diversification point of view, yes, by all means, you know, appreciate the Frank dividend argument, but at the same time, it's a big wide world out there with some very exciting companies doing very exciting things.
So I just think that I want to be, and yes, I'm absolutely talking my book,
I do want to be more diversified because as I said, I want the broadest, when you're looking at, when you're a fund of our size, you know, we need the broadest opportunity set we can find, not just here in Australia, but globally.
And that diversification argument, I think remains a pretty, a pretty favourable one.
There's a fair bit of evidence to suggest that yes, while dividends are attractive, it's about the return and it's about the growth opportunities and it's about the diversification as well.
So,
I'd also caution against being overly focused or mesmerized by the frank dividends, because you potentially miss out on global opportunities.
But at the same time, you know, the best portfolio for every individual person is a portfolio that they have worked out themselves, preferably with the health of professional financial advice that suits their needs, their stage of life, their appetite for risk.
There's no substitute for that.
Anything else is a very imperfect substitute.
Yeah, indeed.
And talking about diversification, ART has a strong presence in the private markets.
Can you talk us through the investment rationale behind this?
Yeah, there's a few, there's several.
Firstly, we get access to a much broader range of opportunities that you don't get if you just limit yourself to what you can buy on stock markets.
And so that's one.
Secondly, because these assets are private and unlisted,
I can't get on the phone and sell our stake in Heathrow Airport tomorrow.
And because of that, that lack of liquidity, I need to be compensated for that through a return premium.
And the history shows that you do get that return premium.
So if I can get a return premium and in the process, get access to opportunities I wouldn't normally get by limiting myself to the share market.
And also because these assets are not valued every minute of the day,
It means our members are not going to be exposed, at least not going to be as exposed to the lunatics around stock markets on a daily basis.
If we can deliver higher returns with a smoother ride and get a really broad opportunity set, that's a really nice proposition for us.
And so we run portfolios where typically about 30% of the fund give or take is invested in things like, is basically invested in the broad private asset space.
So this is infrastructure, private equity,
real estate and a little bit of private credit.
And we just think there's nice return premiums to be gathered.
We just need to be acutely sensitive to liquidity.
So why don't we have more than 30?
And the reason is we need to pay pensions.
We need to have cash on hand.
We need to make sure that if our members want to switch from equities into cash, that we can do that for them.
So 30% for us is about the right number.
For some funds with different demographics, it's smaller.
Some can afford to carry a higher level
But one of the things I would say is that this private asset space tends to be quite unnecessarily controversial in some sectors.
And the reason I say it's unnecessarily controversial is that I look at what the Australian super funds have been doing, and we've not really been doing anything different to what the big Canadian and American funds have long been doing.
The big university endowment funds and the major global sovereign wealth funds all have significant exposure to these private assets for the same reasons we do.
Nice diversification, return premium and a smoother ride.
Yeah, potentially less volatile and with a nice premium.
Love a premium.
We all do.
Are there any economic outlook scenarios, either locally or globally, that the broader investment community generally believes are very unlikely or not widely agreed upon?
But you personally feel they deserve more serious attention and consideration.
Oh, look, there's a few.
Firstly, and I don't want to, I don't want to frighten the horses terribly much, but I still think there is a reasonable amount of complacency about the geopolitical environment.
And the risk of serious geopolitical disruption in various parts of the world, including in our own region, that risk is very real.
How it plays out, we do not know.
But it certainly, and our best defence against not knowing how any of that plays out.
is to be as broadly diversified as humanly possible, which we are.
The other, I suppose, on a more optimistic slant, and I've touched on this already, I think people, because of so many years of being disappointed with Japan, maybe people aren't paying quite enough attention to the fact that Japan is actually becoming a much more interesting and dynamic place.
And these companies at their best are highly innovative, highly efficient, and they're getting better.
So I would say don't underestimate Japan.
And also, if I think about the geopolitical environment, I think I hope people are prepared to be more patient with India.
India is a slower burn.
It's a much more inefficient place to do business.
But in terms of long term growth prospects, the potential for massive productivity catch up, as well as much more favourable demographics than you see in countries like China or Korea or elsewhere.
You know, it'll be potentially very exciting to see how India plays out over the coming decade and beyond.
Interesting.
So how can Australian investors best position themselves to benefit from your expected economic outlook?
In your opinion, of course, not giving any advice, which markets are to overweight and underweight.
The easiest way to do that is to become a member of Australian Retirement Trust and you benefit from our investment expertise.
You knew I was going to say that, didn't you?
But I think the best way to do it is to make sure that when you're thinking about asset allocation, that you're as diversified as possible.
That you're actually, you know, looking seriously to overseas exposure and being willing to actually, you know, maybe look at the home bias that Australian investors typically have and question, does that actually really make sense?
Are we really that in love with our frank dividends?
Because the Australian market is not tended to be a star.
for quite some time and it's a relatively dull market.
I just think there's potentially more exciting opportunities if you look at the international scene and be prepared to sort of venture beyond our borders.
Yes, I know everyone talks about the risk of, you know, currency risk, et cetera, but you can hedge that and you can have a combination of hedged and unhedged.
There's plenty of vehicles out there on markets, whether it's ETFs or funds or both.
that can provide you that opportunity.
You certainly get that opportunity through our superannuation funds.
I'd also encourage people to take an interest in how their super is invested.
I mean, the lion's share of our members end up in the defaults because they don't take an active interest.
I'd really, really encourage people.
And I'm thinking the audience to this call is going to be more engaged simply because they're on this call.
And I congratulate them in advance for actually taking an interest in how their money is invested, because so many people don't.
And I think that's really sad.
Yeah, true.
And thank you for saying that.
So, talking about global opportunities, how do you expect US tariffs to impact the global economy and geopolitical risks?
Yeah, that's a good question.
Tariffs, by their very nature, are anti-growth and they boost inflation.
They make the world a less efficient
higher cost place to do business.
And to the extent that the United States has historically based its foreign policy and its foreign policy agenda on working with allies, deliberately snubbing allies and imposing a trade war on them in such a very uncertain geopolitical environment, I just think this potentially
is going to call, and I think we're already seeing signs of this, you potentially see a massive rethink about, in the capitals of the world, who were previously aligned with the United States and saying, is this, you know, are these father and grandfathers Americans or are they different Americans?
Are these Americans that we could have relied on in World War I and World War II and to provide a nuclear umbrella since the Cold War?
To what extent can we rely
on American power to have our back, to what extent can we rely on access to US weapons if we need them?
And I think there's serious questions being asked.
You're certainly getting those questions asked in Europe, and I think they'll be asked elsewhere as well.
So I do wonder whether, despite the clear intention of President Trump to use tariffs as a tool for boosting US manufacturing, they're doing that
I don't think the president thinks in win-win terms.
He thinks in win-lose.
And so consequently, he thinks that if other people are winning, he must be losing.
And that's so there's no, I don't think there's a scenario in his mind that actually has other people winning and the Americans winning.
So he wants to boost the US economy via manufacturing by either encouraging firms to set up in the United States or encouraging firms to stop importing and start buying locally in the United States.
and you are effectively adversely impacting some of your closest and most reliable allies.
And I'm not sure that's an ideal thing to do from a geopolitical standpoint.
The scenario can be way more complex than it is.
It is indeed.
To conclude, can you, Brian, please share an investment or economic lesson you've learned of later in your position as ART's chief economist?
Oh, that's a good one.
Look, I think
Let me go back a bit further.
I've become a much more patient investor than perhaps I was when I was younger.
I'd like to say that's a wisdom of age, but that's a bit of hubris really.
I've certainly become more patient and I've certainly become far more aware of the importance of risk management and of scenario testing and becoming less reliant on forecasting.
I think if there's one other thing I've learned over my career is perhaps one of the best tools an investor can have is actually a vivid imagination.
You know, being able to imagine how the world might play out, both for good and for ill, and how you might think about positioning portfolios or how your current portfolio would fare under a range of different scenarios.
I think that ability to imagine how things might evolve
is perhaps an underappreciated tool.
Yeah, love it.
That's the first time I get an answer or imagination from that question.
Now, thank you, Brian, for your very generous insights and time.
It was truly wonderful to have you here today.
Thanks, Angelina.
I really, really appreciate the opportunity.
All the best, everybody, and happy investing.
Thank you.
See you soon.
The economic outlook: global, national and local
About this presentation
Chief Economist at Australian Retirement Trust, Brian Parker, explains the economic outlook at the moment, from a global, national and local point of view which is followed by a Q+A session with the CEO of InvestmentMarkets, Angelina Wu.
Disclaimer
- The presentations made during this seminar are for informational and promotional purposes only.
- Any comments made or information provided does not consider the appropriateness for you having regard to your particular objectives, personal/financial situation and needs. Before investing you should consider independent professional financial advice.
- No comments made or information provided constitutes advice, an invitation, or an offer to buy any security or other financial product or engage in any investment activity.
- All securities and financial products involve risks.
- Past performance of any product is not a reliable indication of future performance.
- Read carefully the governing documents of a product’s offering such as its PDS or information memorandum.
- InvestmentMarkets does not vet, endorse or recommend any product the subject of the presentations and is only facilitating the exposure of the product.
- These presentations were made as at 25-27 March 2025, and therefore relevant facts, the economic environment , governing documentation and the law upon which they were based may change after that date such that the accuracy and reliability of their content may be affected.
Featuring
Tags
More Videos