Two leading money managers.
Two different strategies.
With thanks to investment markets this is Conviction Capital.
Hello and welcome to Conviction Capital, I'm your host Juliette Saly.
Well income is a major priority for investors right now, but where should you be looking for it?
From fixed income and private credit through to dividend paying Australian shares, there are very different ways to generate income and very different risks that come with each.
So how do investors assess the trade-off between income, capital growth and risk in today's market?
let's ask our panel.
We are joined today by former CBA CEO and ex-chairman of the Future Fund David Murray and Hamilton 12 Managing Director Richard McDougall.
Great to have you both with me gentlemen.
Let's have a chat first about the pretty dramatic shift that we've been seeing in the interest rate environment.
So when investors talk about income David, what exactly does that mean and how does the change in interest rates really affect that?
Well it means that if they're watching the macro environment they're concerned about protecting their portfolios when they see a major shift, potential rises in interest rates from inflation and a need to basically protect their portfolio a bit more.
by moving from higher risk equity markets into lower risk debt and in that case they'll be concerned about the shape of the income, the risks to that income but I think that is the shift that's going on now and it looks pretty profound so it's something that all investors should be thinking about pretty carefully whether they're
changing the way they look at equities or so making shifts within their equity portfolios or moving their portfolio allocation more to debt and away from equities.
And Richard what's your thoughts particularly amidst the changing interest rate environment?
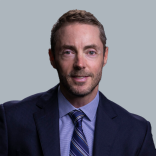
The points I'd add to what David mentioned is, particularly at the moment when we're seeing term deposit rates, I think fluctuating around five and a half percent, it causes pause for investors to have a think about the composition of their portfolios and where they're deriving income from.
And to reinforce David's point, having a real thorough understanding of where that income is sitting in terms of the capital structure, who the investors are actually investing in and what their exposure is from a risk perspective.
Let's talk then about fixed income and credit and what sort of opportunities are you seeing in credit markets at the moment David?
Well the big shift has been towards private credit for returns but I think the opportunities that should be looked for now are a private credit which is less correlated to the normal credit cycle
and more protected in terms of capital and also less correlated to other forms of equity, other forms of credit.
So I think this is a time for questioning whether some of the traditional types of private credit
suitable in this environment or whether people should search out probably less common areas of private credit and see whether they can get that possibility of a higher return with lower traditional risk and how you go about that.
So is that less common area where you're finding the most attractive opportunities?
Well I think so because it depends on your starting position but if your starting position is the world has moved from a disinflationary low interest world to an inflationary high interest world where central banks are going to have a lot of difficulty enforcing their monetary policy outcomes because of high spending by government which isn't going to go away.
then it is time to protect the portfolio.
And moving to fixed income is a very good way of doing that, but people will have to be equally concerned about the type of credit that they're seeking out.
Let's move then Richard to Australian equities.
So where are you seeing opportunity right now?
Look I think the opportunity is broad based across the entire spectrum of the Australian equity market.
I think the underlying message for investors however given the current context is to ensure that there is a focus on quality in terms of balance sheet.
We're obviously facing some headwinds economically for the Australian economic environment.
So having a thorough understanding of how that income is being derived in terms of the underlying company and the quality of that company's balance sheet and its ability to produce consistent stable income streams into the future is the aspect that we would suggest investors consider.
And particularly when they're looking for a sustainable dividend income, what are sort of the best ways to look for that?
Look, we would always advocate for looking at sustainable income from Australian companies that are paying frank dividends.
We're moving into a tax environment that, I mean, we're seeing the biggest shift in the tax environment that we've seen for a quarter of a century.
So having an understanding of how taxes impact income for investors, particularly for Australian equity income investors, we think is a very important aspect that investors should be considering, particularly looking forward over the next couple of years.
One of the big traps as well is simply chasing the highest yield.
Where do investors look beyond the headline yield?
Yeah look, chasing yield is a trap because what it can do is lead to concentration from either a specific stock level exposure or an industry exposure.
So we know from the research actually that equity markets in general are what's termed as positively skewed.
So, what that means is, in fact, when you look at equity markets, it's only a handful of companies that are producing the total returns more so than the broader market or the average of the market.
So, for example, if you look at the S&P 500 or the ASX 200, it's only about the top 20% of companies that actually outperform the broader market.
So, we would always advocate for diversification across an equity strategy because what you're ultimately doing is you are reducing your risk of underperforming or holding those companies that are effectively going to underperform from a total return perspective.
producing income at the expense of total return that's the common trap that investors make so making sure that you're diversified looking for a sustainable income stream that is coming not at the expense of total returns we think is a important aspect that investors need to consider.
David let's get back to credit because investors here effectively being paid to take on risk so what are some of the risks you're watching and how do you assess whether or not you're being properly compensated?
Well in credit
particularly in private credit, the sort of risks that investors have had to learn to manage, the risks associated with performance fees, with a range of less transparent fees, and the higher risk associated with distressed debt and special situations debt,
Private credit that's associated with secured business debt is actually less volatile but the fees structures are high and private credit associated with mortgages is less risky
but we're seeing major changes in the property market so that existing private credit funds focusing on mortgages, in short old books, will have traps and what I would like to see is a newer mortgage fund
where the managers have focused on a new credit policy for today's circumstances and the emerging circumstances with a clean book.
Apart from that, one of the most interesting for me is the traditional trade credit because I once worked in the Commonwealth Bank in the international division doing trade credit and international finance.
And one of the senior executives said to me one day, look, we just want to approve the credit, put forward an application to approve a credit to finance trade to Egypt.
And I thought, Egypt, that's not a very good idea.
And then he gave me a coaching session, which was about
This is wheat.
Wheat makes bread and Egypt doesn't make much wheat.
So it will be paid for.
And then I realised that with trade credit, if you're in essential commodities with well known suppliers and buyers,
the risk of loss is very low.
There are operational risks, improper definition of goods, documentary mistakes, all of those things, but seasoned professionals know how to manage that.
So trade credit has, and it has short duration, which is what we should be looking for now with rising rates.
So trade credit or new mortgages to me have more attraction and in relation to trade credit the risk reward ratio works very much in the investors favour because it turns over quickly.
That's such an interesting story and you've had such a big diverse career.
I'm curious getting to Richard's point about the biggest tax changes we've seen in a quarter of a century.
Is this
something that you know is kind of I guess one of the biggest changes that you've witnessed obviously in 25 years but in your career there has been significant changes to the way people invest.
Very much so.
A lot of that's got to do with sophistication of the markets, of the financial markets and the sheer skills and innovation that have been brought to it, particularly along the spectrum of the securities markets and different types of funds, different types of instruments.
That's all a great thing, because the more diverse the instruments on offer,
to be issued by companies in varying industries with different time frames.
A 20 year mine is very different from a 90 day trade finance for example.
That's a fabulous thing for the development of the system.
But what we've seen now in common with much of the world is a move away from the deregulatory stance of the 80s to heavy regulation, more and more complex tax law and I mean the best example was the recent budget where it was absolutely clear that neither the government nor the Treasury was sufficiently across their own rules and their own tax structures to understand what they were doing.
and have to then undo it.
So this is not a good sign but I agree with the reflection about staple businesses, franking credits in the tax system.
Apart from that people have to organise their own tax.
But even with banks, bank stocks, for example, perform like bonds.
So if the bond market is weak, then banks' prices tend to be weaker.
On the other hand, they can pay out well.
They're well-prudentially supervised in Australia.
Their prices will suffer from the connection with the bond market and with the credit cycle.
Every bank says they've got no bad debts but the truth is they do and when the cycle starts it happens.
But if you want to avoid paying capital gains tax and you're happy to hold and get a frank dividend, that's no bad thing if the banks are well run.
And you remember my own inquiry in 2014 in the financial system, we made sure that the Australian banks from then on had unquestionably strong capital bases.
So there are things you can do but in general and particularly in Australia and particularly with the superannuation funds, moving that allocation away from equity into more credit is probably a smart thing to do.
Do you think there's potentially too much regulation?
See I lived through the deregulatorys.
I studied and understood what was going on in the highly regulated period up until 1982 and then watched how and over what time frame it was deregulated and then with a lag before everybody worked out how to live in a deregulated environment.
just the amazing difference in productivity and performance and we've gone way, way back.
I could make myself extremely unpopular about giving you a very compelling argument why responsible lending laws are wrong and they are wrong.
And so banks have been constrained in their credit.
They're taking much less risk than they used to take.
Is that a good thing or a bad thing?
And I think maybe it's not such a good thing and that's why private credit has stepped in with all of the structures that the securities markets now offer.
You may not want to or be able to answer this but just when you were talking there about the yield relationship with banking stocks as the former CEO of CBA how do you view the valuation of banks like CBA that everybody says is the most overpriced in the world?
Well, I love having a go at some of my old analyst friends about that, because they were telling me that for years.
And so you're telling your clients to sell.
And each time I go back and see them again, I say, how are your clients feeling?
Because it didn't work.
The issue is not the Commonwealth Bank.
The issue is the market.
And if you combine what, if you don't mind me saying so, is an overvalued equity market around the world with Australian frank dividend environment and the sort of payout ratios the banks can afford,
Then you're going to get that result and I'm happy to say the banks been the best performing of the four major banks And those legacies I'm very proud of so part of it is outright performance But the issues are the valuation in the market Combined with the strengths of the value sorry that investors attribute to franking credits
What's your take on the big banks?
Look, I'm not saying it because David's here, but CBA is a very well run bank and they have a very strong management team.
I think their investment in technology early on is what has given them the advantage.
Now whether that justifies today's valuation or not is a different question.
I think when you look at a bank and when its equity yield is potentially lower than its one year term deposit yield, then that might suggest that there's a bit of a dislocation in terms of valuations.
for the banks, but generally for the Australian equity market and global equity markets in general, yes, they are overvalued, but we would say we don't think that's an end or an oar.
An investor should always have a diversified portfolio and how they allocate to each asset class will obviously depend on their individual views and what advice they receive.
And I think one of the reasons, and the current CBA CEO Matt Comyn has said this to us before as well, why so many people want to hold the banks is the dividend yield.
But we know that dividends, they're attractive on paper, they're not guaranteed.
What separates, in your view, a genuinely sustainable dividend from simply a company offering an eye-catching yield?
Well, we would always suggest to look forward.
So investors can quite often make the mistake of looking at a high yield, but that's based on the historical yield relative to today's prices.
So looking at the forward yield, and not just consensus numbers, I mean, we would always suggest looking at individual analysts forecasts around dividend yields and franking levels for all companies.
And in fact, analysts are very good at forecasting dividends and franking percentages.
So, we would always suggest that that's an important element when looking forward on equities.
But in terms of, if you ask the same question around a total return perspective, we would always say that income is purely just one component of the total return and again would reinforce for equity investors, particularly if they are looking at yield, just make sure that's not coming at the expense of total returns.
Because quite often the mistake can be made when you chase yields, you see no growth in the capital component.
And if you've got no growth in relation to inflation, you're effectively going backwards.
I should, maybe I could add to that.
Specifically in the banks, the issue is whether the return on equity that is retained after the payout
is enough to justify the dividend relative to credit growth, which the marker there is nominal GDP.
So if credit growth is hovering around nominal GDP and the retained return on equity is at least equal to that, that dividend can be maintained.
So the credit cycle is one thing that interferes with that and unfortunately by adopting the accounting standards the banks are prevented from provisioning more aggressively in the good part of the cycle which is unfortunate.
And speaking of the cycle does that make you cautious about income investments or does it actually create potentially more opportunities?
No, I think that's what you should be looking at, income investments.
And the reflection about the sustainability of the dividends, where they are in relation to growth, is absolutely correct.
I just like companies where the management and the board are happy to have a dividend.
It sort of signals a slightly more positive view of themselves, doesn't it?
And if they can maintain it, that's even better.
Dividends that chop and change, that's not good.
Richard, how important is capital preservation for an investor really focused on income growth?
Yeah, incredibly important.
Again, going back to the point I just made earlier, as far as equity income is concerned,
In that category in Australia, there's about $20 billion of investors funds in Australian equity income strategies.
It's only a small portion of those funds that are actually allocated to strategies generating high income and total return that's higher than that of the broader market.
So if you think of that context in relation to the tax regime that we're about to walk into,
We would always suggest you want to make sure that you've at least got capital growth that's in line with inflation that will marginally outpace inflation.
So if you think of that from a tax perspective as well, we're moving to an indexation model where really it's only the capital growth over and above the index inflation level that's going to be taxed.
So, if an investor can find an investment strategy that has a capital component that is at least keeping in pace with inflation and above inflation, effectively that's going to come tax free.
But then also look at a strategy that's going to complement that with income and we would always advocate for frank income because effectively that is the most tax effective combination of total return you can receive, provided the investor is prepared to take equity risk.
How much do you think portfolio positioning is going to change in the lead up to those changes?
Yeah we've already started to see some changes around that at the moment and look that's sensible whether that's a good thing for the Australian economy or not that's a different conversation because there is a conversation around capital being allocated to companies that are more interested in paying out dividend as opposed to retaining income for growth.
But you know again it's the first time in a quarter of a century investors are starting to have conversations again around after-tax returns.
At the end of the day it's the after-tax return that we actually get to keep.
So having a thought process around how taxes do impact an investor's portfolio construction is more important now than it's ever been.
So if we look ahead to the changes David and what we could be seeing in 12 months from now, what are you watching most closely?
The global government bond yields.
They're pushing up, pushing up noticeably over that five, five in the US, over five in the UK.
The Australian bond yield, what, 540 and change now, it's pushed up very noticeably in the last 18 months.
It's not a good signal.
Some people defend it by saying it's just an interest rate equation.
But when its differentials move versus others, that means there are bondholders that are not happy and that's not a good sign and so the global bond market is the thing that concerns me most because
It's one of those things where we wake up one morning and find that some very substantial bondholders have shifted.
They won't roll over into new bonds somewhere, and then if you start getting an exodus from the bond market, it gets very ugly.
But the onus is not on central banks to do it all themselves.
It's on governments to stop this spending.
And we haven't followed the right lessons either in Australia.
And speaking of government spending with the US debt 40 trillion US dollars and as you mentioned there the 10 year above 5% I had a guest today saying well what's the difference between 4.99 and 5.02 what do you say to that particularly if we could be seeing something that 2020 2006 2007 again?
Well, so much investment is about sentiment and that five is a sentimental number.
I mean, it's only two basis points, the equation, but five has always been a sentimental number.
It was a sentimental number in the Great Depression.
You know, the Australian government, the community would get really upset if the government went to the London bond market and issued over five.
That would be a
You know, the POM's having a go at Australians, but none of them looked at the discount at which they were issued.
It's always been a sentimental issue and it will stay that way, but the bottom line is, even if you look at Germany, Japan, those bond markets have shifted noticeably.
And then if you combine the government bond issuance with the debt issuance for AI-related investments,
And we don't know whether that's going to turn into the greatest thing on earth or another railroad situation yet.
It's a time for investors to be seriously reconsidering their portfolios.
Do you agree Richard?
Yeah, I do.
And I think in the construct of what David's mentioning, again, bringing that back to equity markets, having a real understanding of how that impacts company balance sheets and what that means for income investors.
The other element to that as well is there's always been periods of concentration in financial markets or particularly equity markets.
If you look at the 1920s, we looked at the great industrial revolution and the railroads
I think it was the Nifty 50s, they called it, around the 60s and the 70s, you know, the buy and hold strategy, where companies like Polaroid had 95 times PE valuations, the tech boom, and then obviously we've got the AI boom at the moment.
It's very tempting for investors to be concerned about the over concentration of industries.
But we would always advocate to be very careful about that because research does show you if you tend to deviate away from the broader market construct in terms of industry construct, that can actually lead to underperformance and greater volatility in portfolios.
So keeping an industry neutral approach, but focusing on companies that have sustainable balance sheets as we're facing into these economic challenges, we think that's something that's really important at the moment.
I was going to wrap up by asking what's your biggest one piece of advice to generating income.
So it would be similar to what you mentioned there with looking for that solid company management and dividend.
Yeah absolutely.
I think that's the return piece.
I think what is just as important is the risk piece.
So particularly at the moment, depending on what asset class the investor is focusing on in terms of deriving income, if it's equities, stay diversified.
Don't be concentrated towards industries or particular names.
We would say always hold a broad diversification of companies.
Really minimise that risk to underperformance relative to the benchmark that I mentioned earlier.
But again, regardless of the asset class, understand where you are on the capital structure, what you're actually exposed to and who you're exposed to, rather than just chasing the headline yield.
And David, what would your advice be to an investor?
Well I can't give advice, I can only comment on the market.
What would you just like to say?
I would say reconsider duration, watch liquidity, particularly these evergreen funds have been exposed a bit now, so watch liquidity, diversify as we've discussed and
tilt into credit if you believe you've been taking too much advantage of an overly strong equity market.
And that's a big issue I think for the Australian superannuation funds because the way their performance is managed now through the ASIC systems or structure of relative performance measures, they're all encouraged to compete on rate of return and that tends to tilt them too high to equities.
And with everything that we've discussed and your broad rich career history, we touched there on AI where the bond yields are above 5%, are you optimistic about the future or are you a bit concerned?
Well if you're more pessimistic you're not going to get as disappointed are you?
That is true.
But I've lived through some very good times.
I've watched some extraordinary, valuable policy responses on deregulation and reform of the Australian economy.
It's very hard to be optimistic when you watch us going backwards and kicking own goals.
and wrecking that very economy that we sorted out so much in the 80s and it's hard for me to watch that and remain optimistic at the same time, particularly in the global context at the same time.
All right, we'll leave it there.
Richard, David, an absolute pleasure to chat to you both.
Thank you so much.
Thank you.
And of course, whether it is credit or equities, the message there is clear that income is about more than chasing the highest yield.
It's about understanding the risks and making sure that you're being paid appropriately for them.
With thanks to former CBA CEO and ex-chairman of the Future Fund David Murray and Hamilton 12 Managing Director Richard McDougall.
And thank you for watching Conviction Capital.
Conviction Capital was brought to you by Investment Markets.
To find and compare Australian investments, visit investmentmarkets.com.au
Income beyond yield | Conviction Capital | Episode 4
About
David Murray says the shift to a higher-rate, inflationary environment means investors should be reassessing portfolio risk and considering greater exposure to fixed income and credit. He says private credit remains attractive, but investors need to be selective about the underlying assets, fees, liquidity and capital protection.
Murray highlights trade credit and new mortgage lending as areas of interest, arguing they can offer shorter duration and, in some cases, stronger protection than traditional private credit. He also says investors should reconsider duration and watch liquidity, particularly in evergreen funds.
Richard McDougall says Australian equity investors should focus on quality balance sheets and sustainable dividend income rather than chasing headline yields. He says diversification is critical, because high-yield strategies can create concentration risk and potentially sacrifice capital growth.
McDougall also says investors need to focus increasingly on after-tax returns, with changes to the tax environment making franked income and capital growth an important part of portfolio construction. Both investors point to rising global bond yields as a key risk to watch, with Murray warning that a major shift by large bondholders could create significant market disruption.
Disclaimer
This show is for informational and promotional purposes only. Any comments made or information provided does not consider the appropriateness for you having regard to your particular objectives, personal/financial situation and needs. Before investing you should consider independent professional financial advice. No comments made or information provided constitutes advice, an invitation, or an offer to buy any security or other financial product or engage in any investment activity. All securities and financial products involve risks. Past performance of any product is not a reliable indication of future performance. Read carefully the governing documents of a product’s offering such as its PDS, TMD or information memorandum. InvestmentMarkets does not vet, endorse or recommend any product that is the subject of these podcasts and is only facilitating the exposure of the product. These podcasts were made at a particular date in time and therefore relevant facts, the economic environment, governing documentation and the law upon which they were based may change after that date such that the accuracy and reliability of their content may be affected.
Featuring
More Videos





