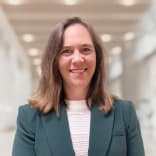
Our next presenter is Lauren Ryan, National Manager Investments for Think Tank Property Finance.
Lauren joined Think Tank in March 2018 to create brand awareness amongst the investment market and grow the funds under management in the income and high-yield trust.
Today, she'll be talking about generating a reliable income stream via the debt and private markets.
Welcome to the presentation, Lauren.
Good afternoon all and thank you for joining us for the investment markets webinar.
My name is Lauren Ryan and I am the National Manager Investments at Think Tank Property Finance.
So Think Tank is a non-bank property lender.
specialising in small ticket commercial and residential mortgages, primarily for SME, small business and SMSF borrowers.
Think Tank started in 2006, and has originated over 13 billion in mortgages.
Think Tank has never missed an interest payment, nor have institutional or private investors experienced a capital loss.
Being a non-bank lender, the capital that Think Tank lends to borrowers comes predominantly from institutional investors such as domestic and global banks, credit funds, and private investors such as yourselves.
So today I am speaking about generating a regular income stream from investing in private debt.
And I suspect that many of you already have an allocation to private debt in some form or have heard about a variety of ways that investors can invest in private debt.
So let's firstly take a look at why investors allocate for income.
Every investor has different income needs and I would argue that investors invest for income to reduce portfolio volatility, to protect capital and to fund their lifestyle as they transition to return in full retirement with no desire to go back to full-time work.
Investors who are trying to achieve income and growth goals simultaneously from a specific investment may be disappointed as these two goals are generally counterintuitive, can cannibalise each other and may encourage an investor to take higher risks to achieve a predefined yield for their portfolio.
For investors looking to invest in private debt to generate an income stream, it is imperative that the underlying assets produce a regular income.
Where the underlying asset is property, these assets can consist of existing residential or commercial mortgages where the owner, occupier or investor is paying a monthly mortgage derived from their PAYG or self-employed income and or rental income in the case of an investment property.
Other kinds of income producing property assets might be larger assets that have multiple tenants in the single building, such as an office tower, a boarding house, or a hotel, to name a few.
Loans where the underlying security property is land or an asset that is in the process of being developed or built is not yet income producing or is very likely to be income producing at that time.
And investors need to be very clear on where the income is coming from if the loan or the fund is able to pay a regular income stream.
Perhaps interest is being capitalised or has been paid in advance by the borrower.
In which case, what happens if the asset isn't built or sold by the time the interest has been fully distributed to investors?
Perhaps the borrower has spare cash or has borrowed additional funds to make those regular interest payments while the asset is being built and or prepared for sale.
Now, I'm not suggesting that these kinds of loans or underlying assets should be avoided.
Provided that investors are appropriately compensated for the risk that they are taking, there's a case to be made for any kind of investment.
I would argue that if an investor invests in private debt to take advantage of the regular income stream, it is imperative that the underlying assets are in fact income producing.
Another consideration for investors is diversification.
Arrears and defaults are an inherent risk when investing in credit.
Sometimes it can take months for a borrower to get back on track with their repayments or to sell the security asset, especially if a residential mortgage falls under the National Consumer Credit Protection Act.
Having a diversified portfolio of loans aims to mitigate against the loss of income should one or more of the loans fall into arrears and miss their scheduled interest payments.
Investors should seek to understand the structure that they are investing in, which will outline whose income, i.e.
yourself as the investor or the fund, is at risk first of income losses in the case of arrears.
If investors are relying on an income stream from one large asset, they may be exposed to concentration risk should that particular asset fall under stress or market conditions turn and that specific asset becomes undesirable.
So where can investors find an investment that addresses some of what I've discussed?
Earlier, I mentioned that Think Tank has been in business since 2006.
We've originated over 13 billion in loans and we primarily work with institutional investors such as global domestic banks and credit funds to fund these loans and our institutional, commercial and residential mortgage-backed securitisation term deals which are in the debt capital markets.
Our broader loan book, which is on the slide right now, is made up of a diversified pool of small ticket commercial and residential mortgages with an average loan size of $607,000 and an average LVR of 66% as at the 28th of February, 2025.
In August, 2017, the income and high yield trust opened for wholesale and sophisticated investors.
The income trust is a first mortgage fund with 95 million assets under management, which is made up of 130 loans secured by existing small ticket commercial and residential properties as at the 28th of February, 2025.
The majority of think tanks loans are on a variable interest rate.
And as such, the return to income trust investors also has a variable component.
As at the 10th of March 2025, the return is 7.69%, which is made up of a 3.6 fixed margin plus the bank bill swap rate 30 days, which is the variable component.
And the bank bill swap rate 30 days is reset on the 10th of each month or the following business day.
As the official cash rate increased since May, 2022, the borrower's default risk also increased.
And in turn, the income trust return increased accordingly.
With the recent RBA cut in February, borrower's interest rates were reduced by 25 basis points, a variable borrower's interest rate, I should say, and investors' returns decreased accordingly when the BBSW 30 was reset.
Underpinning the mortgages the income trust investors are exposed to is 28% worth of borrower's equity as at the 28th of February 2025.
The minimum investment for the income trust is $10,000 and we ask investors to commit capital for a minimum of 12 months.
In September 2024, the Income Trust received an inaugural rating from SQM Research of 3.7 out of 5 stars, which is investment grade.
This rating was a just reward after seven years of strong performance from the fund and the underlying assets.
Think Tank's institutional, commercial, and residential mortgage-backed securities debt capital markets transactions are rated by Standard & Poor's and Fitch for the AAA Tranche.
Similarly, how investors protect their portfolio against volatility by having an allocation to growth and an allocation for income.
Within their defensive allocation, there will likely be higher and lower yielding assets, remembering that higher yield equals higher risk.
For investors who have exposure to high yielding private debt instruments, the income trust may play a valuable role when it comes to diversification and income protection as the economy progresses through various cycles.
Thank you for your attention today and for your consideration in regards to how think tanks income trust can play a role in generating a reliable secured income stream as part of your portfolio.
If you have any questions, please feel free to contact me.
My contact details are on this final slide.
And for those of you who are interested in the portfolio data that I shared today, please feel free to get in touch.
I trust that you enjoy the remaining webinar sessions and thank you for your support.
Lauren, as we know, the private credit market is becoming crowded.
How do investors navigate the noise and find suitable managers to work with?
Yeah, that's a great question and a question that I've come across quite a few times with new investors.
And I'd say that the way that investors find suitable managers would be
somewhat similar across their portfolio.
So I would say for those of you who are looking at private credit to add to your portfolio or to expand your private credit managers, check out their track record and see how they have performed through the last couple of cycles.
I appreciate that we haven't had too many of those in the last sort of 20 years.
And some of the portfolio level data that I shared with you today, see if they're in a position to provide transparency around how the fund has performed.
through the good and the bad times.
And ask as many questions as you can, and you will get a sense from each manager whether they're in a position to answer those questions or not.
And if you come up with a manager who isn't in a position to answer those questions, then they might not be the manager for you.
Also, if you can see who else that they have worked with, whether they've got other institutional investors as part of their investment pool,
those institutional investors are generally able to command a slightly more detailed level when it comes to governance.
And if an institutional investor has completed that governance and still chosen to move forwards with that manager, then investors might be able to take some comfort from that, that the institutional fund is comfortable with the manager and the way that they operate their credit policies and their overall corporate governance.
How do RBA interest rate cuts impact the private credit market and investors' returns?
Yeah, that's a great question as well.
I touched on this in my presentation.
If you're investing in a fund that has a variable rate of return component, as the RBA cash rate gets cut, the borrower's mortgages will decrease and the return that investors get will also likely decrease accordingly.
there might be a few fixed term lending opportunities out there in the market.
Generally they are for a shorter term.
And once that fixed term has rolled over, it is quite likely that new loans that appear will be at a lower rate.
So we are definitely going to see the returns start to come down as the RBA cash rate decreases.
Again, as I touched on in my portfolio, it's a risk and return profile.
So for those of you looking to allocate to this market,
As we see the returns going down, the default risk is also going down, which is a large part of the defensive portion of your portfolio.
So just keep that in mind that when you are investing, if you have an outlook for the cash rate for the next six months, 12 months, two years, depending on how long you plan to allocate to private credit.
and the level of income that you're looking to receive from that investment, that we might see a few RBA cash rate cuts coming through during that time period.
But also keep in mind that it is a risk and return play there.
Thank you for your time, Lauren.
Thanks, Angelina.
And thanks, investment markets.
Generating a reliable income stream via the debt & private markets
About this presentation
Lauren Ryan from Thinktank discusses how investors can generate a reliable, regular income stream from investing in income producing, first mortgages and mortgage-backed securities from a non-bank lender with 18+ years experience. Lauren also explains how Thinktank utilises the debt capital markets and works with institutional investors alongside private investors to offer attractive risk-adjusted returns via first mortgages secured by domestic, small-ticket commercial and residential properties.
Wholesale Investors Only
The product(s) mentioned in this presentation is available to wholesale investors only. It is not applicable to or appropriate for retail investors.
Disclaimer
- The presentations made during this seminar are for informational and promotional purposes only.
- Any comments made or information provided does not consider the appropriateness for you having regard to your particular objectives, personal/financial situation and needs. Before investing you should consider independent professional financial advice.
- No comments made or information provided constitutes advice, an invitation, or an offer to buy any security or other financial product or engage in any investment activity.
- All securities and financial products involve risks.
- Past performance of any product is not a reliable indication of future performance.
- Read carefully the governing documents of a product’s offering such as its PDS or information memorandum.
- InvestmentMarkets does not vet, endorse or recommend any product the subject of the presentations and is only facilitating the exposure of the product.
- These presentations were made as at 25-27 March 2025, and therefore relevant facts, the economic environment , governing documentation and the law upon which they were based may change after that date such that the accuracy and reliability of their content may be affected."
Featuring
Tags
More Videos





