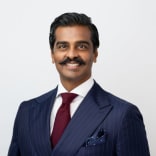
Our next presenter is Patrick William, Managing Director at Rickson Capital.
Patrick has nearly 20 years experience in high-yield SME private credit and public credit M&A.
His presentation topic today is how a boutique private credit fund strategy can outperform larger funds.
Welcome to the presentation, Patrick.
Thanks, Angelina.
This presentation is a timely opportunity to formally address a question we get from investors all the time.
You know, why should I invest in a boutique strategy when there are large funds out there with a very similar returns profile?
And fundamentally, it comes down to, well, it's not a dinner party conversation, so I'll limit it to three key factors.
A prescriptive investment mandate, the ability to access higher returns for lower risk, and personalized investor relations.
So what investors really need to understand is, while various funds may have similar headline returns, what you've got to understand is what the underlying risk is, because the risk is different, then that return becomes a lot less relevant or a lot more important.
So the goal of this presentation for me is for investors to walk away with some degree of understanding that all things held equal, a boutique strategy will deliver a superior risk reward to a large fund strategy.
Now, if you look at, you speak to a large fund manager, look at their website, they tend to talk about a preference for asset backing, a preference for senior ranking debt, which is perfectly fine and ideal.
Except if you look at the information memorandum, which is the rulebook, they're generally permitted to invest in anything that smells like debt.
And now there's fundamentally nothing wrong with that.
They've got a broad mandate, which is why they can grow into a very large fund.
Where it becomes problematic is when you're an investor, you've got a fixed target return 8, 10, 12%.
But with these funds, you've got a variable risk variable.
So a large fund can theoretically always meet their target return because as the market gets more competitive, they can just move up the risk curve.
Now, by contrast, a boutique strategy is small by design.
So that design is predicated by having a prescriptive investment mandate.
So there's no invest ambiguity.
If you read the IM, the IM sets guide rails or guide rails for the fund manager.
You know, the Rixin fund is an example.
All the debts, first ranking, senior secured, asset backed, and the borrowers have to have available cash flow service to debt, interest payments, monthly in cash.
all defined, all clear.
So as an investor, you've got comfort and confidence that when you put your capital in, you're getting a defined level of risk for that return.
Now, where this is particularly important is if you're a risk-averse investor.
So if you look at those two diagrams,
You know, if you're an SMSF investor with a boutique fund, if you pick a fund that is senior secured asset backed, you can put your capital in and rest assured that, you know, in 12 months, three years, five years, that's all the fund ever does.
So you can define risk profile that you are comfortable with on day one.
With a large fund, you do run the risk of investing in day one when the fund is primarily senior secured.
But heaven knows where you are through year five because that fund starts doing more subordinated funding or asset or covenant-like funding.
Your risk profile is blown out.
And as an SMSF investor going into retirement, that's not what you want.
Now we contrast the ability of a boutique strategy to deliver higher returns for a given level of risk
So if you look at the broader funding landscape, if you're a high quality borrower looking for over 20 million dollars in debt, you're very well serviced.
You know, as you hit the 40 to 50 million dollar range, the banks look after you.
When you're above 20 million dollars, the large funds are lining up to give you capital.
The challenge there for the large funds is that means this competition.
So you've got a choice.
You can lower your returns to move lower your returns to take on lower risk or move up the risk curve to take higher risk.
So their risk reward proposition is tight as it should be.
So if you're seeing really high returns in a large fund, by and large, they're delivering it by taking on more risk.
In contrast, if you look at a boutique lender, they focus on underservice space because they are smaller funds because they write smaller checks.
So if you're a quality borrower looking for, say, $5 million, you're in a difficult spot.
You might have assets, you might even be profitable, but
uh your choices are friends and family because the funds aren't going to deal a half a billion dollar fund is not going to write a five million dollar loan so your choices are friends and family which are not a sustainable option or opportunistic funds that look to take five to ten percent of your business in equity as well so this allows pure debt boutique strategies to focus on high quality borrowers and say look you haven't got many options out there
I will give you a solution where I'll take you from one to two million dollars or five million dollars up to 20 million dollars over several years.
But in return, I extract a scarcity premium.
You pay me a premium price to compensate my investors.
But the end of three is you can refinance out for a far better price.
But in the meantime, the boutique fund investors are protected by asset backing and are rewarded with a very attractive cash yield.
I mean, I think it's quite obvious, right?
You look at you look at those two charts, you can just see boutique funds are the advantage of being undertaking bilateral negotiations when they're looking at writing debt.
So you're going to get better pricing, better terms, and most importantly, very, very good security.
You can leverage that to outsize returns for a defined level of risk.
And last but definitely not least, if you're an investor, is access to the investment manager and access to information.
Now if you're a large fund by design, you know you're huge.
So unless you're investing 7 to 8 figures, you're not going to get access to the investment manager.
You're not going to get access to the portfolio manager.
You'll be lucky to get a graduate reading your script if you get through the phone line.
They're also less likely to report very detailed portfolio holdings because they might have 100 loans.
In the same breath, they might also have a lot of subordinated debt, which they'd rather not put out there.
In contrast with a boutique, because they're small by design,
they're able to offer direct investor access.
So again, with the Rickson Income Fund, I'm the portfolio manager, and I speak to all my investors.
And there is substantial value to you as an investor to be able to get a detailed briefing as and when required, particularly if you're concerned about the market or you're looking to top up your investment.
We're able to provide very detailed reporting because we'll never hold 100 loans.
We'll hold 20, 30, 40 loans at best, and that's easily an addendum to our monthly unit holder update.
And this reduced information asymmetry as a material, intangible value to investors.
A boutique can see its investors as individuals, and by virtue of being able to speak to my investors, we understand this is hard-earned capital, whether it's $50,000 or $4 million.
Either you've worked really hard for it or someone else in your family has, and you're working really hard to maintain capital value and deliver a return for your family.
And we're able to offer the respect, if you like, and the personalized treatment that should come with it.
Now, it's unsurprising.
The Rickson Income Fund is obviously a boutique private credit strategy.
We've got a very, very prescriptive strategy, and it's disclosed in IIM.
So our guide rails are very clear.
All loans we write must be first ranking, senior secured.
They must be asset backed by real assets, receivables, equipment, plant property.
We have a target return that's defined 10 to 12% per annum, net of fees and costs paid monthly.
So you've got a defined risk and a defined return.
I'm also very pleased to share, you know, we are performing well within our fund mandate.
So the current portfolio reflects 100% senior secured asset backed portfolio at a 60% LVR.
We distributed 0.94% in January, which annualizes to an 11% rate of return.
And our annualized return since inception is just over 12%.
And while we're very proud of our funding, the value we create investors, nothing beats external validation.
their most recent LEED table prequent rated the Rixson income fund the number one ranked asset backed credit strategy in the Asia PAC region with the number four ranked credit strategy in the Asia PAC region and it's notable that the funds that outperformed us there were long shot hedge fund strategies which are a completely different risk profile.
We're very proud of what we do, and we're an employee-owned fund manager.
So our success is very aligned with investor outcomes.
So we're not looking for short-term gains or short-term sugar hits.
We're building a business alongside of investors for the next 10, 20 years.
That's really us in a nutshell.
So if you've got any questions, please reach out via our website.
But I believe you've got some questions that have come through, Angelina.
Thank you for your presentation, Patrick.
If the risk reward proposition is so attractive in the sub-20 million lending space, why aren't there more funds targeting that niche?
Look, that's a great question.
So we went through this experience when we set up our fund.
We spoke to some institutions that look to incubate big funds.
You know, to hear the proposition, they think, look, the risk reward's incredible in that sub-20 million dollar space.
And then they ask the question, how quickly can you grow it to a billion dollars?
And the short answer is you can't.
It's a niche.
The risk income fund will probably top out at 250 to 300 million dollars, which is perfectly fine.
And the economics are very attractive for our shareholders, but for big, big funds, particularly global players, a large list of players in Australia, that's not worth their time.
So while they acknowledge our returns are very attractive,
Their focus is on funds under management.
If you can't build a fund to a billion dollars, they have no interest in the space, which is perfectly fine by us because it leaves a very attractive niche for us to harvest, if you like, for our investor base.
You discuss a focus on asset backing.
If a borrower has a substantial equity value and a relatively smaller loan, shouldn't that valuation alone provide sufficient protection for investor capital?
Again, that's a very good question.
So you've got a lot of funds out there that will lend against equity value or cash flows.
You know, they call them cash flow lending.
And the pitch, of course, or the message to investors is, look, I'm lending them $2 million.
They've got a $10 million equity valuation.
What a great loan value ratio.
What investors need to understand is all that security underlying a loan has no meaning, has no real value unless the business is challenged, unless they defaulted on the loan.
So you might have a 10 million dollar equity value when the loan is written, but the only time you want to stake a claim on that equity, on that security or that collateral is when the business isn't paying you interest.
And I can tell you, if you're defaulting on your interest, you're not worth 10 million dollars anymore.
Number one.
Number two, how do you sell a business which has got earnings in decline?
That's why we focus on asset back lending and real assets, because if a business, heaven forbid, went south,
We've got registered liens over equipment, receivables and property, which retain value in the downside, which we can liquidate in the open market and recover our investor capital.
Thank you, Patrick.
Good to see you again.
Thank you, Angelina.
How a boutique private credit fund strategy can outperform larger funds
InvestmentMarkets Investor Webinar March 2024 Wholesale Investors Only The product(s) mentioned in this presentation is available to wholesale investors only. It is not applicable to or appropriate for retail investors. The Rixon Income Fund is a niche, asset-backed, high-yield private credit fund focused on capital preservation & monthly income. Patrick William is the Managing Director at Rixon Capital, he has nearly 20 years' experience in high yield SME private credit and public & private M&A. Disclaimer
- • The presentations made during this seminar are for informational and promotional purposes only.
- • Any comments made or information provided does not consider the appropriateness for you having regard to your particular objectives, personal/financial situation and needs. Before investing you should consider independent professional financial advice.
- • No comments made or information provided constitutes advice, an invitation, or an offer to buy any security or other financial product or engage in any investment activity.
- • All securities and financial products involve risks.
- • Past performance of any product is not a reliable indication of future performance.
- • Read carefully the governing documents of a product’s offering such as its PDS or information memorandum.
- • InvestmentMarkets does not vet, endorse or recommend any product the subject of the presentations and is only facilitating the exposure of the product.
- • These presentations were made as at 19-21 March, 2024 and therefore relevant facts, the economic environment , governing documentation and the law upon which they were based may change after that date such that the accuracy and reliability of their content may be affected.
Featuring
More Videos



