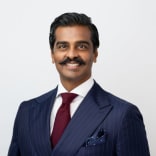
We now welcome Patrick William, Managing Director at Rixen Capital.
Patrick manages the Rixen Income Fund, a boutique asset backed SME private credit strategy focused on capital preservation and monthly income.
Today, Patrick will be talking to us about the ASIC private credit review and why it matters to investors.
Over to you, Patrick.
Thanks, Darren.
Patrick William, good morning, good afternoon, good evening to listeners.
Look, this topic I thought was very topical given A, the ASIC review of the private credit sector, and B, the ongoing media coverage in, you know, all mainstream financial and mainstream media.
ASIC published a paper in September, it's called the REP 814, flagging a number of areas for improvement.
Now, given the constraint of time and attention spans this time of the year,
This paper focuses on the three priority areas that ASIC has explicitly highlighted.
Fee disclosures, the potential for mismatch of risk and reward, related party transactions, potential for misalignment of interest between fund managers and investors, and valuations where they're generally just misleading.
The first example is on fee disclosures and how it impacts investors.
So let's take a hypothetical investment.
You've got an investor earning a 9.5% return.
Now returns are free, so there's a disclosed 1.5% management fee.
So what investors would perceive or rational investors perceive is the borrower was prepared to pay an 11% rate of interest.
Therefore, investors are exposed to 11% risk, which is not outrageous.
They pay a 1.5% return to the management book underwriting and they get 9.5.
Now what happens if there is an undisclosed fee?
Call it what you want.
Establishment fee, upfront fee, arranging fee.
This hides the underlying risk exposure because let's call that a 4% undisclosed fee.
What that means is the actual cost of the loan, the actual payment paid by the borrower is 15%.
So you're now exposed to 15% risk, not 11% risk as you perceived.
And this is problematic because as an investor, you've got a 15% risk explorer, which is 50% higher than the 9.5% you get.
Now this raises two issues.
The most obvious is the disconnect between the perceived and actual risk.
You think you're exposed to 11% risk, you're actually exposed to 15% risk.
But second, perverse incentives that create.
Because here you've got investors exposed to 100% risk.
and earning 9.5%.
But then you've got the fund manager who's exposed to none of the risk, but generating 5.5%, 4% plus the 1.5.
The key learning there for investors is you must ensure fees are disclosed and quantified.
Because if you haven't got that clarity, you're likely in for a nasty surprise if things ever went wrong.
The next priority area for ASIC is related party transactions.
Now this diagram here is meant to capture the relationship between a conventional fund manager and its investors.
Investors invest in the credit fund.
The fund manager's job is to find the best risk-adjusted returns for its investors.
The manager identifies and underwrites the loan to a borrower at 11%.
The manager is paid a 1% management fee.
Investors receive 10%.
Very uncontroversial.
Now, but what happens when that borrower is a related party?
A business that's actually owned by the credit fund manager themselves.
But remember, a rational borrower is always looking for the lowest cost of debt with the loosest covenants.
So if your fund manager is lending to a business that it owns, then you, the investor, are the cheapest funds available in the market.
Otherwise, the borrower would look elsewhere.
ASIC's focus here, though, appears to be less than the fact that investor returns a subpar for the risk, but the risk of conflicts of interest.
So if you look at this scenario here, the manager earns a 1% management fee from making lending decisions in the best interests of investors in the private credit fund.
That same manager is generating 20, 30, 40% equity returns from lending that money from the private credit fund to a business it owns.
Now investors have to ask themselves, how much weight do you think your manager is gonna place given their fund investment is generating such a substantial return for the fund manager?
The business that's making them 1% or the business that's making them 20%?
And that a key learning there for investors is related party lending should be disclosed, and that's really where ASIC is pushing.
But secondly, even if it is disclosed, investors need to understand that when the chips are down, people make decisions based on where the incentives lie.
And if you look at that 1% management fee, you look at that 20% return, you are unlikely to be the fund manager's priority.
The final issue is on valuations.
Now the marrying facets to it, but the focus is predominantly in the property development sector.
So I'm going to focus on a property development hypothetical and when an LVR is not what you think it is.
On day one, a developer buys a site for two and a half million dollars of cash.
They get a DA approval for, let's call it an apartment block.
Now that creates an immediate uplifting value because here's this piece of land that you can generate all this value from because you have an approval for development.
Now remember, this site was acquired for only $2.5 million in cash, but now because of that DA, because of a valuation, it is valued as a $10 million site on an as-if complete basis.
Now that point is very important because number one, it's a paper uplifting valuation,
The valuation is on an as-if complete basis, which means it's worth $10 million when it completes in two or three years.
When the block were partnered up and the units are sold, it's still a $2.5 million piece of land.
Now the developer borrows at what seems a very conservative 65% LVR against that $10 million valuation.
And again, a rational investor would say, hold on, that's pretty good.
I put $6.5 million out the door for a $10 million asset, 65% LVR, and I've got a 35% or in this case, a $3.5 million first loss buffer.
But the reality is, as I say again, until the project is completed, your $6.5 million loan is secured against a $2.5 million piece of land and $7.5 million in speculative value.
It's worth that when the project completes in two to three years.
If it fails in the interim, you are not going to be able to get the capital back.
The key lesson there for investors is an LVR is not the be all and end all.
The definitions count.
So if you ever pitched a project and you're told there's an LVR of 50, 60, 70 percent, the question you should ask is, is that asset working?
that much today, number one, and number two, could it be monetized that price today?
Because going back to this example, at the 65% LVR, there is no way you'd get 65 cents per dollar if the project failed prior to completion in year three.
Thank you.
Thanks for those points, Patrick.
Certainly, if you're an investor, there's a lot to consider.
And if I was an investor in a fund and looking for a cheat sheet, so to speak, to help me out, what are the questions I should really be asking before I take the next step and invest?
I mean, going back to the presentation, look, assets got a very long list of questions they'd like you to ask.
I mean, the practicality of it is people aren't going to ask 20 questions.
So you had to summarize it.
The three points I covered are material, what are the fees and make sure they're disclosed and quantified.
What is the underlying asset base?
If you think you're getting an asset lender at an attractive LVR, is it actually what you think it is?
Thirdly, is there related party transactions?
Those are the headline issues.
But my advice to a lot of investors is if you're not sure, read the information memorandum, get advice from an accountant or a wealth manager, because if you don't understand how the fund is generating the return, you should be very cautious about deploying capital, irregardless of the fund's track record or return profile.
the age old adage that the higher the risk, the higher the risk and higher return both go hand in hand, I think.
And probably just an aside question is, how has this all eventuated?
How has this level of disclosure or lack of disclosure, I should say, how has this come about?
A lot of the ASIC regulation on disclosures were put in place when the only real unlisted funds you invested in were equity funds.
So equity funds are very, very vanilla.
If it's a listed fund, it's pretty obvious where they're investing.
So all you're really looking at is a paragraph that describes where they're going to invest, ASX 200, ASX 50.
a little paragraph on what the fees are, which are very transparent, and the profile of the management team.
So I think ASIC's been relatively loose with what those disclosures have to be, because the market policed itself.
Private credit is a relatively nascent sector in Australia.
And what some opportunistic managers have done is they've respected the lesser of the law rather than the spirit.
So a lot of funds will disclose they take upfront fees, they just won't quantify them.
So investors assume it's 0.5%, not 5%.
There are funds that will disclose related party transactions, but again, if you don't disclose the fact that the manager is making 30% here and 1% from you,
there is a very material conflict of interest.
That gets problematic.
So it's a sign of how nascent the sector is and I suspect a lot of ASIC's pressure is to get the industry to smarten up themselves and begin to police themselves.
I'm just, maybe finally, do you think that's a reasonable ask of the industry?
That the industry will police itself to the level that maybe ASIC expects?
Look, I think using game theory, I think you will end up in that scenario where the industry will self-police for several reasons.
The key amongst them is if ASIC is prescriptive, you must do this and you must do that, it will incur a cost.
It's not a one-size-fits-all, so it will be problematic to some fund strategy.
So, good fund managers will sit back and go,
My returns will contract by 1.5% if I incur all these costs.
How about I do the right thing or do what ASIC wants and get the other people or my peers to do the same so we can maintain our level of return while giving ASIC and investors confidence that things are kosher.
The plus side of that as well is the bad actors or the passengers, if you like,
journeying through a new sector will lead because they will not be able to make those disclosures that the good fund managers make.
So the higher the level of disclosure, the better it is for everybody, all the players in the value chain.
Is that a fair summary?
That's a very fair summary because you've got nothing to hide.
Odds are you're doing the right thing.
Lovely.
Thank you very much for your insights today, Patrick.
Thanks, Darren.
The ASIC Private Credit Review | Why it Matters to Investors?
About this presentation
The recent ASIC Private Credit review flagged areas for improvement in the sector. Patrick William, Managing Director at Rixon Capital discusses HOW and WHY these areas of weakness increase investor risk.
Wholesale Investors Only
The product(s) mentioned in this presentation is available to wholesale investors only. It is not applicable to or appropriate for retail investors.
Disclaimer
- The presentations made during this seminar are for informational and promotional purposes only.
- Any comments made or information provided does not consider the appropriateness for you having regard to your particular objectives, personal/financial situation and needs. Before investing you should consider independent professional financial advice.
- No comments made or information provided constitutes advice, an invitation, or an offer to buy any security or other financial product or engage in any investment activity.
- All securities and financial products involve risks.
- Past performance of any product is not a reliable indication of future performance.
- Read carefully the governing documents of a product’s offering such as its PDS or information memorandum.
- InvestmentMarkets does not vet, endorse or recommend any product the subject of the presentations and is only facilitating the exposure of the product.
- These presentations were made as at Oct/Nov 2025, and therefore relevant facts, the economic environment , governing documentation and the law upon which they were based may change after that date such that the accuracy and reliability of their content may be affected.
Featuring
More Videos





