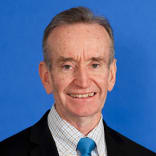
Finally, it's my pleasure to introduce Paul Brennan, Chief Economist at Suncorp.
Paul joined Suncorp in 2020 and has over 40 years of experience in financial markets, including roles at the RBA, Treasury, the OECD and Citigroup Australia.
He is a regular contributor to the Australian Financial Review, The Australian, and appears frequently on Auspice.
Today, Paul will provide us with an insightful economic update.
Follow with a Q&A with me.
Welcome, Paul.
Thank you.
Thank you, Angelina.
So I will be talking about some of the big themes in economies and markets.
And I think, Angelina, it's a very good timing because at the moment there's a view that maybe we're at a turning point in economies and markets.
And that's why I've subtitled this presentation, Waiting for Goddard.
Some of you might remember there was a famous play by Samuel Beckett called Waiting for Godot.
And let me just go to my next slide, which was in this play, there were two characters that meet at dusk to wait for someone named Godot.
And they debate, when will Godot come?
why are they waiting for him and whether they're even at the right tree to meet him.
And this is, I think, got some parallels with financial markets and economies, because we've been waiting for some time to see the impact of monetary, the tightening of monetary policy globally on economies.
And from that, of course, there would be very significant implications for financial markets.
Now, so let me just give a bit of a roadmap for the points that I'll be hitting in this presentation.
First is how likely is a US recession?
Because I think that is really the key to the economic and market outlook.
What does this mean for financial markets?
But also not forgetting China, because China is the second largest economy.
And then I want to touch on what are some of the implications for Australia and then I'll sum up the presentation and draw some of the key conclusions.
Where are the recession risks in the US?
Well I think there's a few.
One is that we're already seeing signs the manufacturing sector is in recession.
What we're seeing in this chart is it just shows the relationship between
orders, new orders in manufacturing versus inventories.
And you can see that that line right at the end is dipped down again below zero, which is just telling us that new orders in manufacturing in the US are falling.
relative to inventories.
And so that's, I think, a warning sign of recession.
At the same time as well, you can see in this chart that the US yield curve, so the relationship between the short end of the bonds and the long end, so the two year bonds and the 10 year bonds,
has been inverted now for over two years.
Historically, it's been a very good indicator of recession in the US.
This time around, as you can see in this chart, the curve has been inverted for a lot longer than what it's normally taken.
to see a recession in the US.
And I think there's a number of reasons for that.
One is that there was just massive stimulus in the US, but indeed in most economies.
Fiscal and monetary policy was set really strongly during the pandemic.
And that's helped to support the economy, even though monetary policy has been gradually tightening.
So that's, I think, something that we still need to bear in mind that that tightening of monetary policy is still working away and is working to slow the US economy.
At the same time, what we're seeing is, let me just move on, sorry, from that.
Oops, let me just get this, try and move this presentation along a little bit.
And so what I wanted to show here is that the key part of the US economy is really the labour market.
And what we're seeing very clearly in this chart is this after this period of exceptional strength, what we're now starting to see is the employment slowing quite noticeably.
Now employment is still growing, but it's growing at a lot slower pace than what it has been.
And unemployment is gradually starting to rise as well.
So this is another warning sign that recession is maybe not all that far away.
At the same time as well, we're seeing the slowdown in the economy flowing through into lower inflation.
inflation is coming down and this is opening the opportunity for the Fed to be cutting interest rates.
And so the big question then is, can the easing in monetary policy from the Fed save the economy?
Now, what this chart shows is that when the interest rates peaked historically, and the Fed started to ease, normally it was still the case that the economy went into recession.
And you can see that in those red circles.
that after interest rates began to fall, the economy still went into recession very shortly after the Fed started to ease.
So this is this big question around whether the Fed now is too late to prevent a recession by easing monetary policy now.
The one exception to this, and you can see this in the chart, is in the mid 1990s, where the Fed did start to ease after tightening monetary policy in the mid 1990s, and the economy did not go into recession.
So that must give us hope that maybe the Fed can achieve this soft landing that we all would like to see.
However,
I think the important reason why in the mid 1990s, why the US economy didn't go into recession after the Fed had tightened monetary policy is because productivity growth started to boom in a very structural way on the back of, if you remember, the internet boom in the late 1980s, early 2000s.
Now, what we're seeing now in this chart, this shows the growth in US labour productivity, and you can see it is rebounding, but it's still a long way
from where we were back in this period in the late 1990s and the first half of the 2000s.
There is a lot of hope that the AI boom will drive significant productivity gains.
But as we saw with any new technology, it takes time for companies and individuals to be able to tap in and use that technology in a way which is going to lead to significant productivity improvements.
So I think this is still very much an open question about whether the AI boom is going to come and save the day and help the Fed achieve this soft landing.
Now, if I can turn to financial market implications, I think even once the Fed starts to ease monetary policy, what tends to happen is that share markets tend to take the good news from the Fed easing monetary policy as bad news for the economy.
That is, the markets interpret the easing in monetary policy as a sign the economy is weak
And that of course plays through into the outlook for company earnings and therefore for share prices.
So historically, as you can see from this chart, that when the Fed starts to ease, you get this initial maybe bounce in share prices, but it doesn't last very long and you see a period where share prices fall.
And this is the question at the moment.
whether we're already starting to see this correction after what has been an exceptionally strong period of share market gains and risk on in financial markets.
So I think allied to that question is that the share market also has a number of features which worry us.
So for example, this is well known, market concentration is quite extreme.
We've seen
very little growth outside of the so-called magnificent seven shares in the US.
So the Microsofts and the Nvidia and the Apples are a matter of this world.
They've been driving the share market gains and so you know we're in this unusual situation where markets are extremely concentrated and that I think adds to the risk
that it's going to be hard to achieve this soft landing in share markets from the Fed's previous tightening of monetary policy.
As well, if we look at earnings expectations in the markets, they look exceptionally strong.
And that's at a time when the profit share of GDP for US companies is at record highs.
And finally, market positioning amongst investors still looks extremely optimistic.
And we tend to see that with the market being prepared to buy dips when you see a correction in share prices.
So it does look as if the features of the share market look fairly challenging if we are going to achieve this soft landing for both economy and for the share market.
So if I can now turn to China.
China is the second largest economy in the world, and it's particularly important for Australia.
And so what I've shown here is a chart of core inflation in China.
And as you can see, those lines are really falling away quite sharply, which indicates that there's mounting deflation pressures in China.
Core inflation is actually
fell in the month of August and the annual rate of increase in core inflation in the US is only barely above zero.
And what's behind that?
Well, if we look at another indicator of the health of the Chinese economy is property prices.
Property prices, as you can see in this chart, have just been continuously falling.
for a number of years now, since basically even before the pandemic.
And this is reflecting the chronic property market slump, which there doesn't seem to be any end in sight.
And neither does the government appear to have any strong answers to how to deal with this property market slump.
Interest rates are already very low in China, so it's not as if they've got a lot of firepower left to be able to stimulate the economy.
Indeed, if we look at what it means for Australia, one of the things that's particularly worrying
is that the excess capacity in the steel sector in China is driving down the price of iron ore, but also for metallurgical coal.
which are two of our major export commodities.
So in the last six months or so, we've seen the iron ore price fall by over 40%.
And that's going to weigh on export income coming into the Australian economy.
And that will in turn be another factor working to put a break on the outlook for the Australian economy.
So I think importantly, it doesn't appear as if China is going to come to the rescue for Australia.
And this is at a time when the RBA, the Reserve Bank, is still battling with inflation.
Unlike the US, where as I showed you, inflation has been falling quite quickly.
In Australia, as you can see from this chart,
these various measures of inflation look like they're moving sideways and well above the Reserve Bank's target of two and a half percent.
So that means the RBA doesn't have a lot of capacity to be easing monetary policy quickly.
At the same time, if we look at the latest readings on the economy from the June quarter national accounts, it looks very soft.
Real GDP growth is growing less than 1%, less than population growth.
If we look at this chart here, maybe a little bit hard to read, but what it shows is that none of the major components of GDP, so consumer spending, dwelling investment, business investment,
making hardly any contribution to growth in the economy.
Indeed, in the June quarter, consumer spending and business investment actually fell.
The only thing that's really keeping the economy positive and staying out of recession is government spending.
And a lot of that, of course, is an area of healthcare, the NDIS.
Defence is another area.
But if it wasn't infrastructure, of course, if it wasn't for those areas, you'd have to say the economy would probably now be in a recession.
And looking at the household saving, household balance sheets, they don't look like they're particularly strong because income growth is weak, debt has been going up, and household saving, as you can see in this chart, is flatlining at very low levels.
So I think, again, as we did in the US, we come back to the labour market as really what is going to be key to be guiding our thoughts on where the economy goes.
And I think unfortunately, what we're seeing is that labour demand is softening.
now albeit from exceptionally strong levels, but what you can see in this chart is this dotted line is the ratio of job vacancies to unemployment rate and it is plotted as inverted on this chart.
And what it shows is that we went from an exceptionally strong level where job vacancies were outstripping those looking for work because of the very strong stimulus in the pandemic, but now what we're seeing is that's reversing as the economy is slowing, as I mentioned,
And as a result, you can see in this line here, this blue line, you can see the unemployment rate is starting to gradually rise.
And so we would be expecting that with the slowdown in the economy, very weak growth in the economy, the unemployment rate is going to continue to track higher.
Reserve Bank thinks it might only rise a little bit from here, but we're sort of a bit more skeptical of that and thinking that the unemployment rate could push towards 5%, maybe not quite get there, but that would still be a material rise from where we were back at the low point, which was around 3.5%.
Where are some of the pain points that we're seeing in the economy?
At this stage it looks to be more in the small business sectors of the economy.
So what this chart shows is a company in solvencies.
And what you can see from both those lines is both the number and the ratio to all businesses is rising quite quickly.
We're seeing this particularly in the construction sector where we're seeing a number of major
businesses coming under financial pressure, some of the smaller operators in the construction sector actually having shut down.
Also seeing in hospitality sector as well, rising costs, lower demand, squeezing earnings, and against that backdrop, it's meaning that companies are under
under significant financial pressure.
If we turn then to the larger companies which are listed on the share market, what you can see here is that historically company analysts who are forecasting company earnings
tend to be constantly surprised by how well company earnings perform.
So this line here shows that the number of profit reports, which beat expectations of endless, tend to be much greater than the number of
or the share of company earnings, which are disappointing expectations.
But what we're seeing now, as you can see from these, these two lines are converging.
So the portion of beats, of earnings beats is coming down and it's converging towards the number of disappointing earnings.
So in the last reporting season,
in Australia, what we saw was that there was almost an equal number of companies that were beating earnings expectations relative to those that were disappointing.
And this is a reflection again that even for large companies, the weak economy and still significant inflation pressures is providing a significant challenge.
And as a result,
it's not surprising that we receive companies looking to cut costs.
And one of those costs, of course, is labour costs, which of course means that we're seeing this rise in unemployment.
So I might just show one more chart and then I will finish up, Angelina.
If there is a
positive in the economy, and it's nice to end Angelina on a positive note, is that you can see this red line, which is household wealth has been, it's almost vertical, it's been rising so strongly.
And this is a reflection of the strength in the share market until recently, but more importantly, the significant rise in house prices that we've been
that we've been seeing because of the underbuilt in housing and the strong population growth.
And this has been driving house prices higher, even though monetary policy is trying to work to cool the economy.
The problem, of course, is that not all of this wealth is equally shared.
It's mainly amongst those that have got the ability to leverage into the housing market
And that tends to be the more older demographic rather than the younger demographic, which of course is really struggling in terms of high rents and also the large deposit gap that they face trying to get into the housing market.
So what we're seeing as a result is that consumer spending overall has actually fell in the June quarter, as I mentioned.
But in fact, if we look at the part of spending which has
that is predominantly demographic groups, that is actually quite strong.
So I'm thinking there of people going out for restaurant to restaurant.
Travel has been a very big one.
People, again that old demographic, are still able to go out and travel to
the US and Europe, even though of course the exchange rate is making it really quite expensive.
So we've got this dichotomy in the economy where the younger demographic, from 25 through to 45, it's really
struggling under the weight of high interest rates and falling real wages until recently.
Whereas that older demographic is benefiting from the wealth accumulation on the back of those higher house prices.
So Angelina, let me just sum up.
I think history suggests that a US soft landing will be hard to achieve, even with the Fed starting to ease this month.
In other words, going back to Samuel Beckett's play, Godot I think will arrive.
I think some sort of recession will arise.
It may be a mild one.
but I think it's going to be very hard to afford, even if it is later than usual.
Secondly, markets are priced for even a mild recession.
And I think as a result, if we do see a mild recession, we'll likely see material correction in share prices and other risk assets.
Thirdly, the Chinese economy is too weak to offset the effects of a US recession.
And finally, unfortunately, this has important implications for Australia because it means that we face, I think, a challenging 18 months ahead.
Even if we do able to avoid a recession,
The RBA has very limited room to ease monetary policy quickly and China isn't going to be coming to our rescue.
So Angelina, I might end there and hand back to you.
Thank you both.
Well, gold will arrive indeed, eventually.
Now I've got some questions for you.
So the first one is, why is the supply side of the Australian economy growing at a slower rate than the demand side?
And behind the headline data, are any sectors facing chronic supply challenges?
What are the implications for where inflation is heading next?
Yeah, Angelina, I think that the key point here is that our productivity growth is very weak, and that's weighing on the supply side of the economy.
Because if you think of the supply side, it is a combination of population growth, particularly labour supply, which has so far been held up.
So that's helping the supply meet demand.
But now we're seeing that often.
But more importantly, productivity growth is actually, we're just not seeing productivity growth.
In the US, of course, we are seeing some productivity growth, as I mentioned, but in Australia, it is less than that.
And so I think that's the reason why the supply side of the economy is not being able to keep up with demand.
What of course we're seeing though is demand now is very clearly slowing.
And that is a reflection in the fact in the June quarter, consumer spending fell and business investment fell.
So I think that gap is starting to close between demand and supply.
And I think that ultimately will mean that we will be in a position for the RBA to cut interest rates, but probably not this year.
Well, that's a good segue into my next question.
Are the RBA influenced by the strategies of other central banks, particularly the Fed?
Yeah, they have to because the Fed is the largest economy in the world and it sets global interest rates.
Longer term interest rates are basically set out of the US and
The RBA can't ignore, Angelina, what the Fed's doing because the further we get away from interest rates in the US, the more implications that has, particularly for our exchange rate.
And I think that's one of the reasons, Angelina, why with our interest rates well below the US interest rates, our exchange rate has been as weak as what it has.
And of course, that in turn means that adds some inflation pressure.
into the economy.
So I think that definitely is the case that we can't get too far away from the Fed.
Yeah, so Paul, nominal Australian economic growth continues to run below trend at 1.5% last financial year, whilst GDP per capita has been negative for some time now.
So do you expect this local economic weakness to continue?
And if not, what's likely to drive an economic recovery from here?
No, I think it's going to remain.
week.
I think if we look at the second half of this year, there's some elements of stimulus are coming courtesy of federal and state government budgets.
We've got the income tax cuts which have started.
The early signs though, Angelina, are that a lot of those tax cuts are being saved because people are very cautious about the outlook and our confidence is still low.
But at the same time as well, we're getting cost of living relief, electricity rebates, we're getting some support for rent for rents, for lower income earners, state governments are doing various similar measures as well.
So I think there is some support there, but at the same time,
interest rates, some people are still moving off those very low interest rates as they move from their fixed rates to the current level of rates.
So that's working against us a bit.
And of course, the big one is the unemployment rate is rising, and that's going to make it harder as well.
So I think there's swings and roundabouts, but because of those fiscal measures by federal and state governments, that's why I think
I think the economy can avoid recession.
Do you believe the RBA are in control of local inflation at this juncture or are external factors such as energy and commodity supply constraints more likely to influence the future direction of inflation?
Well, that's a really good question because the RBA, as you know, hasn't raised interest rates as much as what most other central banks have.
And their reason for doing that is that they want to preserve as much of the gains of employment that we saw in the last couple of years.
And so they've tried to balance the reduction in inflation with
keeping a lid on the rise in unemployment.
So that's a trade off that they've been prepared to make.
And the biggest contrast is probably in New Zealand, where the central bank there actually decided that it would put much more weight on reducing inflation.
And as a result, pushed interest rates up a lot higher than Australia.
over one percentage point, 100 basis points.
And that's actually driven the New Zealand economy into a recession.
So the RBA wants to avoid that.
But you know, there's no free lunch in this.
It means that inflation is sticky, as I showed in that chart.
And you know, it means that inflation is going to take longer to come down than what it will in other economies.
And that raises the big question whether inflation expectations might start to
break out.
And if that happens, then the RBA is in a world of worry.
So far it hasn't happened, Angelina, but that's the thing that we're going to be really watching closely.
Paul, will the government's cost of living measures make a dent in the inflation rate?
I don't think so, because the economy, Angelina, is so weak.
As we've talked about, it's growing by less than 1% per capita.
It's falling.
Consumer demand is falling.
Business investment is falling.
So yes, it does add some growth into the economy, but the economy is growing below potential.
Potentially, for Australian economies, probably
two and a half percent, maybe.
We're way below that.
As a result, inflation, I think, ultimately will come down.
I think if it wasn't for those measures from the government, as I mentioned, we'd be in recession.
So again, it is a balancing act.
But no, I don't think those measures are really
creating a significant inflation impulse.
And in fact, when we look at some of those measures, they actually reduce the measured rate of inflation because of those electricity subsidies.
They actually reduce the rate of inflation in electricity prices.
So that I think is helpful as well.
And yes, it is only temporary.
But, you know, it's still at the end of the day, I think, working together with the RBA to get inflation down, albeit more slowly than what maybe we would like to see.
So do you think the RBA will cut or raise rates in the coming months?
Or is the status quo a more likely scenario?
I think, and Michelle Bullock, the Governor of the RBA, has made this very clear.
They think that markets are too optimistic about how quickly the RBA will be cutting.
They're guiding that the RBA will cut.
Well, the market is saying it will cut before the end of the year.
The RBA is saying that's too early.
And I think that's right, because as we showed in those charts, inflation is sticky.
And it's going to take a while for inflation to really come down and for the RBA to be confident that inflation is going to get to 2.5%, which is their target.
So my guess, Angelina, is that we'll start to see the RBA give some relief late, probably early next year.
Yep, yep.
So when do you believe the RBA will be confident the 2.5% headline inflation target is achievable?
And if and when they reach this position, how many rate cuts do you expect in the next cutting cycle?
I think because they haven't raised rates as much as everyone else, I think this will be a more shallow easing cycle than what we will see from the Fed.
So for example, financial markets are anticipating around 200 basis points of cuts from the Fed.
I think probably maybe about 125 basis points from the RBA.
And they'll probably get down to that level by the late next year.
And that would be consistent with inflation.
getting back to the target probably in early to mid-26.
So some way off, Angelina.
Right, early to mid-26.
Right, so how do you believe equity, fixed income and property markets will respond if the RBA starts cutting rates?
And are there any other noteworthy investment implications of a shift in the direction of rate expectations?
I think the markets tend to sort of flip flop their pricing.
At the moment, I think they're very focused on the fact that the economy is as weak as what it is.
So I think they'll persist with this view that, particularly with the Fed cutting interest rates,
that they expect the RBA to be following.
The next important reading for the RBA will be the September quarter inflation.
That, I think, will be moving in the right direction, partly because of those measures from federal and state governments to lower the cost of rents and electricity and so on.
that will be helpful, but I don't think it's going to be enough to change the line from the RBA.
I think the market ultimately will come to the view that the RBA is going to come to the party later rather than sooner.
You might have touched on this in your presentation, the Australian unemployment remains relatively low at 4%.
Why has employment been so resilient today?
Do you expect this resilience to continue looking forward?
I think with the labour market and unemployment, the labour market is really softening, job vacancies are falling.
companies, as we mentioned, are still facing cost pressure.
And so they're looking to cut costs and labour demand is part of that.
So the unemployment rate has been gradually rising.
It's in the low fours, but I think we will see it move up towards the high fours before it peaks.
So that's why I say I think the economy still faces a challenging time.
And even when the RBA starts to ease monetary policy, we know that monetary policy works with lags.
And as a result, the labour market tends to be quite lagging as well.
So I think we've got to expect a further softening in the labour market over the next six months, at least.
And are there any non-consensual economic outlook scenarios that investment markets are dismissing as unlikely at this juncture, which you believe warrant greater attention?
I think there's always things that come out of the woodwork that surprises Angelina, and that's why we have to be quite humble with our forecasts, and indeed why, as I mentioned, financial market pricing tends to flip around quite a bit.
And at the moment, we're very much data dependent.
All central banks are saying,
that they're data dependent, that is that they're looking for key data to guide them as to what will be, how quickly and to what extent they will be able to ease monetary policy.
And what we've seen, of course, in the last couple of years, we've seen a pandemic, which is once in 100 year event,
We've seen a war with the invasion of Russia and Ukraine.
We've seen other supply side shocks.
We've seen very unusual situation in the labour market where the unemployment rate got down to 50 year lows in most economies.
So what we're doing with Angelina is very exceptional
situation.
And then of course throwing a US presidential election where you've got a very unusual combination of a sitting Vice President running up against a former Vice President.
So this is another example of situations which are highly unusual.
And who knows, Angelina, to be honest, what might be the next
highly unusual shock that comes along to change our views and change where markets are taking us.
Yeah, like a less worn event.
You can't predict that.
So how can Australian investors best position themselves to benefit from your expected economic outlook?
I know it's hard to predict.
Well, I think
And speaking personally, I think we need to be very cautious because we've had an extremely strong risk on rally for an extended period of time.
We've seen valuations in risk assets, so share prices and credit products becoming quite exceptional, looking very stretched.
And earnings expectations that underpin that look very optimistic when we consider that economies are slowing, unemployment is rising.
And no economy really yet can say confidently that they've got inflation back in the bag.
So,
My advice was be very, very cautious because we've had, because of that backdrop, I see risk being more on the downside rather than the upside, at least until the easing of monetary policy by the theatre and others
fast to get traction.
But that could take some time.
So I think it is going to be, it is a challenging investment backdrop because of those reasons, Angelina.
It is a very challenging environment.
So do you have any advice for households aiming to weather the high interest rate environment?
It's challenging, there's no doubt, and I know from many friends and younger people than me
and just how tough it is at the moment, either because of the high rents, the difficulty of finding properties to rent, and then for home, those who have borrowed come into the housing market over the last couple of years when interest rates were really low, and to see those interest rates go up so much, it's really tough.
I can remember back when I was a lot younger and I had interest rates of around 18% on my mortgage and I really didn't know how things were going to work out.
All the advice I guess I can give Angelina is just hang in there, just do whatever you can to cut your costs, but stay positive because ultimately cycles turn.
and these interest rates will be lower.
Just stay positive and we'll all come out of this and we've learned a lot along the way, but it certainly is a challenging time.
It is.
And to conclude, Paul, can you please share an investment or economic lesson you've learned in your position as Sankop's chief economist?
Well, I think we just have to be humble because, Angelina, if we can get things right 50% of the time, that's a good result.
And particularly because of this surprising environment that we've been living in since the pandemic, we're not in a stable forecasting platform.
And so that means, unfortunately, we're constantly revising our forecasts and revising our opinions.
And so what I do is I try and read as widely as possible and get as wide range of views as possible because no one is the single font of knowledge.
And the more that we sort of canvas wide-ranging views, even if they are challenging our view and don't even agree with us, that will make us think more deeply.
And I think that's the way it's going to be for quite a long time.
Well, thank you so much, Paul.
You've been very generous with your time and knowledge.
And that brings us to the end of our Investment Markets September 2024 investor webinar.
The economic outlook: global, national and local
About this presentation
In this economic update from the Chief Economist at Suncorp Group, Paul Brennan covers:
- History suggests a US soft landing will be hard to achieve, even with the Fed starting to ease this month.
- Markets are not priced for a recession, even a mild one would likely see a material correction in share prices and other risk assets.
- The Chinese economy is too weak to offset the effects of a US recession.
- Australia faces a challenging 18 months, even if it avoids a recession, as inflation is limiting the RBA’s degrees of freedom and China isn’t coming to the rescue.
Disclaimer
- The presentations made during this seminar are for informational and promotional purposes only.
- Any comments made or information provided does not consider the appropriateness for you having regard to your particular objectives, personal/financial situation and needs. Before investing you should consider independent professional financial advice.
- No comments made or information provided constitutes advice, an invitation, or an offer to buy any security or other financial product or engage in any investment activity.
- All securities and financial products involve risks.
- Past performance of any product is not a reliable indication of future performance.
- Read carefully the governing documents of a product’s offering such as its PDS or information memorandum.
- InvestmentMarkets does not vet, endorse or recommend any product the subject of the presentations and is only facilitating the exposure of the product.
- These presentations were made as at 24-26 September, 2024 and therefore relevant facts, the economic environment , governing documentation and the law upon which they were based may change after that date such that the accuracy and reliability of their content may be affected.
Featuring

Tags
More Videos